
Choice Hotels International (CHH) Sees Franchise Momentum, Is The Stock Still Trading At A Discount?
Choice Hotels International (CHH) is back on investors’ radar after a fresh upswing in franchise agreements, strong hotel retention, conversion-led development, and expanding international operations that highlight how its asset-light model is being put to work.
Recent trading has been choppy rather than euphoric. Choice Hotels International’s share price has risen over the year, with a 30 day share price return of 8.5% and a year to date share price gain of 15.7%. The 1 year total shareholder return of 20.9% contrasts with a slightly negative 3 and 5 year total shareholder return, which hints that momentum has picked up only more recently.
Scan how Choice Hotels International stacks up against other asset-light players and cash generative franchises with our hand picked 18 high quality undiscovered gems to spot what the market may be missing.
Choice Hotels International has already rewarded investors who were willing to sit through a choppy ride. The harder call now is whether you add at today’s price or wait for the next pullback.
Most Popular Narrative: 3% Undervalued
The most followed narrative pegs fair value for Choice Hotels International at $114.60, slightly above the latest close of $111.16. This frames today’s price as only a modest discount that depends heavily on how the franchise model and technology stack perform over the next few years.
The reversion to an asset light, capital recycling model, including an 80% decline in hotel development outlays in the first half of 2026 and plans to recycle roughly US$650 million of real estate capital starting in 2027, is intended to lift free cash flow and support higher returns on invested capital.
See why 2 investors see Choice Hotels International as 3% undervalued.
Result: Fair Value of $114.60 (UNDERVALUED)
Still, the bullish case for Choice Hotels International leans heavily on closing its roughly 300 basis point U.S. RevPAR gap and on asset light returns improving despite weaker financial strength scores.
Find out about the key risks to this Choice Hotels International narrative.
Another View: What Multiples Say About Choice Hotels International
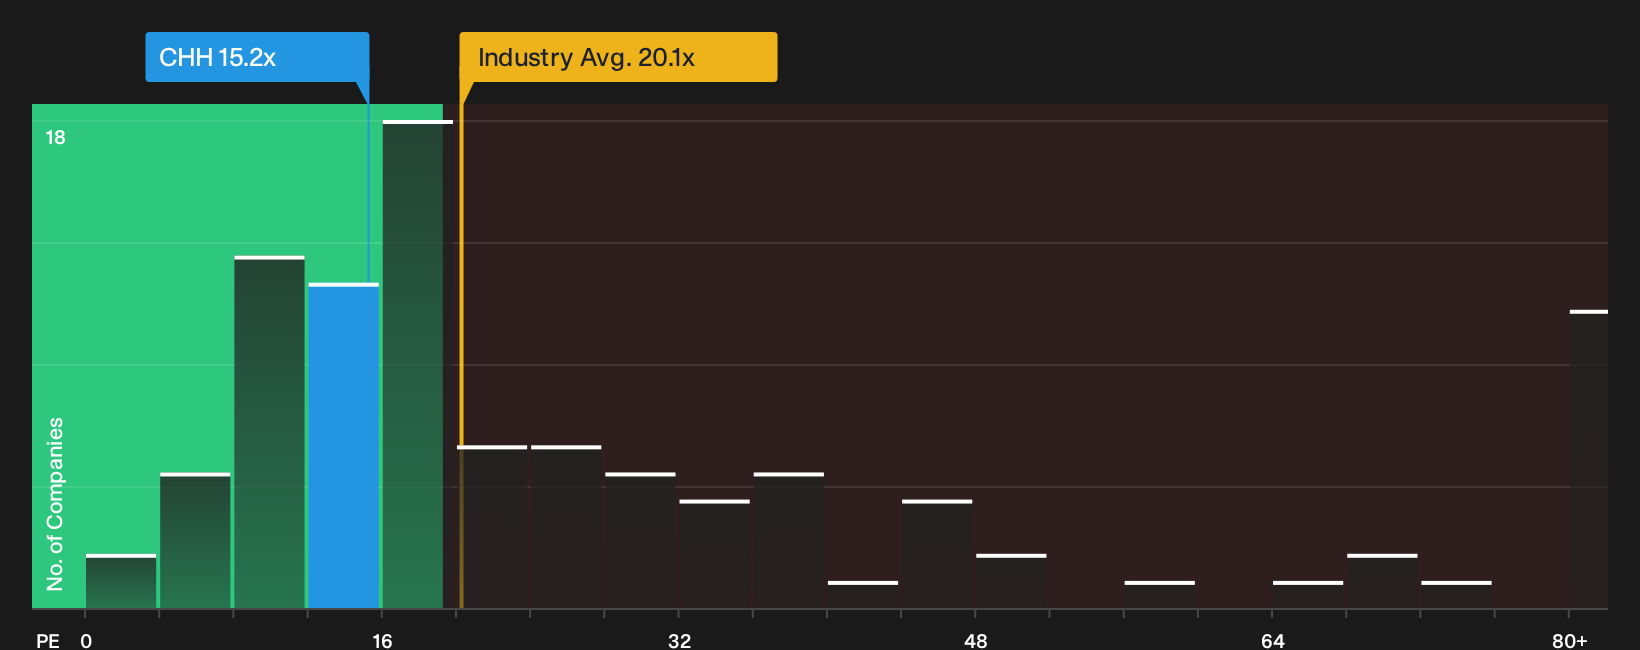
There is a different read when you zoom out from fair value targets and look at what buyers are actually paying for Choice Hotels International today. The stock trades on a P/E of 15.2x, below both the US market at 18.2x and the US Hospitality sector at 20.7x, and also under its own fair ratio of 17.7x.
That gap suggests the market is pricing in extra risk or lower durability of earnings, even though analysts see profit still growing. The question for you is whether this discount reflects real balance sheet concerns and one off items, or whether it is an opening for patient investors to step in. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Choice Hotels International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Choice Hotels International so far. Review the numbers, consider both sides, then anchor your own stance with 4 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Choice Hotels International?
If you stop with Choice Hotels International, you only see one angle. Broaden your watchlist and give your future self more options to work with.
- Target potential mispricing by scanning a curated pool of quality opportunities through the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on balance sheets that look resilient using the list of solid balance sheet and fundamentals (25 results).
- Boost your income focus by lining up companies that offer meaningful yields through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com