
Jabil (JBL) Stock Dropped, So What Is Behind The Attention Now?
Jabil (JBL) just paired strong Q4 fiscal 2026 earnings with a new capital return plan, highlighting AI infrastructure demand, fresh buybacks, and a continued quarterly dividend that keeps cash flowing back to shareholders.
Despite the upbeat Q4 and capital return plans, Jabil’s recent share price has cooled, with the stock down 13.44% over 90 days and 4.93% over the past month. At the same time, the year-to-date share price return is 13.45% and the 5-year total shareholder return is 324.39%, which suggests that long-term momentum remains intact while shorter-term sentiment looks more cautious around the US$272.72 level.
Scan beyond Jabil and spot other plays riding similar technology and capital return themes with our hand picked 54 AI infrastructure stocks.
Jabil has the earnings story, the AI exposure, and a fresh capital return plan, yet the share price has eased back. Are investors paying a fair price for that package today?
Most Popular Narrative: 36% Undervalued
At a last close of $272.72 against a narrative fair value of $425, Jabil is framed as materially underpriced. That gap hinges on how convincingly it turns AI infrastructure, regulated industries and cash returns into sustained earnings power under a 9.15% discount rate.
The main thing that has to go right is that Jabil converts the guided ramp in AI infrastructure, regulated industries programs and automation into sustained margins while managing supply constraints and working capital.
The numbers on AI-related revenue growth, segment guidance, free cash flow generation and large ongoing buybacks together imply that the current share price treats Jabil as undervalued and does not fully reflect this bullish setup.
See why 37 investors see Jabil as 36% undervalued.
Result: Fair Value of $425 (UNDERVALUED)
Still, tight supply for key AI components and slower inventory normalization could choke Jabil’s Intelligent Infrastructure ramp and blunt the bullish valuation story.
Find out about the key risks to this Jabil narrative.
Another View: What Jabil’s P/E Is Telling You
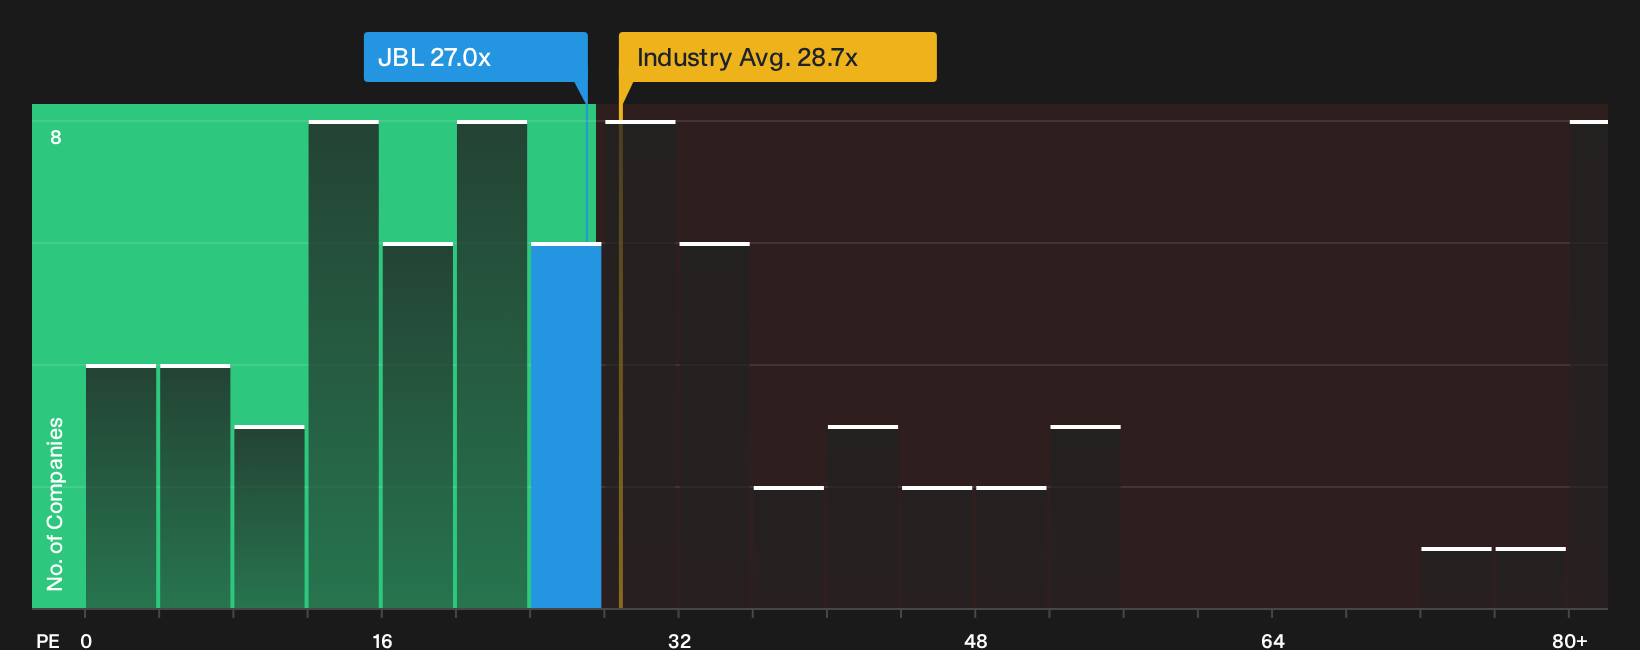
The first narrative leans on cash flows and long term AI earnings power. A simple P/E check paints a more mixed picture. Jabil trades at about 27x earnings versus roughly 25.8x for close peers and 28.7x for the wider US Electronic group.
Our fair ratio for Jabil sits higher at 37.5x, which implies the market is assigning a lower multiple than that model suggests while still asking investors to accept a premium to immediate peers. Is that gap a margin of safety or a reminder that expectations are already rich if the AI and buyback story hits any bumps?
For a closer look at how this earnings multiple stacks up against peers and that higher fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or a clear message from Jabil so far. If you want to move quickly and build your own stance from the underlying numbers, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Jabil?
If Jabil has sharpened your focus on quality and price, do not stop here. Broaden your watchlist with data driven ideas that others could overlook.
- Target potential mispricing and compare quality with a curated set of 29 high quality undervalued stocks that pair fundamentals with compressed expectations.
- Strengthen your income stream by reviewing 5 dividend fortresses built around higher yields that still lean on underlying cash generation.
- Dial back risk without stepping away from opportunity by scanning 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com