
Gene Technology Deals Might Change The Case For Azenta Stock
- Azenta reported that it has invested in its GENEWIZ unit through an exclusive license for Elegen's cell free DNA manufacturing technology and the purchase of SynPlexity, which supplies high throughput gene libraries.
- The combination of Elegen's cell free DNA platform and SynPlexity's pooled gene assembly gives Azenta a broader set of tools to support synthetic biology, protein engineering, and AI driven drug discovery projects.
- Investors may now evaluate how Azenta's investment narrative could be influenced by GENEWIZ's expanded cell free DNA and gene library capabilities.
Scan how Azenta's move into AI assisted gene design compares with other high throughput biology plays by zeroing in on 34 healthcare AI stocks.
Azenta Investment Narrative Recap
To own Azenta, you need to believe its mix of sample management and multiomics services can eventually translate forecast revenue growth and a shift toward profitability into durable cash generation. The near term hinge remains whether end market softness and order delays ease enough for that forecast earnings ramp to show up in reported numbers.
The biggest immediate risk is that spending pressure at pharma and biotech clients keeps weighing on higher margin equipment and legacy sequencing work, so losses linger while Azenta keeps investing. The GENEWIZ expansion adds potential where synthetic biology and AI driven design are growing, but it does not erase that execution risk.
The fresh announcement that matters most here is the exclusive Elegen license paired with the SynPlexity acquisition inside GENEWIZ. That package targets higher value workloads like sequence verified constructs for antibody discovery and large pooled libraries that fit directly alongside Azenta's existing NGS and sample storage services.
For catalysts, investors will probably watch the upcoming Q4 FY 2026 call for concrete milestones. Items to listen for include how quickly Elegen based capacity is deployed near key customers, whether SynPlexity's libraries start to feed incremental orders, and how management plans to balance this heavier R&D and infrastructure spend against the current loss making profile.
Azenta's current analyst narrative points to forecast revenue of $691.8 million and earnings of $29.5 million by 2029. This outlook is built on assumed yearly revenue growth of 4.1% and an earnings move of about $141.6 million, from a loss of $112.1 million today into positive territory.
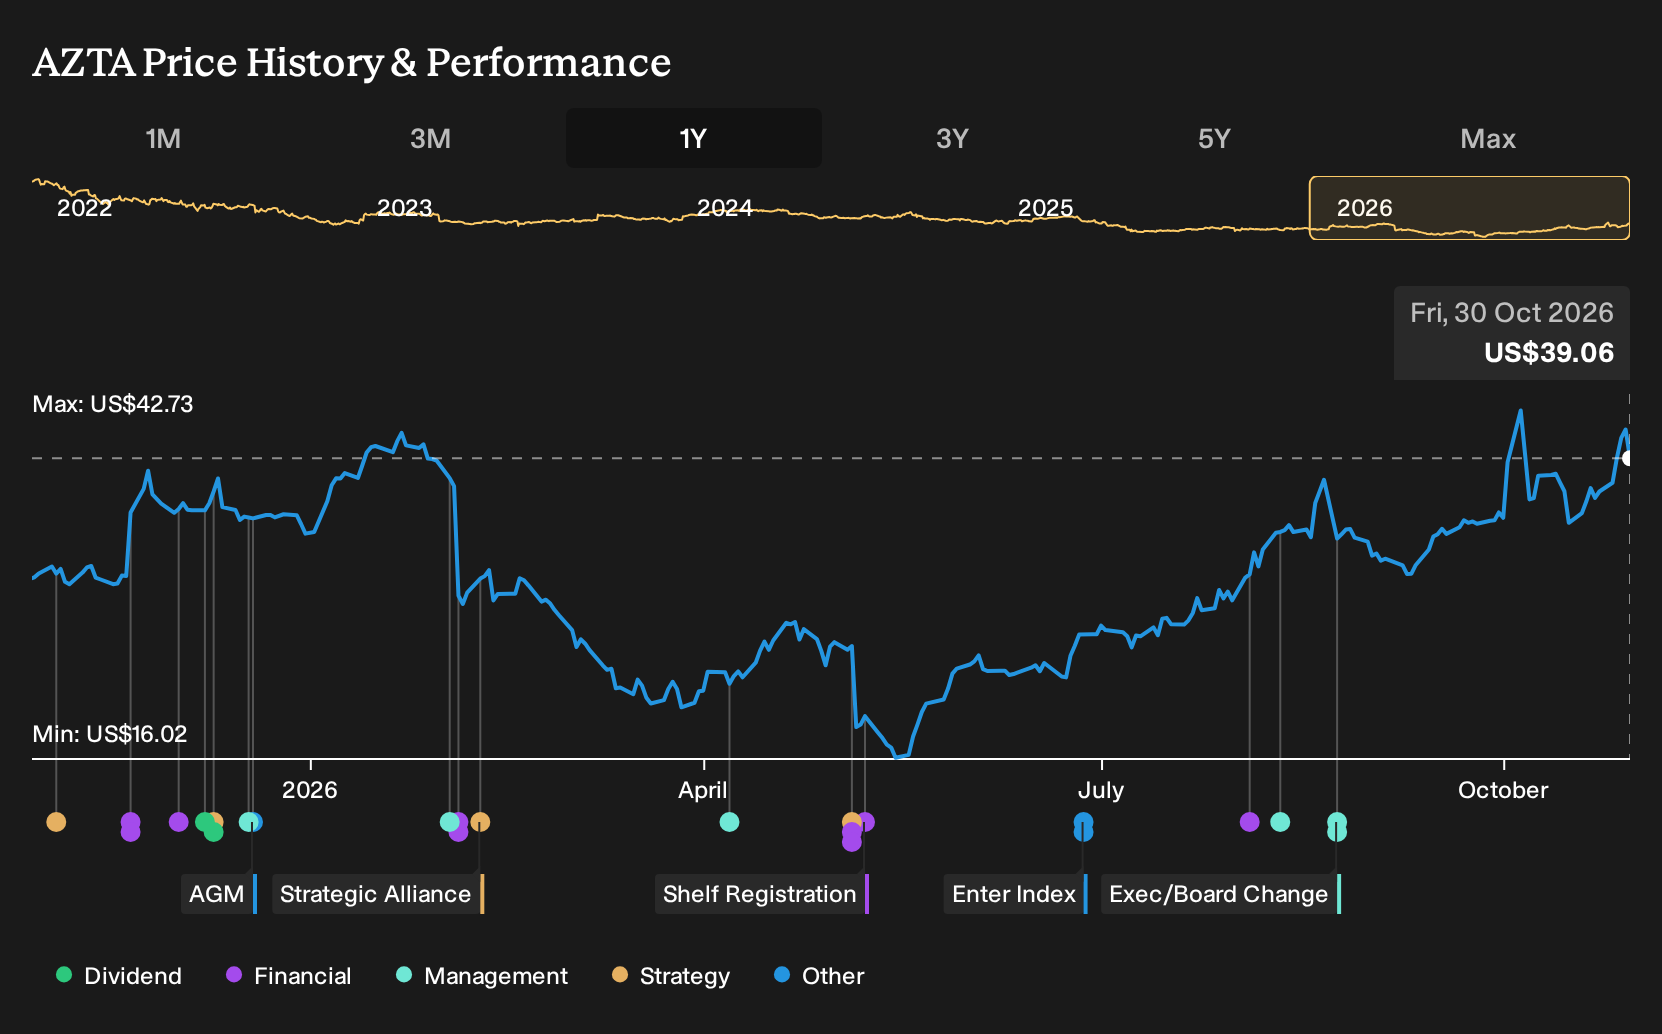
Discover why Azenta's fair value appears to be broadly aligned with its current market price.
Exploring Other Perspectives
One alternate lens focuses on margin pressure rather than growth potential. The lowest analysts were already sketching a tougher path for Azenta, with revenue only reaching about US$696.1 million and earnings around US$24.6 million by 2029. Those forecasts came before this GENEWIZ DNA move. As you weigh how these new tools affect that more cautious story, your own view may shift.
Explore another Azenta fair value estimate, including one that suggests as much as 42% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Azenta research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Azenta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Azenta's overall financial health at a glance.
Looking For More Ideas Beyond Azenta?
If the Azenta story has sharpened your thinking about risk, balance sheets, and long term potential, use that same lens to sort through a wider opportunity set with the Simply Wall St Screener.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If downside protection matters to you, filter for defensiveness first by checking companies in our 30 resilient stocks with low risk scores that score well on stability.
- When you want potential mispriced opportunities with strong fundamentals, cast a wider net across the 18 high quality undiscovered gems and see what else deserves a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com