
What Is Drawing Attention To Sherwin Williams (SHW) After Its Latest Update?
Why the latest Sherwin-Williams earnings moved the stock
Sherwin-Williams (SHW) just put fresh numbers on the table, with third quarter earnings, updated full year guidance, and a confirmed dividend all hitting in quick succession.
Investors now have a fuller picture of how stronger revenue, tighter profitability, and management's softer demand commentary fit together for the paint and coatings group.
The latest quarter arrived against a backdrop where Sherwin-Williams shares have been treading water rather than breaking out, with a 1-year total shareholder return that has slipped 2.66% even as the 3-year total shareholder return is up 36.14%. Recent earnings, a reiterated full year outlook and a confirmed dividend have kept long term holders engaged. However, the modest 1-day share price gain of 0.76% around the results suggests investors are weighing revenue momentum against ongoing cost and demand risks rather than rushing to re-rate the stock.
Compare Sherwin-Williams' earnings reaction with peers and hunt for coatings and materials stocks with stronger risk reward profiles using our curated 30 resilient stocks with low risk scores.
Sherwin-Williams just posted solid sales but softer profitability, and the share price barely moved. Is this a reasonable entry now, or does it make more sense to wait for a cheaper valuation before committing fresh capital?
Most Popular Narrative: 12% Undervalued
Sherwin-Williams last closed at $332.61 while the most followed narrative estimates fair value at $378.33. This frames the latest earnings move as a debate over whether the current price fully reflects the longer term story.
The ongoing plan to open 80 to 100 net new Sherwin-Williams Paint Stores Group locations each year on a path toward roughly 6,000 stores, alongside pruning of underperforming sites, increases the reach of the controlled distribution network and can lift revenue and operating earnings as more professional and commercial customers are brought into the system.
See why 43 investors see Sherwin-Williams as 12% undervalued.
Result: Fair Value of $378.33 (UNDERVALUED)
Still, prolonged softness in housing and DIY demand, along with rising raw material costs and only flat gross margin guidance, could put pressure on the Sherwin-Williams narrative.
Find out about the key risks to this Sherwin-Williams narrative.
Another View: Sherwin-Williams on Earnings Multiples
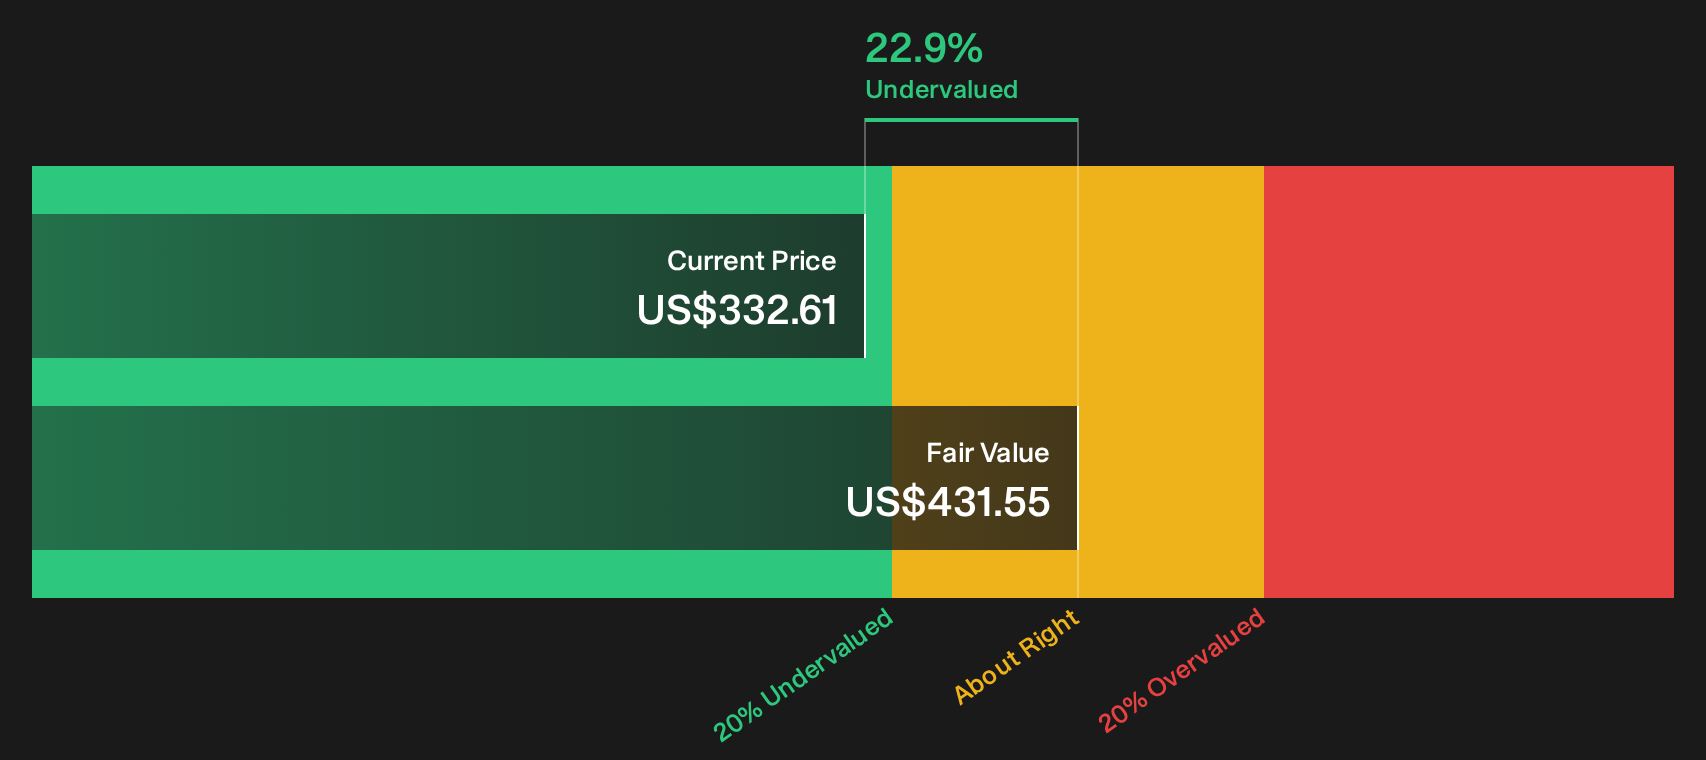
The SWS DCF model suggests Sherwin-Williams at $332.61 is trading below an estimated future cash flow value of $431.55, which points to an undervalued outcome. That appears to clash with concerns about slower earnings growth compared with the wider US market. Which signal should carry more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals in the Sherwin-Williams story, with both concerns and bright spots, make this a moment to move quickly and test the numbers yourself using the 3 key rewards and 2 important warning signs.
Looking for more Sherwin-Williams style investment ideas?
If Sherwin-Williams has sharpened your focus on quality and price, do not stop here. Use the Simply Wall St screener to spot opportunities before they feel obvious to everyone else.
- Zero in on quality at a discount by filtering for companies that match your criteria through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding opportunities using the 5 dividend fortresses.
- Protect downside risk by scanning for businesses with cleaner balance sheets and sturdier fundamentals via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com