
Learn Why The Bull Case For Hitachi (TSE:6501) Could Change Following Profit Hit From Cost Overrun
- Hitachi reported half year sales of ¥5,614.0b for the period to September 2026, with net income of ¥416.6b and basic EPS from continuing operations of ¥93.2.
- The board lifted the interim dividend to ¥32 per share and maintained a raised full year earnings outlook, even as one off project costs weighed on recent profit.
- We will now look at how Hitachi’s investment narrative is affected by lower recent profit, despite raised guidance and a higher dividend.
Scan how other industrial and AI infrastructure players are priced by running the 39 power grid technology and infrastructure stocks alongside this latest move from Hitachi and its push into digital services.
Hitachi Investment Narrative Recap
To own Hitachi, an investor needs to be comfortable with a story built around power grids, digital services and AI driven infrastructure rather than short term quarterly swings. The latest half year showed record sales of ¥5,614.0b but lower net income and EPS as one off project costs hit profit, so the key question is execution quality, not demand.
Right now the most important short term catalyst is whether raised full year guidance and ongoing demand in Energy and digital services hold up in the face of large capex and complex projects. The biggest risk is that cost overruns, geopolitical issues or softer customer investment, especially where tariffs bite, chip away at margins while these investments scale.
The launch plan for Hitachi Digital Inc. looks most relevant to this earnings beat and miss mix. Management intends to combine GlobalLogic and Hitachi Digital Services under one roof from April 2027, with a focus on cloud, data and AI projects that link physical infrastructure to software based services for clients.
For a shareholder, that move ties directly into the Lumada and HMAX catalysts because it concentrates engineering, consulting and AI capabilities into a single operating platform. It also raises execution risk, since integration, talent investment and acquisitions can weigh on costs if revenue from digital transformation, Physical AI and related service lines does not keep pace.
Hitachi's narrative projects ¥14,382.3b revenue and ¥1,328.5b earnings by 2029. This is based on an assumed 9.2% yearly revenue growth and an earnings increase of about ¥528.9b from ¥799.6b today.
Uncover why Hitachi's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
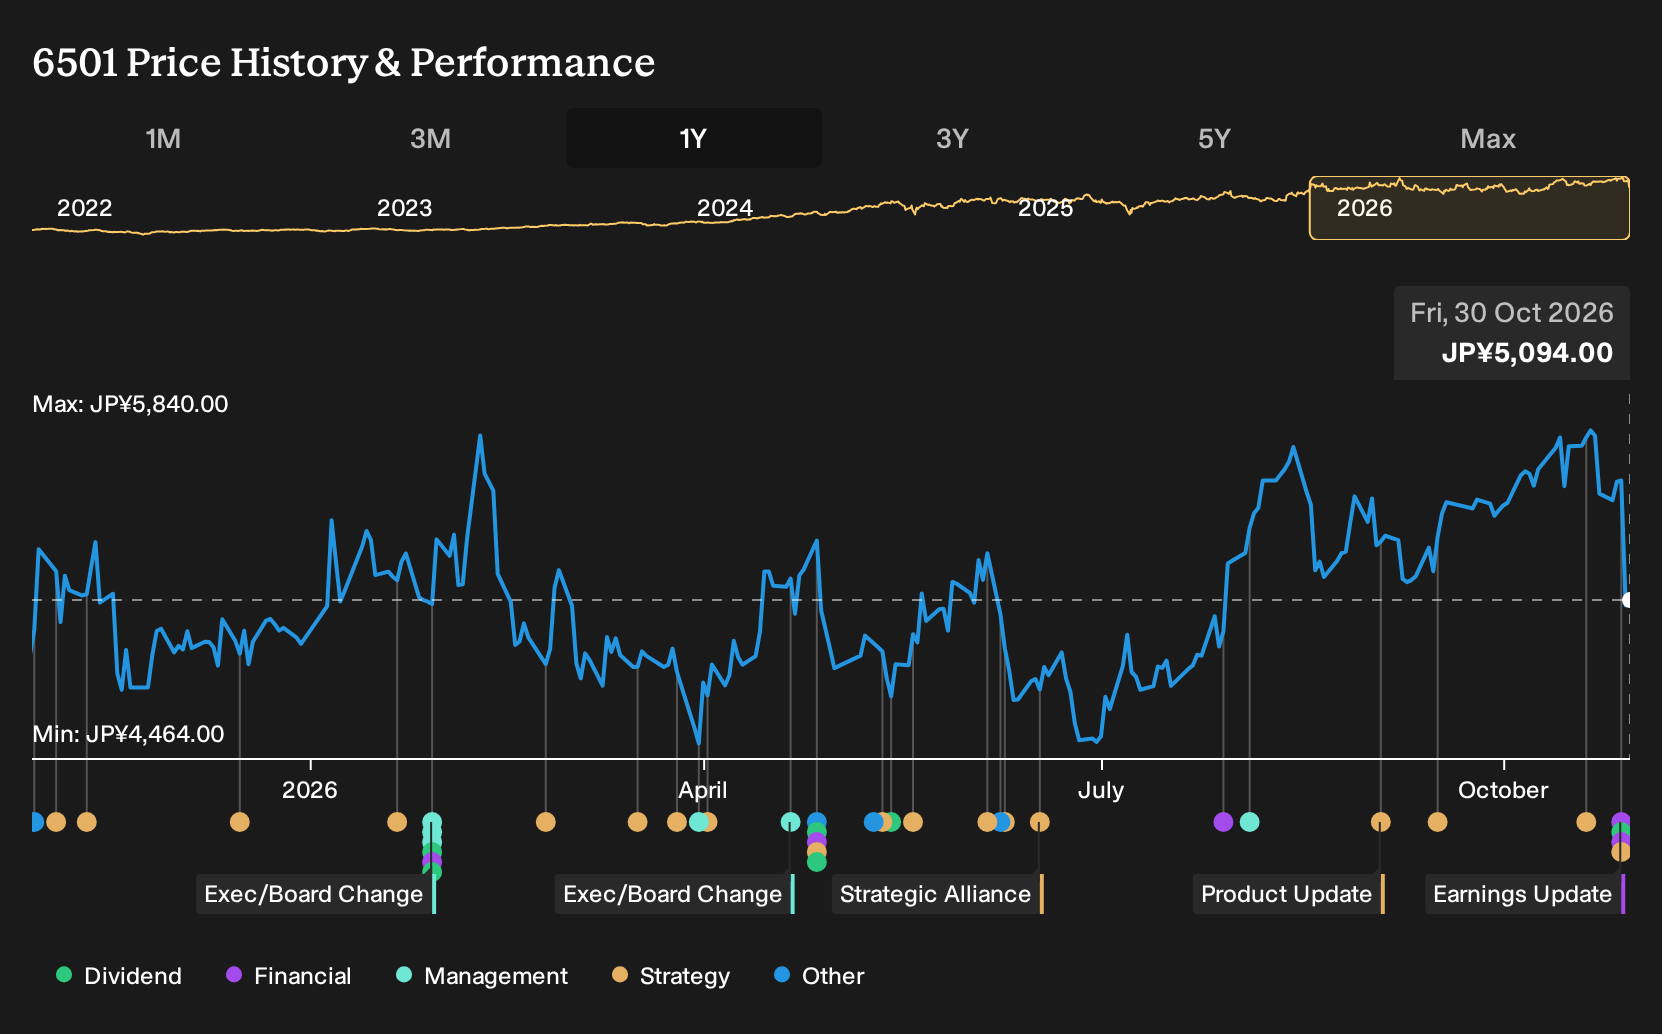
Exploring Other Perspectives
One optimistic thread in the alternate Hitachi story leans hard on AI driven efficiency. Those analysts were pencilling in revenue of ¥16,106.8b and earnings of ¥1,517.6b by 2029, well above the consensus path. You can treat this half year profit dip, raised guidance and higher dividend as a live test of that upbeat view. Explore both sets of assumptions and decide which is closer to how you think Hitachi can execute.
Explore 3 other Hitachi fair value estimates, including one that suggests as much as 46% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Hitachi research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Hitachi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hitachi's overall financial health at a glance.
Looking for more investment ideas beyond Hitachi?
If the Hitachi story has sharpened how you think about risk, income and balance sheet strength, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want income that does more of the heavy lifting, consider higher yielding opportunities through 27 dividend fortresses that might better match your payout goals.
- If capital protection and resilience are higher on your checklist right now, focus on steadier businesses by filtering for 24 resilient stocks with low risk scores that align with a more cautious playbook.
- When you are hunting for quality that the crowd may be overlooking, widen the search with 71 high quality undiscovered gems that could fit a more contrarian watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com