
Learn Why The Bull Case For Arcutis Biotherapeutics (ARQT) Could Change Following Earnings Beat
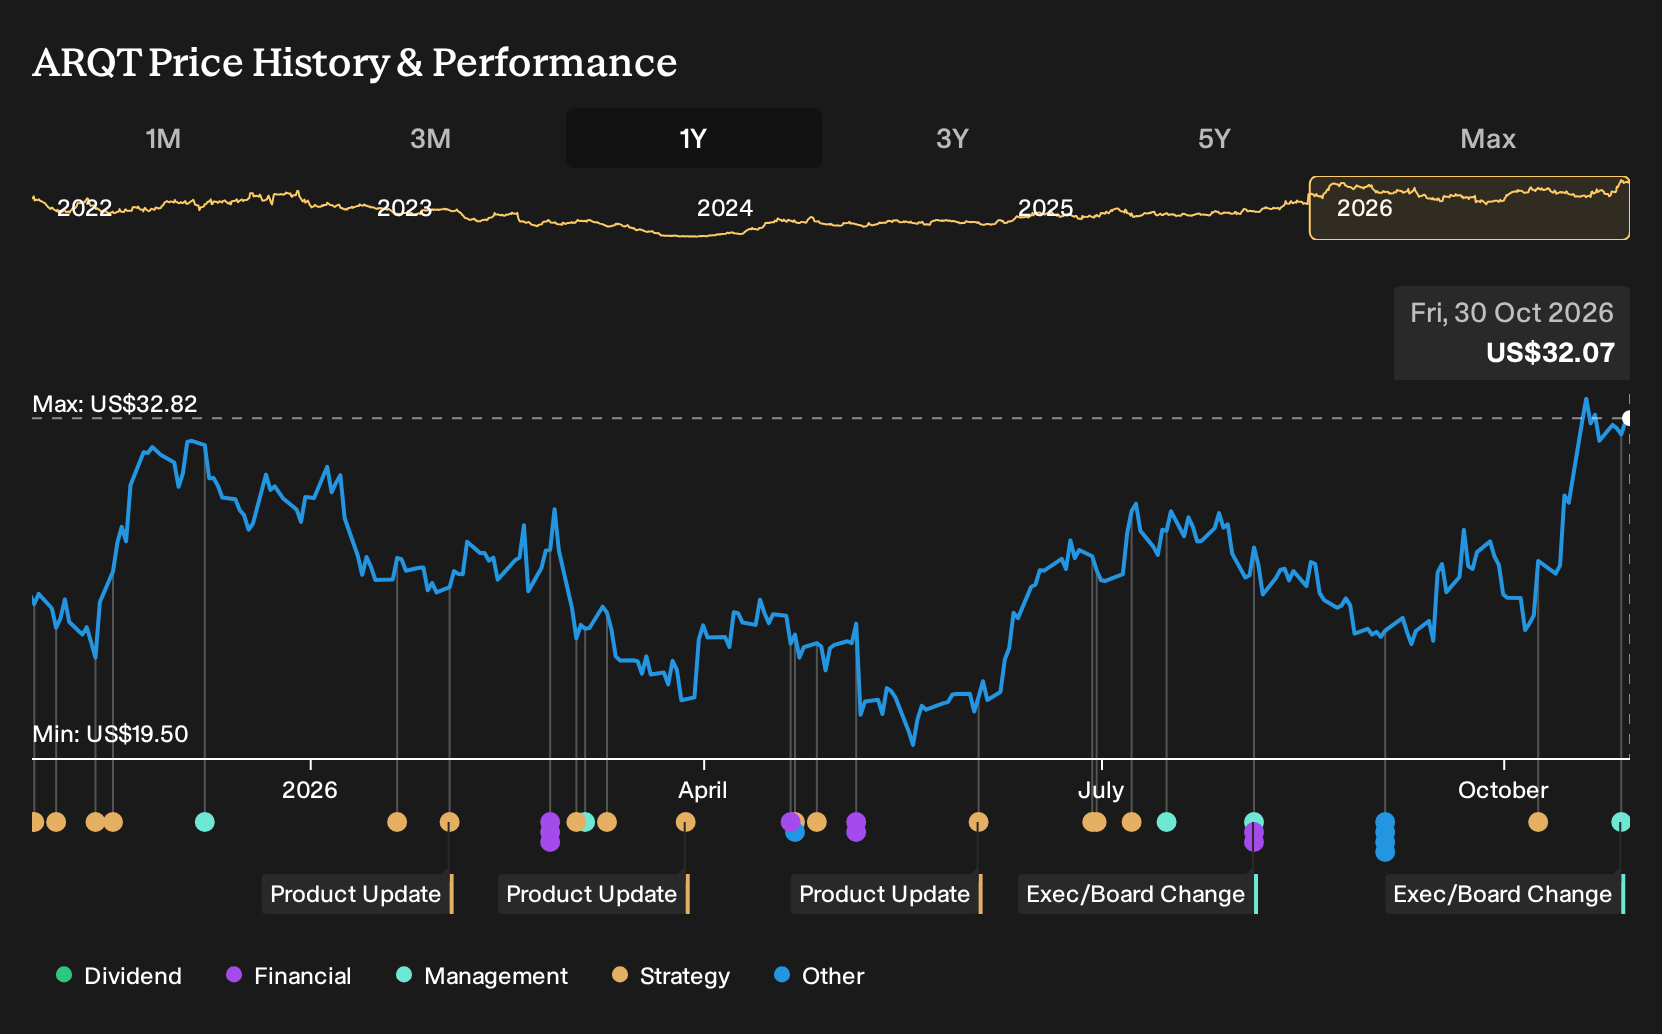
- Arcutis Biotherapeutics recently appointed Rob Scott, MD, a veteran pharmaceutical executive with decades of development and C-suite experience, to its board and Nominating and Corporate Governance Committee as a Class II director through the 2028 annual meeting.
- Expectations for Arcutis Biotherapeutics to post quarterly earnings of $0.17 per share, with revenue projected to be 42.8% higher year-over-year, highlight how execution on its dermatology portfolio remains central to the story.
- We will now look at how Arcutis Biotherapeutics' expected earnings performance could reshape the broader investment narrative around the business.
Arcutis Biotherapeutics Investment Narrative Recap
To own Arcutis Biotherapeutics, you need to buy into a dermatology story that leans heavily on ZORYVE and its follow on uses. The key short term catalyst is execution on the current launch and label expansion, supported by expected quarterly EPS of $0.17 and revenue that consensus sees 42.8% higher year over year.
The biggest risk is still concentration in one franchise alongside high R&D and SG&A needs. Rob Scott’s appointment does not change that in the near term. It matters more for longer horizon governance and development depth than for whether the next few quarters of ZORYVE demand and payer coverage meet expectations.
The fresh piece of news that ties most directly into this setup is Rob Scott joining the Arcutis Biotherapeutics board and its Nominating and Corporate Governance Committee. His background running development at AbbVie and Amgen reflects deep experience in scaling specialty products where label management, safety data and payer evidence can significantly influence uptake.
For you as a shareholder, this board change feeds into two live questions. Can Arcutis keep translating ZORYVE’s positioning in non steroidal topical care into sustained prescription trends? And can it do that while keeping spending and funding choices under control, given reliance on higher risk external borrowing and the need to support a relatively thin pipeline?
Arcutis Biotherapeutics' current analyst storyline points to revenue of $903.5 million and earnings of $313.9 million by 2029. That path assumes 24.9% yearly revenue growth and an earnings step up of about $285.4 million from $28.5 million today.
Uncover why Arcutis Biotherapeutics' fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value views on Arcutis Biotherapeutics from three Simply Wall St Community members span a wide band, from US$38.38 to about US$93.04, so you are seeing very different takes on what the shares might be worth. Set that against ZORYVE concentration risk, payer uncertainty and the new board expertise, and then explore several contrasting viewpoints before committing capital.
Explore 2 other Arcutis Biotherapeutics fair value estimates, including one that suggests as much as 190% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Arcutis Biotherapeutics research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arcutis Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arcutis Biotherapeutics' overall financial health at a glance.
Looking for more Arcutis Biotherapeutics sized ideas?
If you want to put Arcutis Biotherapeutics in context, it helps to line it up against other stocks that match your preferred style, whether that is value, resilience, or balance sheet strength.
- For investors who like paying less for quality, consider screening for potential value opportunities using 29 high quality undervalued stocks that fit tighter fundamental criteria.
- If durability matters most to you, focus on businesses with cleaner finances through a targeted list of solid balance sheet and fundamentals (25 results) that can help filter out weaker profiles.
- For a calmer ride across market cycles, narrow your watchlist to companies with steadier risk characteristics using a curated 30 resilient stocks with low risk scores tailored to resilience first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com