
How Investors May Respond To Luzerner Kantonalbank (SWX:LUKN) Higher Nine Month Profit
- Luzerner Kantonalbank AG reported net income of CHF 242.74 million for the nine months to 30 September 2026, compared with CHF 223.34 million in the same period a year earlier.
- The increase in nine month profit indicates that Luzerner Kantonalbank is managing its core banking activities and cost base in a way that supports earnings resilience.
- The next area of focus is how Luzerner Kantonalbank's higher nine month net income might influence the broader investment narrative around the bank.
Compare Luzerner Kantonalbank's earnings momentum with a curated group of resilient financial stocks highlighted in our 218 resilient stocks with low risk scores to see how its profile stacks up in terms of quality and risk.
What Is Luzerner Kantonalbank's Investment Narrative?
Luzerner Kantonalbank’s story appeals most if you like steady, fairly concentrated banking franchises that lean on core Swiss lending and fee income rather than big swings in trading or investment banking. The CHF 242.74 million nine month net income print slots neatly into that picture. It points to solid execution on costs and credit quality. In the short term, that kind of earnings profile supports ongoing reinvestment in digital channels and risk systems without stretching capital, given the business model is relatively traditional and capital intensive by design.
Shareholders also need to be comfortable with what this is not. Luzerner Kantonalbank is not a fast growth story. Earnings grew 4.6% over the past year and profit margins moved from 43.2% to 45%. Revenue is forecast to rise 5.78% a year, while return on equity is described as low at 7.2%. The recent earnings news fits this pattern. It reinforces a slow compounding, dividend paying profile, and leaves the main swing factors around loan demand, funding costs and any change in credit losses.
That said, the appealing mix of high quality earnings and a 2.09% dividend yield still sits beside one uncomfortable wrinkle that could matter a lot if...
There's only one way to know the right time to buy, sell or hold Luzerner Kantonalbank. Head to Simply Wall St's company report for the latest analysis of Luzerner Kantonalbank's Fair Value.
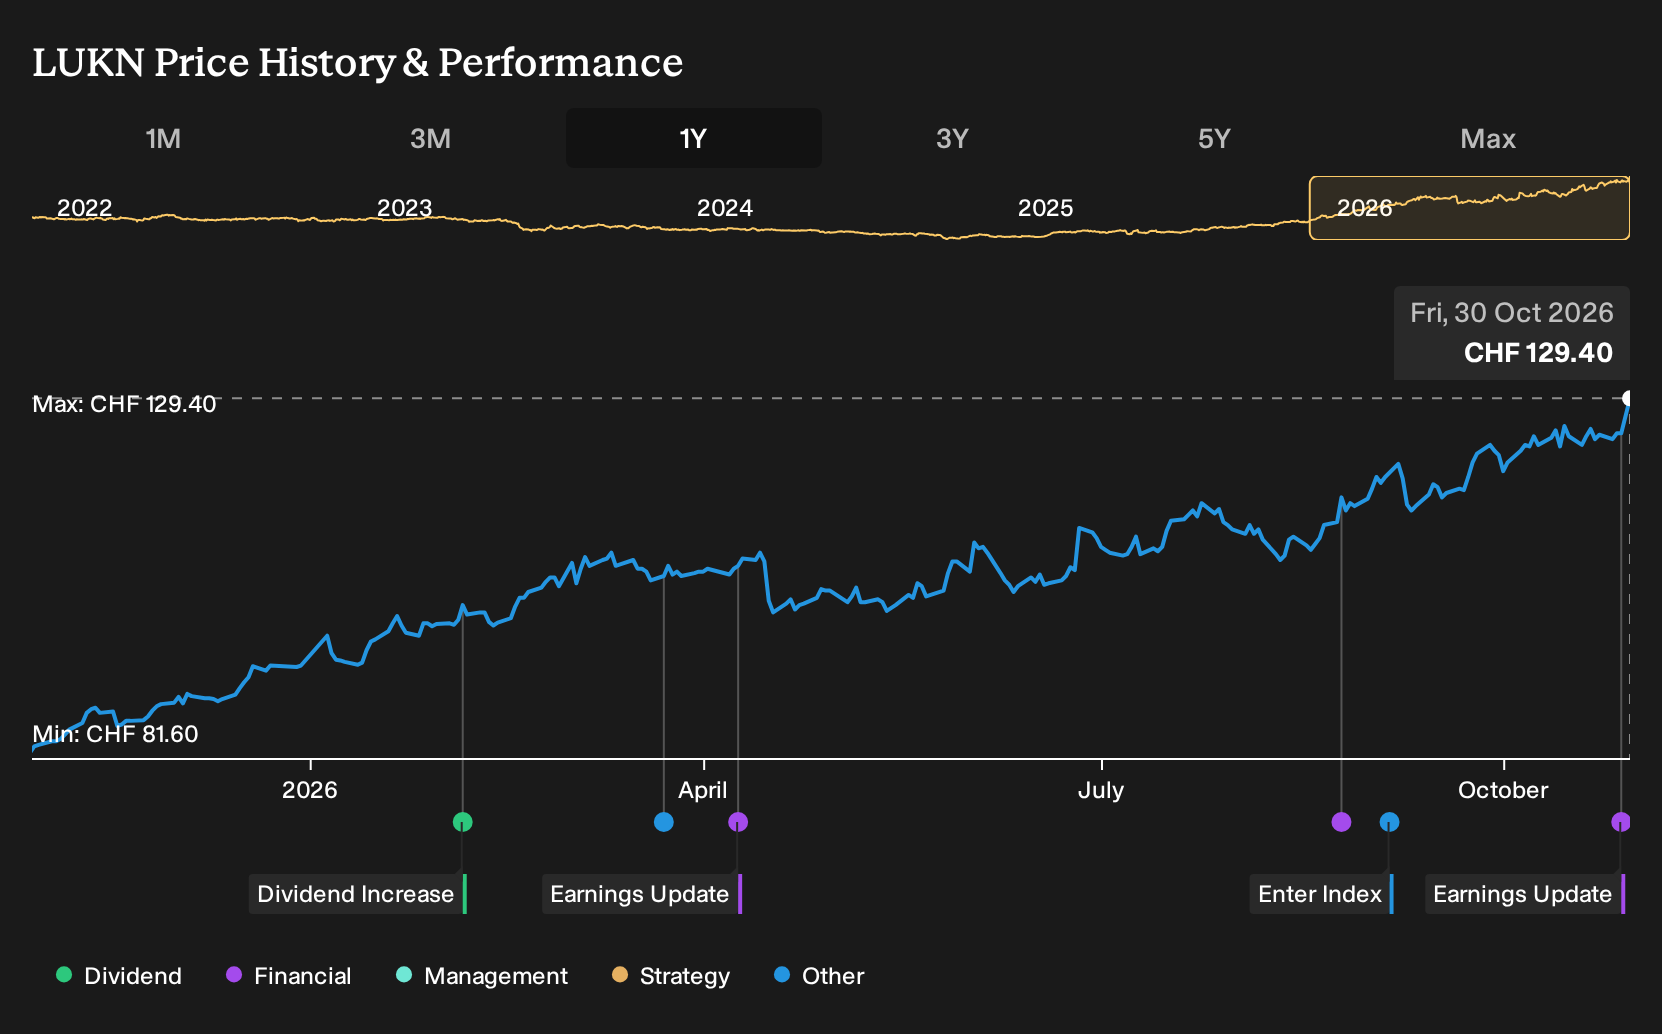
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly CHF 118 to CHF 145, so private investors already bracket Luzerner Kantonalbank across a wide valuation band. These views were set before the latest nine month earnings update, so treat them as a jumping off point and compare several contrasting opinions for context.
Explore another Luzerner Kantonalbank fair value estimate, including one that suggests potential upside of as much as 12% from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Luzerner Kantonalbank research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Luzerner Kantonalbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Luzerner Kantonalbank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Luzerner Kantonalbank?
If Luzerner Kantonalbank’s measured profile appeals to you, it can be useful to compare it with other listed businesses that share some of the same strengths but sit in different corners of the market. The Simply Wall St Screener lets you sift through global stocks by balance sheet strength, dividend profile or valuation signals in a few focused steps.
- For investors who care most about capital stability and business durability, start with a curated 218 resilient stocks with low risk scores that score well on resilience and lower perceived risk.
- If steady income is a priority, scan companies in the 221 dividend fortresses that combine higher yields with a focus on ongoing distributions.
- When you want to hunt for underappreciated opportunities, review the 602 high quality undiscovered gems where strong fundamentals have not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com