
Will Mardie Project Progress Change BCI Minerals' (ASX:BCI) Stock Narrative
- BCI Minerals has progressed construction of its Mardie salt and sulfate of potash project toward completion while keeping spend aligned with budget, even as the asset remains pre revenue.
- The company’s high P/E ratio against current earnings has sharpened focus on whether Mardie’s potential future cash generation justifies today’s valuation.
- This article examines how BCI Minerals’ investment narrative is shaped by Mardie’s near term completion progress and the debate around its elevated P/E.
Compare BCI Minerals’ valuation story with other potential opportunities by scanning our hand picked 15 high quality undiscovered gems that may still be flying under most investors’ radar.
BCI Minerals Investment Narrative Recap
To own BCI Minerals, you need to buy into Mardie moving from construction site to functioning salt and sulfate of potash operation. The short term swing factor is execution on the remaining high value packages, including dredging, crystallizer sealing and the salt wash plant, without heavy budget creep in an inflationary build environment.
The biggest near term risk is that any construction delay or pond underperformance slows first tonnes and drags out the move from pre revenue to cash generation. If global salt or SOP pricing softens by the time production ramps, that would further test whether the current high P/E still feels sensible.
One of the most relevant recent disclosures is management’s progress update on Mardie, which highlighted around 93% pond inundation, crystallizer sealing underway and marine works also around 93% complete. For you as a shareholder, that update sets expectations on how close BCI Minerals really is to first salt on ship in late 2026.
That same progress report also flagged dependence on the digital twin, pond density control and crystallizer performance to hit early volume targets. Any slippage there, or a more expensive SOP byproduct plant than the A$150m to A$200m range previously discussed, would weaken the multi pillar earnings story that many investors are currently paying up for.
BCI Minerals' outlook indicates projected revenue of A$357.8 million and earnings of A$50.0 million by 2029. This is based on an assumed annual revenue growth rate of 354.1% and an estimated earnings change of about A$123.3 million, shifting from a current loss of A$73.3 million to the forecast profit.
Discover how BCI Minerals' fair value indicates a 19% potential upside to its current price, which could close sooner than many investors expect.
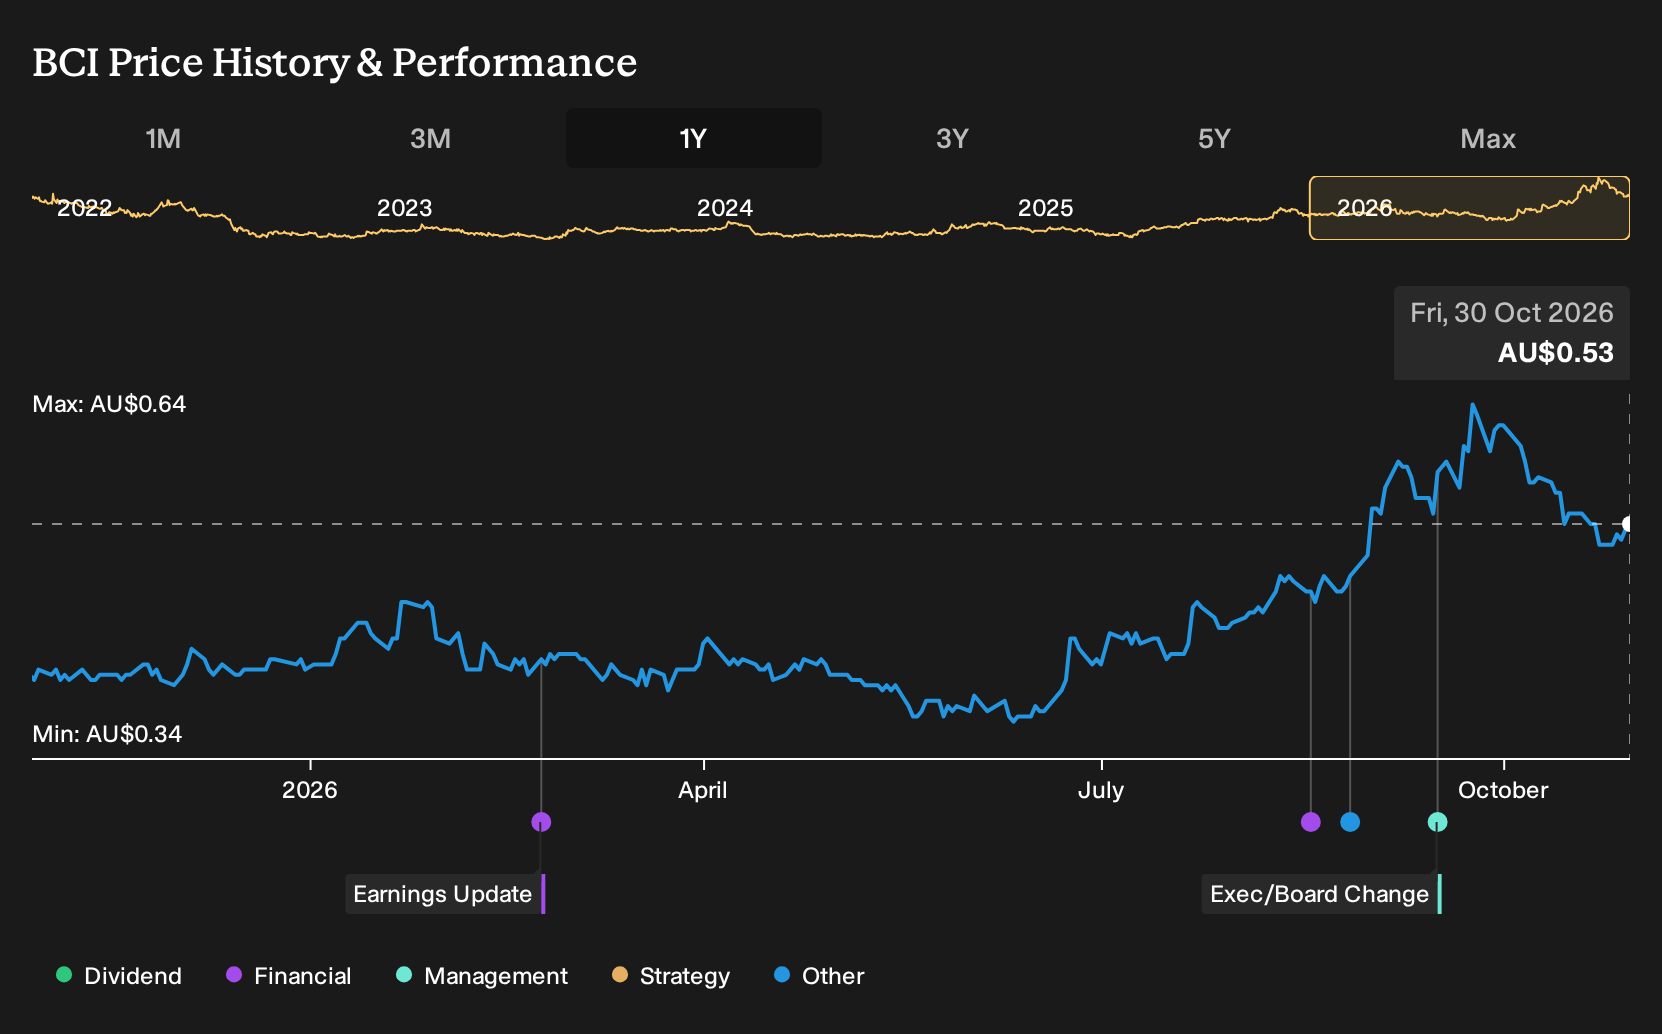
Exploring Other Perspectives
BCI Minerals looks very different through the most pessimistic lens. Instead of focusing on long term salt demand, the lowest analysts worry about weather and ramp up risk, and the A$333 million still to be spent. Before this news, that group was only pencilling in around A$388.2 million of 2029 revenue and A$101.3 million of earnings. These views may shift, so treat them as one set of assumptions among many and weigh them against your own expectations.
Explore 2 other BCI Minerals fair value estimates, including one that suggests it could be worth just A$0.625.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BCI Minerals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BCI Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate BCI Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond BCI Minerals?
If the BCI Minerals story has sharpened your thinking on risk, timing and valuation, it can help to set it alongside a wider watchlist. The Simply Wall St Screener lets you scan for other shares that match the kind of balance sheet strength, income profile or upside potential you are looking for.
- If resilience matters most to you, start with companies that screen well on stability and risk using the 6 resilient stocks with low risk scores available in the tool.
- For investors who prioritise income, use the screener to zero in on reliable payers and work through the 4 dividend fortresses that fit your yield criteria.
- If you want to widen the search to strong operators that are not widely followed, sort through the 15 high quality undiscovered gems and see which profiles line up with your own checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com