
Is Toro (TTC) Still Cheap As OneFleet And A New CTO Lift Its Story?
Toro (TTC) just paired a new chief technology officer with a fresh customer program, OneFleet, tying leadership changes and multibrand savings into a single, technology focused story for investors.
Recent trading has been moving Toro in the same direction as its latest announcements, with the share price at $107.96 and a 30-day share price return of 11.97% contributing to a 34.66% year-to-date share price gain. The 1-year total shareholder return of 47.03% suggests that this momentum has been sustained rather than fleeting.
Scan Toro alongside other equipment and industrial players showing renewed interest from the market with our hand picked 18 high quality undiscovered gems.
Toro now trades near its recent highs, yet still sits below both analyst targets and one intrinsic value estimate. Is that a reasonable cushion for caution, or a sign the market is underrating this move?
Most Popular Narrative: 2.7% Undervalued
Toro’s most followed narrative pegs fair value at $111, just above the recent $107.96 close. This frames the current rally as still having a modest valuation gap to close if that thesis holds.
Secular growth in underground and specialty construction equipment tied to fiber, power, water and data connectivity needs, evidenced by low double digit organic growth in Q2 FY2026 and additional growth in Q3 FY2026, along with products such as HammerHead Bluelight pipe relining growing over 30% year to date and Tornado adding more than 2 percentage points to overall company sales growth, positions Toro to expand revenue and contribute positively to overall margins as this mix grows within the portfolio.
See why 9 investors see Toro as 3% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, Toro’s story can break if AMP savings fade or golf and underground demand disappoint, which could leave those analyst margin and P/E assumptions looking stretched.
Find out about the key risks to this Toro narrative.
Another View: Toro On Earnings Multiples
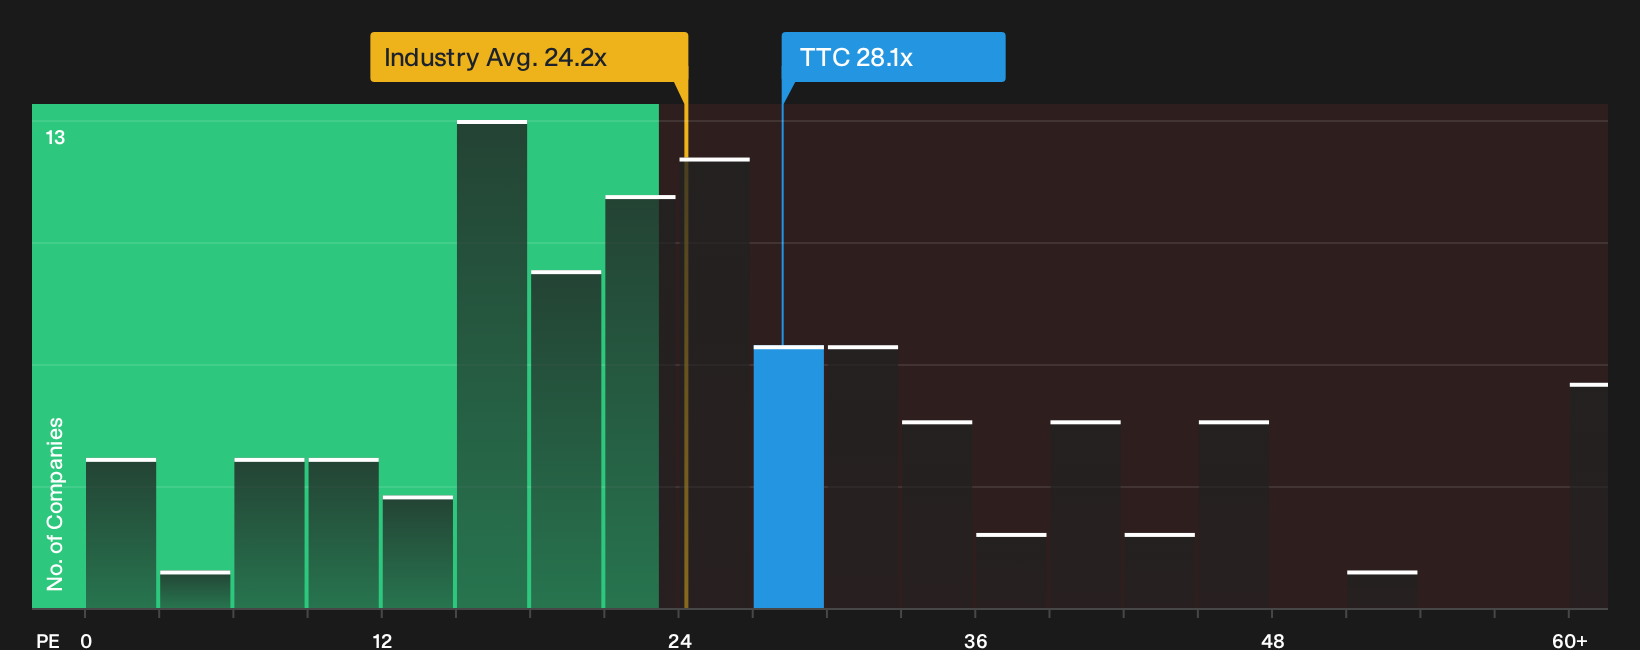
The story shifts once the focus moves from fair value estimates to what the market is paying for Toro today. The stock trades on a P/E of 28.1x, slightly above peers at 27.9x and well above its own fair ratio of 21.7x. This points to less room for disappointment if growth underdelivers.
That gap suggests investors are already paying a premium for the story. Any slip in AMP execution or demand in golf and underground equipment could hit sentiment faster than the fundamentals change. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Toro’s valuation story can be helpful, not confusing, if you move quickly and test the data against your own thesis using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Toro?
If Toro has sharpened your focus, do not stop there. Broader opportunity often sits just outside your current watchlist, and skipping that view can limit your options.
- Zero in on quality at a discount by checking companies screened as 29 high quality undervalued stocks that might suit a value driven watchlist.
- Prioritize resilience and sleep better at night by reviewing a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier histories.
- Get ahead of the crowd by scanning a 9 elite penny stocks with strong financials that highlights smaller, higher risk ideas with stronger fundamentals than many peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com