
Deere (DE) Cyberattack Spotlight Keeps Valuation Questions In Play
Cyberattack spotlight puts Deere’s risk and valuation in focus
Recent AI powered cyberattacks involving Deere (DE) have pushed cybersecurity and resilience to the foreground, as investors weigh incident related risks against the current valuation and the farm equipment group’s broader demand trends.
Recent trading suggests investors are still rewarding Deere for execution despite the cyber headlines, with a 90 day share price return of 13.97% and a year to date share price gain of 44.70%, feeding into a 1 year total shareholder return of 47.99% and a 5 year total shareholder return of 102.97%.
Scan beyond Deere and the cyber headlines by reviewing a hand picked set of machinery and industrial players with resilient balance sheets in the list of solid balance sheet and fundamentals (25 results).
Deere has a long running, diversified equipment franchise and a stock that has climbed sharply this year. After that kind of move, is this still a strong business at a fair price, or is it simply a strong business at a full one?
Most Popular Narrative: 2% Undervalued
On the most followed view, Deere’s fair value of $688.44 sits just above the last close at $675.48. This puts the current cyber headlines against a valuation that already incorporates many expectations.
Expansion of Deere’s digital ecosystem, with more than 520 million engaged acres, nearly 1.2 million connected machines and over 450,000 monthly active users in John Deere Operations Center, builds on the prior focus on software and data services and points to a growing base for recurring revenue and potentially higher earnings from digital tools layered on the installed equipment fleet.
See why 125 investors see Deere as 2% undervalued.
Result: Fair Value of $688.44 (UNDERVALUED)
Still, the Deere narrative can crack if tariff costs around US$1.1b persist as a margin drag, or if large agriculture demand in key regions stays weak.
Find out about the key risks to this Deere narrative.
Another View: Deere’s P/E sends a different message
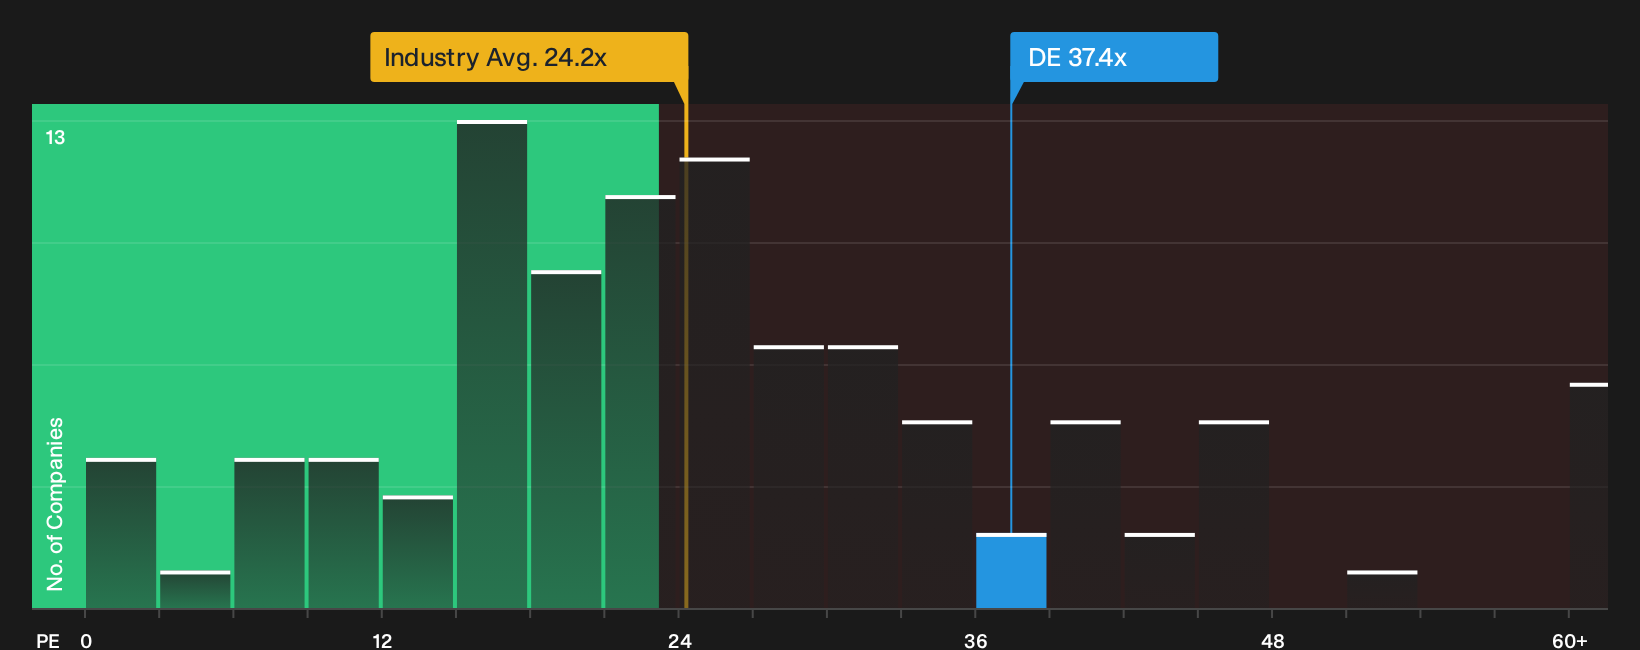
The SWS DCF model flags Deere as undervalued, with the $675.48 share price trading below an estimated $777.08 future cash flow value. The P/E picture is very different. Deere trades at 37.4x earnings versus 24.2x for the US Machinery industry and 33.4x for peers.
Set against an estimated fair ratio of 37.6x, that premium looks thin on paper. However, the gap to sector and peer multiples still raises a simple question for investors: Is this a sensible quality mark up or a valuation that leaves little room for error in the Deere story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Deere story points in opposite directions, so do not wait to poke through the numbers and pressure test the narrative for yourself. To balance the potential upsides with the issues investors are worried about, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Deere?
Do not park everything in Deere. Use fresh screens to uncover other opportunities that fit different goals, risk levels, and income needs.
- Target resilient cash generators and let the numbers guide you through a curated 29 high quality undervalued stocks list that focuses on quality alongside pricing.
- Lock in potential income streams by scanning companies with strong payout profiles through a focused 5 dividend fortresses list built for yield hunters.
- Prioritise capital protection by filtering for sturdier businesses using a carefully constructed 30 resilient stocks with low risk scores set that keeps downside firmly in view.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com