
UL Solutions (ULS) Lifts 2026 Capex After Strong Quarter But Is The Valuation Priced In
UL Solutions (ULS) just put more money to work than investors expected. Management lifted 2026 capital spending and highlighted slower margin improvement driven by higher incentives and acquisition costs, and the stock slipped despite a strong quarter.
The near term story around UL Solutions reflects that tension between growth ambition and higher spending. The share price is up 13.93% over the past month but down 18.42% over 90 days, and the 1 year total shareholder return is also slightly negative. This suggests recent momentum is rebuilding after a weaker stretch, as investors weigh heavier capital expenditure, facility expansions and new service launches against concerns about a slower pace of margin improvement.
Scan beyond UL Solutions and compare this capital spending story with other testing and infrastructure driven plays using our curated list of 54 AI infrastructure stocks.
Bulls see UL Solutions spending to deepen its testing and software moat. Bears see capex and moderated margin progress biting into returns. Which story does the current valuation actually echo?
Most Popular Narrative: 24% Undervalued
UL Solutions closed at $74.76 while the most followed narrative pegs fair value closer to $98. That gap puts real weight on whether recent spending and forecast earnings can support a higher long term valuation.
Planned expansions in testing facilities in Plano, Texas and Carugate, Italy could lead to increased capital expenditures, impacting free cash flow. However, these expansions are expected to address demand for sustainable HVAC systems, potentially supporting future revenue growth.
See why 5 investors see UL Solutions as 24% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, global macro uncertainty and higher effective tax rates could squeeze earnings, especially if customers delay product launches or pull back on testing budgets.
Find out about the key risks to this UL Solutions narrative.
Another View: UL Solutions Looks Expensive On Earnings
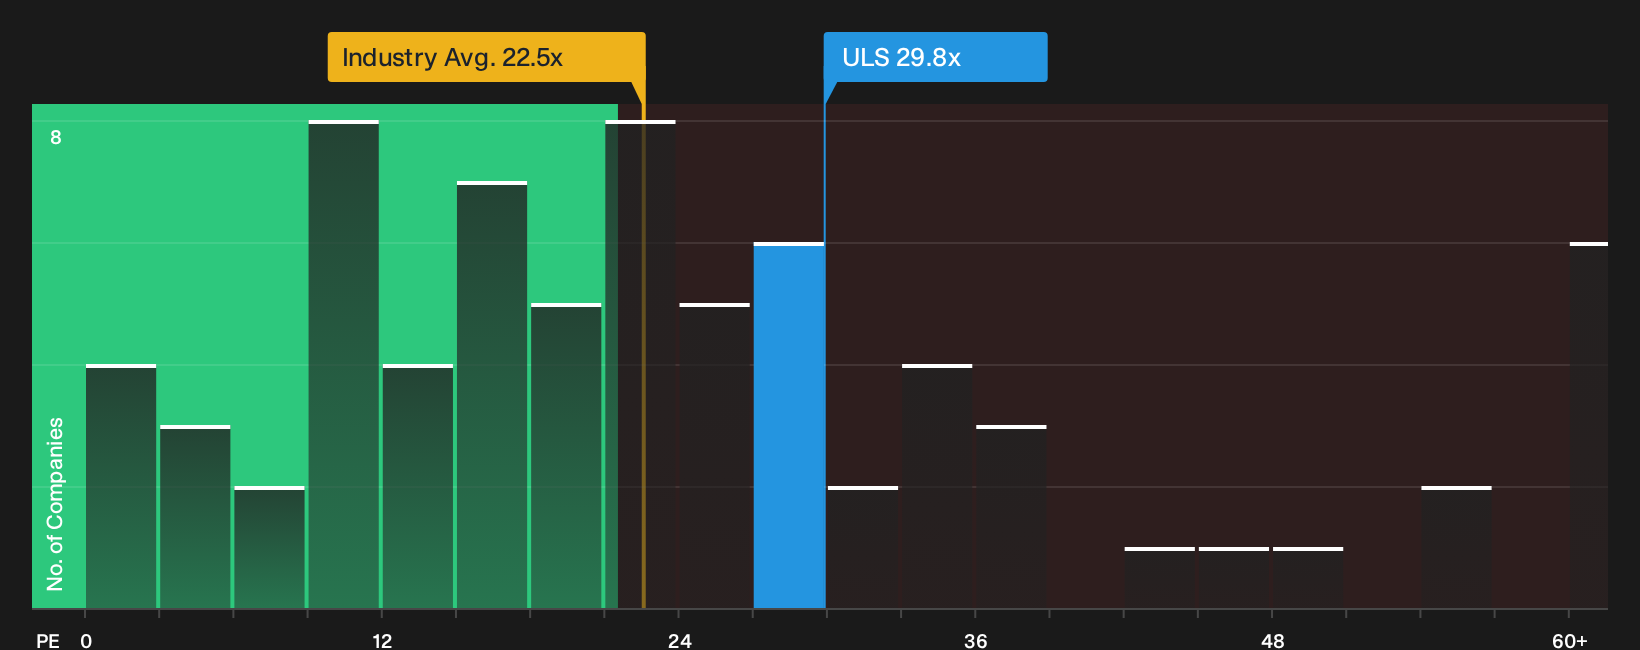
On a simple earnings yardstick, UL Solutions screens as pricey. The stock trades on a P/E of 29.8x, compared with 22.3x for the US Professional Services group and a fair ratio of 16.2x that our work suggests the market could eventually lean toward. That sort of gap often matters most when sentiment cools rather than when it is running hot, so how comfortable are you paying above both peers and that fair ratio today?
For a closer look at what the earnings multiple implies for valuation risk, see See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on UL Solutions can pull you in both directions, so move quickly to inspect the full picture yourself and decide where you land. To balance the potential upside against the issues that investors are watching closely, start by weighing 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions interests you, do not stop there. Fresh ideas often sit just outside your current watchlist, and ignoring them can quietly cap your upside.
- Target stronger value opportunities by scanning 29 high quality undervalued stocks that combine quality fundamentals with more modest market expectations.
- Protect your downside by reviewing 30 resilient stocks with low risk scores that pair resilient balance sheets with lower overall risk scores.
- Spot tomorrow's potential leaders early by searching through 18 high quality undiscovered gems that the wider market may not be focusing on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com