
Celsius Holdings (CELH) Stock Climbed, But What Is Drawing Fresh Attention?
Pomerantz LLP’s newly filed class action against Celsius Holdings (CELH), tied to alleged misstatements about Alani Nu energy drink safety and youth marketing, has pushed the stock and its legal exposure into sharper investor focus.
The short term tape has firmed, with a 1-day share price return of 3.41% and a 30-day share price gain of 6.47%, yet Celsius Holdings still carries a year to date share price decline of 39.02% and a 1-year total shareholder return loss of 51.65%. This hints that recent strength is more about a rebound in sentiment than a full reset of longer term concerns around earnings expectations and the fresh legal overhang.
Scan handpicked consumer and beverage peers facing similar earnings and legal scrutiny by reviewing the 30 resilient stocks with low risk scores that still clear stricter balance sheet and risk hurdles.After a sharp one day bounce and a modest 30 day climb, Celsius Holdings still trades well below recent highs. Is the real upside still ahead, or did this rebound already capture most of it for now?
Most Popular Narrative: 39% Undervalued
Against a last close of $29.12, the most followed narrative on Celsius Holdings pegs fair value closer to the high $40s, which frames recent volatility as a valuation gap rather than a spent trade.
I believe Celsius Holdings stock can reach a price of $47.00 per share (+42%) over the next two months, with potential to reach $71.00 per share within the next few years. This will be driven by continued earnings and revenue gains, international expansion, and the long-term integration of Alani Nu and Rockstar, which were both recent acquisitions.
See why 11 investors see Celsius Holdings as 39% undervalued.
Result: Fair Value of $47.37 (UNDERVALUED)
Still, the Celsius Holdings bull case leans heavily on continued Pepsi distribution momentum and on smooth Alani Nu integration, both of which could unravel if legal challenges escalate.
Find out about the key risks to this Celsius Holdings narrative.
Another View On Celsius Holdings: Rich Multiples Against Peers
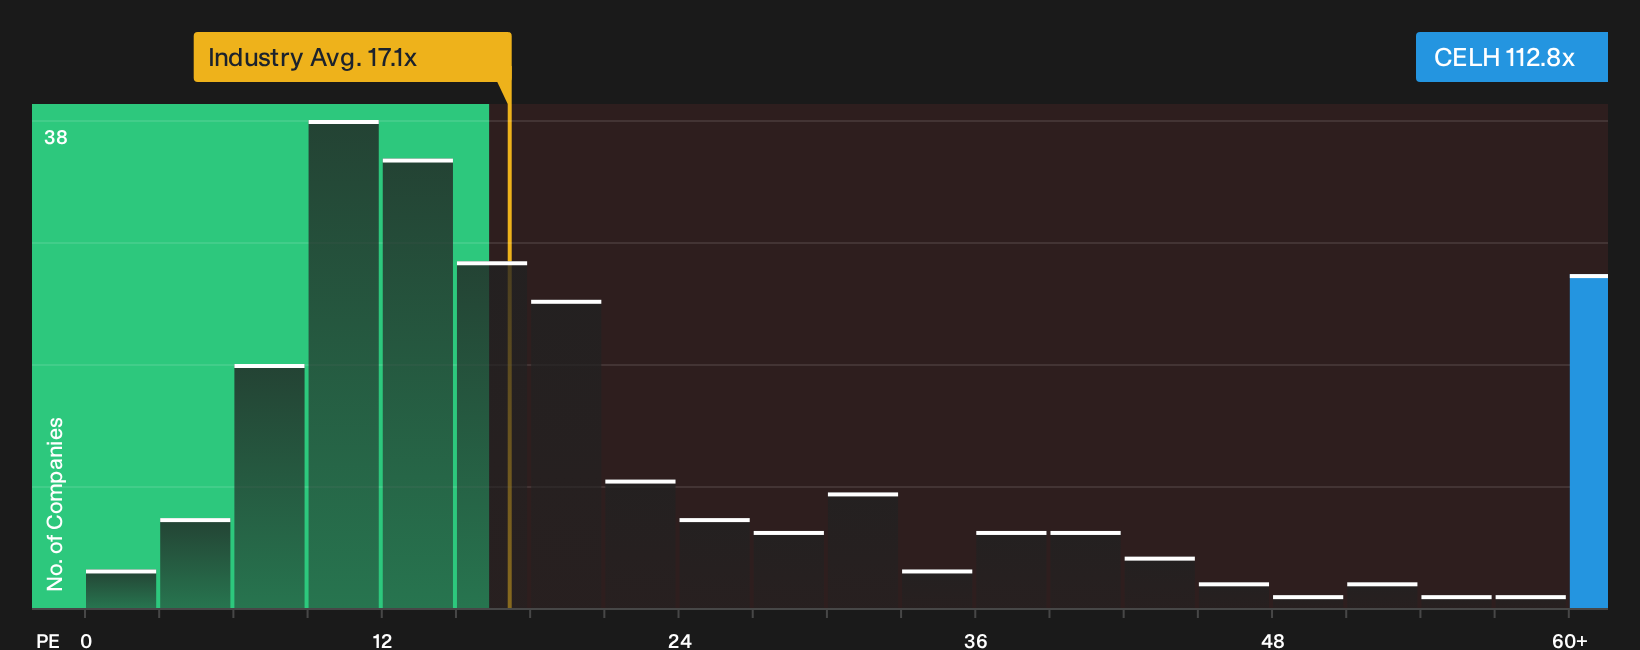
DCF and narrative fair values both paint Celsius Holdings as undervalued, yet the market is already charging a P/E of 112.8x for the shares. That compares with 34x for peers, 17.1x for the wider beverage group, and a fair ratio of 28.8x. For investors, is that gap a margin of safety or a valuation hazard?
Our valuation work takes that richer P/E head on. It focuses on what would need to change in earnings or sentiment for Celsius Holdings to trade closer to its fair ratio and peer range, rather than far above them.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Celsius Holdings story so far. Use the full data set, including 2 key rewards and 2 important warning signs, to pressure test the bull and bear cases yourself.
Looking for more investment ideas beyond Celsius Holdings?
If this Celsius Holdings review sharpened your thinking, now is the moment to widen your opportunity set and stress test your portfolio against stronger contenders.
- Target resilient returns by scanning a 5 dividend fortresses that can help you focus on income ideas with yields that stand out from cash in the bank.
- Hunt for mispriced opportunities using the 18 high quality undiscovered gems that highlight companies with solid fundamentals yet limited market attention.
- Prioritise capital preservation by reviewing a list of solid balance sheet and fundamentals (25 results) so you are not relying on stories that crack when conditions tighten.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com