
AI Go Launch Could Be A Big Test For Procore Stock (PCOR)
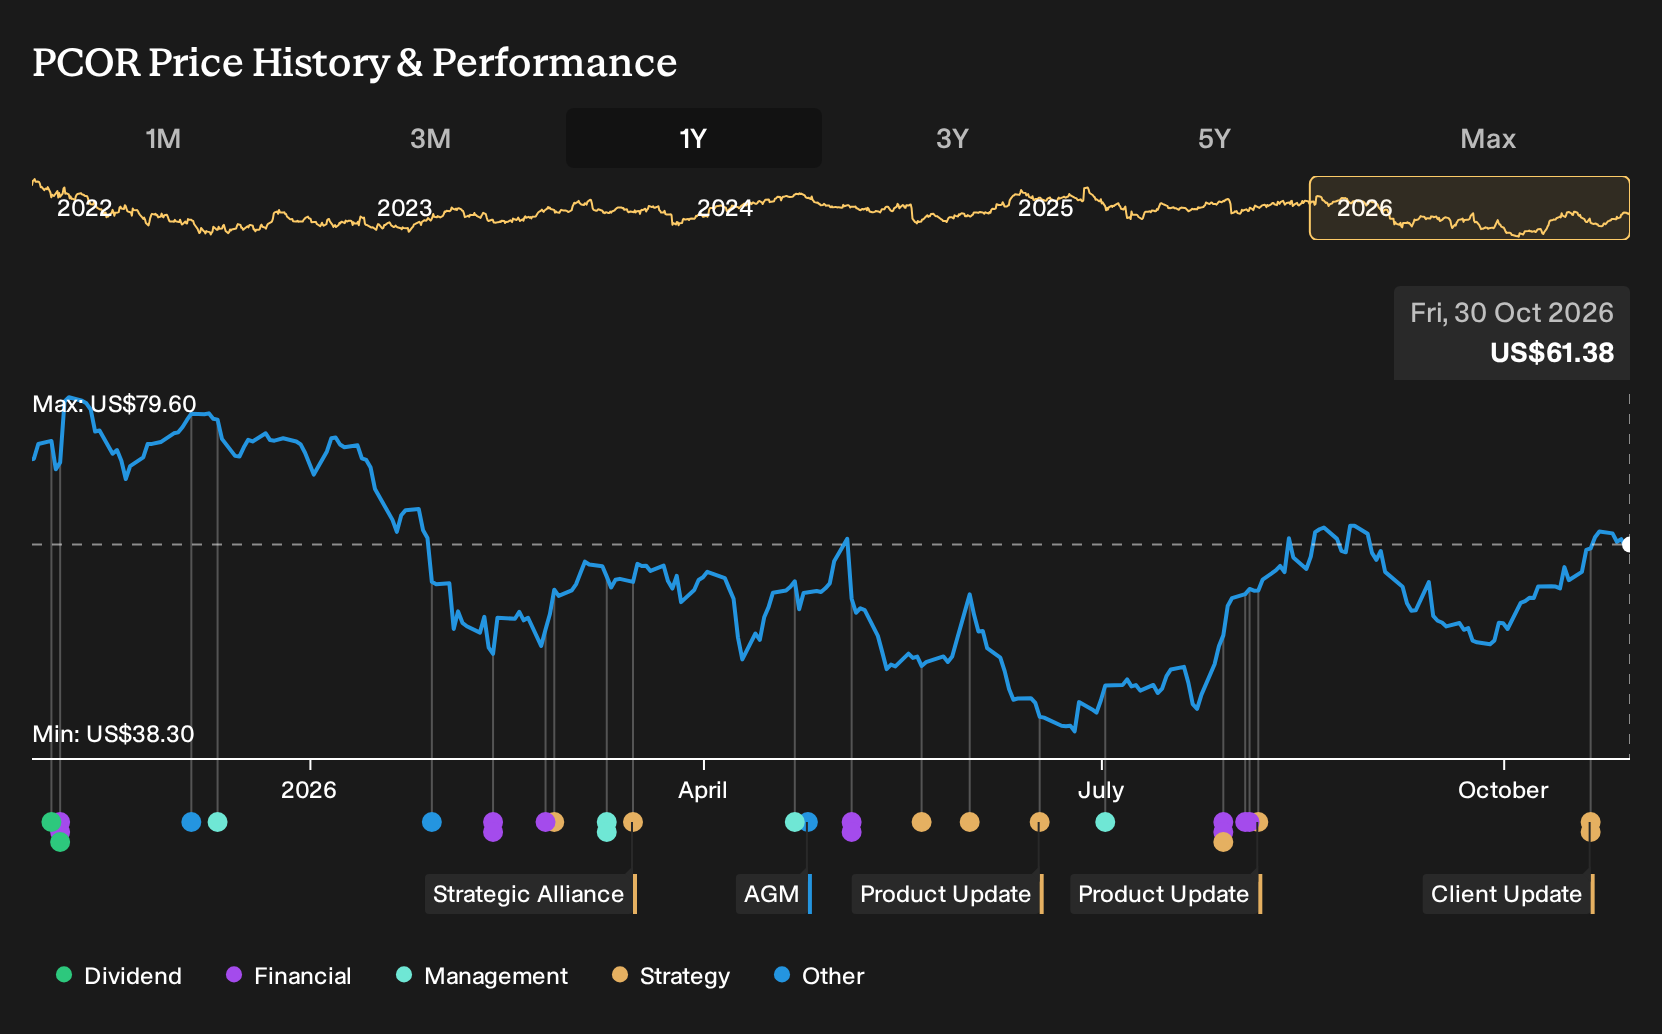
- Procore Technologies reported two major updates in October 2026, linking its construction platform with IBM Maximo for asset lifecycle data and launching Procore AI Go, a voice-led app with a Meta AI glasses beta for hands-free access to project information.
- The pairing of Procore’s asset data capture with IBM’s enterprise maintenance software, alongside AI-powered field tools, points to tighter integration between construction workflows and long term asset operations. This directly affects how owners, contractors, and facility teams may weigh software spend against productivity and lifecycle costs.
- Next, the focus shifts to how Procore Technologies’ broader investment narrative could be influenced by the AI Go rollout and IBM asset integration.
Scan how Procore Technologies’ AI tools and data partnerships fit into a wider construction tech shift, then size up other potential beneficiaries with the 54 AI infrastructure stocks.
Procore Technologies Investment Narrative Recap
To own Procore Technologies, you need to believe its construction platform can keep deepening into daily workflows for owners, contractors, and now operations teams, even as revenue growth expectations sit in the low to mid teens. The IBM Maximo tie up and AI Go launch both point toward richer use cases that could help support that broader platform role.
The key near term swing factor is whether these products translate into healthier annual recurring revenue without forcing a big jump in sales and marketing spend. The main risk is that growth continues to slow while costs stay high, which would keep margins pressured for a business that is only beginning to show operating profitability.
The IBM Maximo collaboration looks most relevant for today’s thesis check. It connects Procore Asset Management data with enterprise asset maintenance software, giving owners and facility teams a clearer digital thread from build to operations. For an investor, that moves Procore Technologies further into the owner stakeholder segment that analysts already see as an important growth vector.
Operationally, this link could support higher average revenue per owner customer over time if those users standardize on Procore for both construction and asset data. The flip side is execution risk. Integrations of this depth can be complex, and if adoption is slower than hoped, the spend on AI and product development might run ahead of the revenue impact that investors are watching for.
What The Current Forecasts Assume For Procore Technologies
Analysts sketch a fairly specific financial path for Procore Technologies. Consensus models point to revenue expanding by 15.1% a year over the next three years, with the business moving from a loss of $38.9 million in earnings today to a projected $313.1 million by 2029. That shift implies an earnings swing of roughly $352 million over the forecast window, with the same reports tying those profits to about $2.2b in revenue in 2029.
Procore Technologies' narrative projects $2.2b revenue and $313.1 million earnings by 2029. This implies 15.1% yearly revenue growth and an earnings increase of roughly $352 million from a loss of $38.9 million today.
Uncover why Procore Technologies' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Procore Technologies leans hard into AI adoption risk. The most cautious analysts were only penciling in 12.6% annual revenue growth and about US$158.5 million in earnings by 2029 before this news. That is far below the consensus path. Use this IBM and AI Go update as a prompt to compare those narratives yourself.
Explore 4 other Procore Technologies fair value estimates, including one that suggests as much as 55% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Procore Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Procore Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procore Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Procore Technologies?
If the Procore Technologies story has you thinking about how AI, balance sheet strength, and cash generation show up in other stocks, it can help to cast the net wider with a few focused screens on Simply Wall St.
- If you prefer resilient businesses where financial risk looks contained and balance sheets are built to absorb shocks, then check out the 30 resilient stocks with low risk scores.
- If you are interested in companies that pair financial strength with cleaner fundamentals and less leveraged capital structures, start with this list of solid balance sheet and fundamentals (25 results).
- If you are hunting for under followed opportunities that already have robust metrics but less attention from the crowd, you may want to scan the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com