
Bitmine Immersion Technologies (BMNR) Sells Off As Growth Hopes Clash With A Pricey Valuation
Bitmine Immersion Technologies (BMNR) has drawn fresh attention after recent trading left the share price at US$20.18, with short term returns under pressure even as the past 3 months show a positive move.
Recent trading has been rough for Bitmine Immersion Technologies, with the share price sliding 6.83% in a single session and leaving the 7‑day and 30‑day share price returns down 9.91% and 23.65% respectively. However, the 90‑day share price return is still up 16.78%, and the 3‑year total shareholder return sits at 57.73% against a much weaker 1‑year total shareholder return of a 56.73% decline.
Scan how Bitmine Immersion Technologies compares with other blockchain related plays by reviewing our hand picked list of 18 cryptocurrency and blockchain stocks in one place.
Bitmine Immersion Technologies has reported rapid growth in revenue and net income alongside a sharp pullback in the share price. The business story looks bold. The real test is whether the current valuation still justifies a closer look.
Preferred Price-to-Book of 1x for Bitmine Immersion Technologies: Is it justified?
On a simple yardstick, Bitmine Immersion Technologies trades on a P/B ratio of roughly 1x, which sits well below both its US Software industry average of 2.6x and a peer group average of 4.8x. With the share price at $20.18, the market is assigning a comparatively modest value to the equity base.
P/B compares a company’s market value to its net assets, so it can be a blunt but helpful tool when earnings are negative or volatile. For Bitmine Immersion Technologies, which is currently loss making and focused on blockchain infrastructure and services rather than mature, cash generative software licenses, that kind of balance-sheet-anchored lens becomes more prominent for many investors.
The headline takeaway is stark. A P/B of 1x when peers sit at 2.6x and 4.8x signals the market is pricing in heavier business risk, profitability concerns, or balance sheet strain relative to those groups. The firm is unprofitable, reports a return on equity that is currently deeply negative, has less than one year of cash runway, and relies on higher risk funding sources rather than customer deposits. Shareholders have also taken on substantial dilution over the past year, which can weigh on how much investors are prepared to pay for each dollar of book value.
The same data that flag value also point to why the discount exists. Losses have been widening at a very rapid rate over five years, management and the board are both new with short tenures, the share price has been volatile, and recent one year returns lag both the wider US market and the broader Software sector. On the other side of the ledger, forecasts currently point to very strong revenue expansion of about 95.2% per year and earnings growth of roughly 103.25% per year, with expectations that Bitmine Immersion Technologies becomes profitable within three years and grows faster than the wider US market.
In short, the low P/B ratio pits a heavy risk profile and thin cash runway against aggressive growth projections and analyst expectations that losses eventually flip to profit. Whether that discount to peer P/B levels is justified depends on how much confidence you place in the revenue and earnings forecasts compared to the financial pressure and dilution already visible in the recent record.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 1x (ABOUT RIGHT)
Still, the rapid net loss, along with a short cash runway and heavy shareholder dilution, could quickly challenge the bullish Bitmine Immersion Technologies narrative if funding conditions tighten.
Find out about the key risks to this Bitmine Immersion Technologies narrative.
Another View on Bitmine Immersion Technologies
The low 1x P/B ratio presents Bitmine Immersion Technologies as inexpensive on an asset-value basis, yet the SWS DCF model points in the opposite direction. From a cash flow perspective, the shares at $20.18 trade well above an estimated future cash flow value of about $0.01, which indicates a high price if those projections hold up.
This contrast between a modest balance sheet multiple and a very stretched DCF result raises a practical question: Is the current valuation more about confidence in future growth than about the cash the business is expected to generate?
Look into how the SWS DCF model arrives at its fair value.
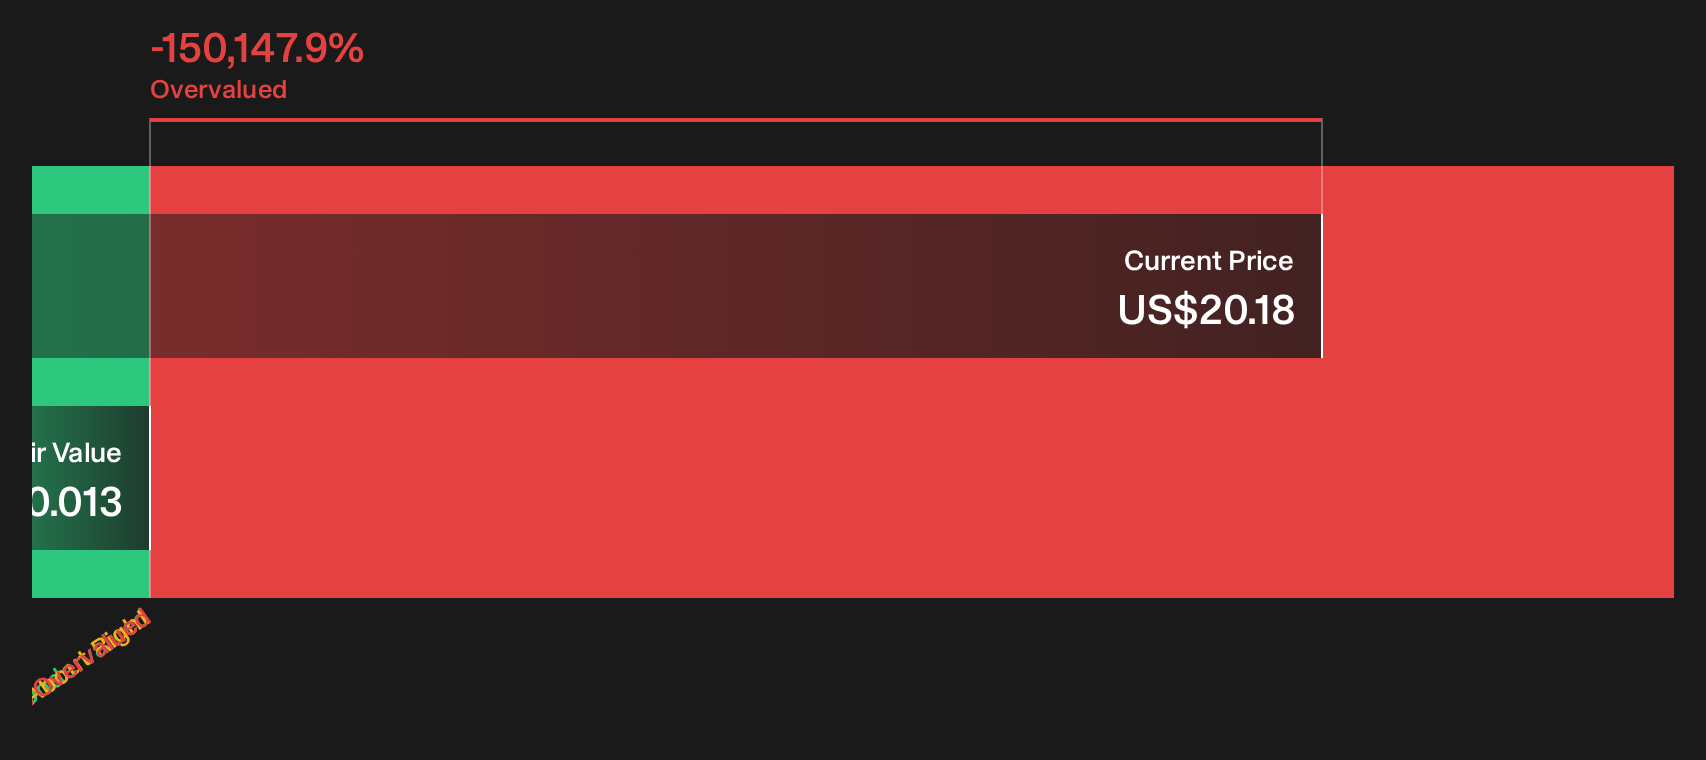
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bitmine Immersion Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the market is too harsh or not harsh enough on Bitmine Immersion Technologies right now? Take a moment to review the underlying figures, weigh both the threat side and the upside potential, and then anchor your own view with the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Bitmine Immersion Technologies?
If Bitmine Immersion Technologies has you thinking harder about risk, reward, and valuation, do not stop here. Use the time spent today to scan fresh ideas that might fit your goals even better.
- Target higher potential upside in smaller companies by reviewing the 9 elite penny stocks with strong financials that clear stricter financial quality filters.
- Hunt for mispriced opportunities by checking the 29 high quality undervalued stocks where strong fundamentals line up with compressed market expectations.
- Prioritise resilience first by running through the 30 resilient stocks with low risk scores and focus on businesses flagged for sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com