
Ollie's Bargain Outlet Holdings (OLLI) Could Be 9% Undervalued On Tariff Refund Fueled Earnings
Ollie's Bargain Outlet Holdings (OLLI) is back on watch after a recent share move that left returns mixed, with the stock up about 5% over the past month yet down roughly 19% year to date.
That recent bounce comes after a tougher stretch for Ollie's Bargain Outlet Holdings, with the share price still down about 19% year to date and the 1 year total shareholder return declining roughly 25%. In contrast, the 3 and 5 year total shareholder returns of about 13% and 24% hint at steadier longer run momentum.
Scan beyond Ollie's Bargain Outlet Holdings and evaluate other retailers showing mixed momentum profiles with the hand picked 18 high quality undiscovered gems.
Ollie's Bargain Outlet Holdings looks like a solid closeout retailer on the surface, and that recent rebound only sharpens the real puzzle. Are investors paying a fair price for this business today, or stretching it?
Most Popular Narrative: 8.6% Undervalued
On the most followed view, Ollie's Bargain Outlet Holdings trades below an estimated fair value of $98.78, with the last close at $90.26, which puts the focus on how that gap is justified by the recent earnings story.
Ollie's reported its second quarter of fiscal 2027 on September 2, 2026, posting comparable store sales of -1.8% against what management called "one of the toughest comparisons we've had as a company." The headline earnings beat, adjusted EPS of $1.42, up 43%, was substantially powered by IEEPA tariff refunds that added 380 basis points to gross margin, a nonrecurring item that management both celebrated and immediately began caveating.
See why 2 investors see Ollie's Bargain Outlet Holdings as 9% undervalued.
Result: Fair Value of $98.78 (UNDERVALUED)
Still, the Ollie's Bargain Outlet Holdings story leans heavily on tariff refunds and elevated price investment, so any weaker comps or softer customer response could quickly pressure that undervaluation case.
Find out about the key risks to this Ollie's Bargain Outlet Holdings narrative.
Another View: Ollie's Bargain Outlet Through The P/E Lens
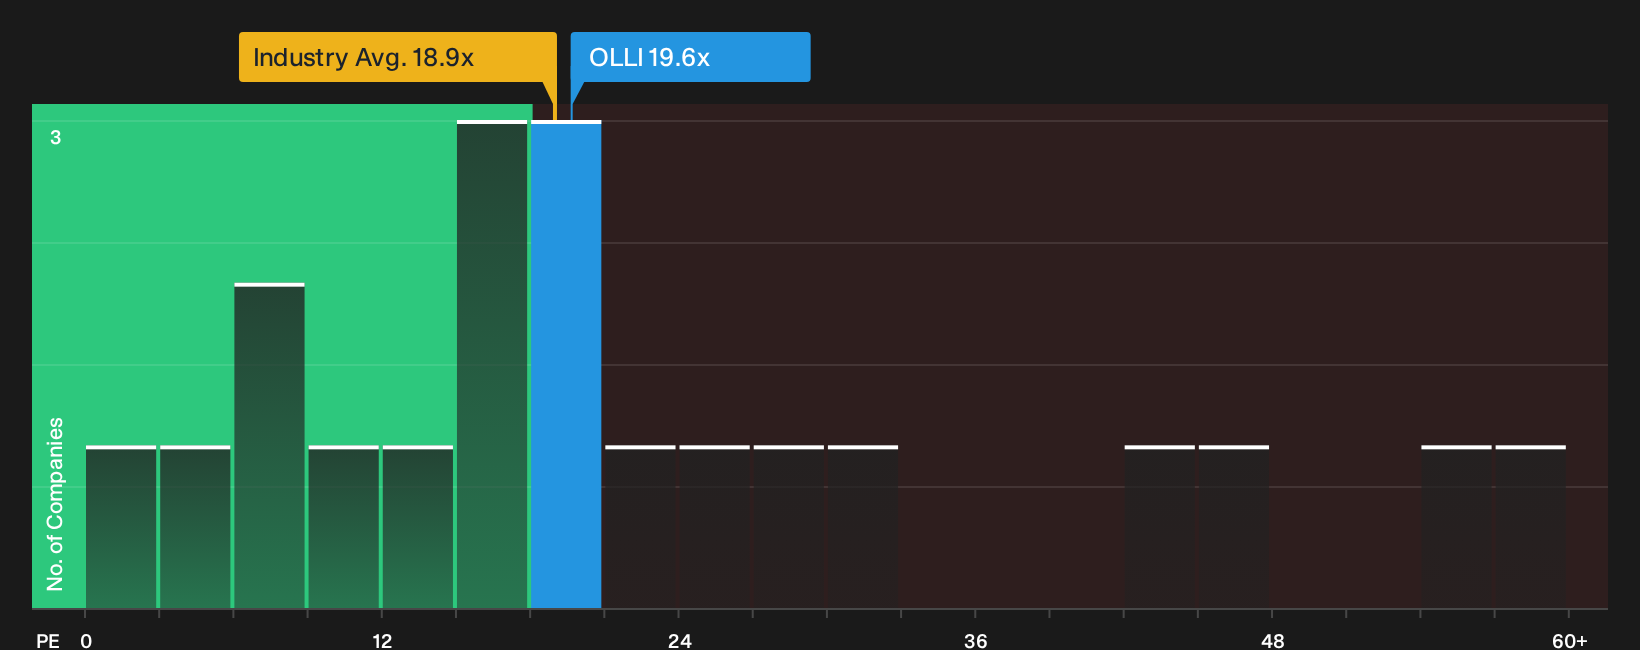
A second look at Ollie's Bargain Outlet Holdings focuses on the earnings multiple instead of fair value models. The stock trades at a P/E of 19.6x compared with a fair ratio of 13.5x, the Global Multiline Retail group at 19.4x, and direct peers also around 19.6x. That cluster of numbers points to limited room for error on the current price, so how comfortable are you paying a premium to the fair ratio when recent comps depend heavily on tariff refunds and pricing moves?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ollie's Bargain Outlet Holdings is split, and the data can point in more than one direction. If you want to pressure test this mixed picture and see what has investors optimistic, walk through the 3 key rewards.
Looking for more Ollie's Bargain Outlet ideas and beyond?
If Ollie's Bargain Outlet Holdings has you rethinking where value and risk really sit, broaden your shortlist with focused stock ideas sourced from the Simply Wall St screener.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio against shocks.
- Hunt for potential mispricings by scanning a 29 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Prioritize capital protection first and growth second by reviewing a 30 resilient stocks with low risk scores designed to highlight companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com