
What Is Drawing Fresh Attention To Ingredion (INGR)?
Fresh analyst commentary around Ingredion (INGR) has focused on expectations for a year-over-year earnings decline, softer revenue, and limited odds of an upside surprise in the upcoming quarterly report.
Recent trading in Ingredion reflects that cautious backdrop. The shares closed at US$96.97 with a 1-day share price return of 1.44% and a modest 7-day gain of 1.33%. However, the year to date share price return is down 11.68% and the 1-year total shareholder return is down 13.23%. By contrast, 3-year and 5-year total shareholder returns of 9.89% and 13.79% point to a much steadier experience for investors who have held the stock through several reporting cycles.
Scan for other ingredient and packaged food stocks under similar pressure by jumping into a curated list of 29 high quality undervalued stocks that may offer a stronger balance of quality and price.
Ingredion trades around US$96.97 while analyst targets and intrinsic value estimates sit higher in a tight band. Is the recent share price weakness enough to close that gap, or is it pointing to a different fair value altogether?
Most Popular Narrative: 10% Overvalued
Ingredion closed at $96.97 while the most followed narrative, using a fair value of $88.23 based on a 7.1% discount rate, points to a modest premium that hinges on how the business mix evolves over time.
The acquisition of Tate & Lyle has the potential to transform Ingredion from a predominantly commodity-oriented starch and sweetener processor into a more global specialty ingredients platform. The primary upside comes from mix shift toward higher-margin functional ingredients, meaningful cross-selling opportunities with global CPG customers, and scale-driven cost synergies. If successfully integrated, the combined business could generate structurally higher margins, stronger free cash flow, and warrant a higher valuation multiple over time.
See why 8 investors see Ingredion as 10% overvalued.
Result: Fair Value of $88.23 (OVERVALUED)
Still, Ingredion’s story can break if the Tate & Lyle integration disappoints or if higher value ingredients fail to offset pressure in legacy starch and sweetener products.
Find out about the key risks to this Ingredion narrative.
Another View: Ingredion’s Earnings Multiple Signals Value
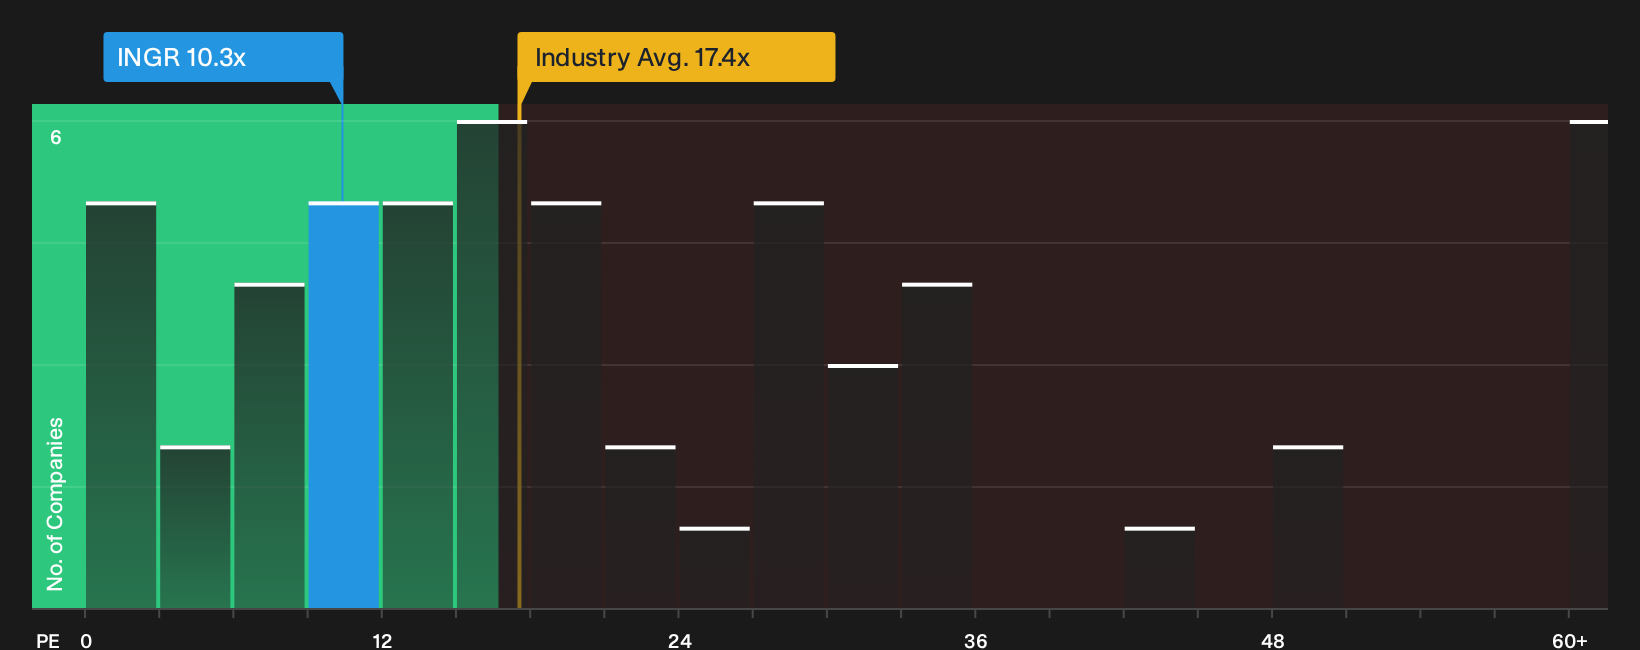
The SWS fair ratio tells a different story for Ingredion. The stock trades on a P/E of 10.3x while peers in the US Food industry average 18.3x and the fair ratio sits at 16.5x. That discount can hint at caution or a potential mispricing. Which side of that gap do you trust more?
See what the numbers say about this price in more detail with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Ingredion do not need to leave you on the fence. Move quickly, review the underlying data for yourself, and then weigh how 5 key rewards fits into your own investment thesis.
Looking for more investment ideas beyond Ingredion?
If Ingredion has your attention, do not stop there. Use the same structured approach to scan other opportunities and keep your portfolio ideas fresh.
- Target dependable cash generators by reviewing a curated 5 dividend fortresses that focuses on income without ignoring balance sheet strength.
- Hunt for quality at a discount through a 18 high quality undiscovered gems that may not yet be heavily followed by the broader market.
- Lean into resilience by filtering for a 30 resilient stocks with low risk scores that aims to pair sturdier financial profiles with measured volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com