
Is Strong Q3 Execution Altering The Investment Case For Corpay Stock (CPAY)?
- Corpay announced that its Cross Border business previously entered a multi year agreement with Newcastle United to serve as the club's Official Foreign Exchange Partner, providing FX risk management solutions and a single access point for global payments.
- The focus on supporting Newcastle United's day to day FX flows highlights how Corpay embeds its platform into operational finance, linking client activity directly to recurring transaction and service fee revenue.
- We will now look at how Corpay’s investment narrative could be influenced by expectations for strong third quarter execution.
Scan how Corpay’s FX partnership fits into the broader payments story by reviewing hand picked 29 high quality undervalued stocks built on recurring transaction flows and solid fundamentals.
Corpay Investment Narrative Recap
To own Corpay, an investor needs to believe the payments mix keeps tilting toward corporate and cross border activity, and that transaction driven fee income stays resilient across cycles. The Newcastle United FX partnership fits that view, but on its own looks modest against a US$5.0b revenue base. The more immediate focus is whether third quarter execution lines up with expectations.
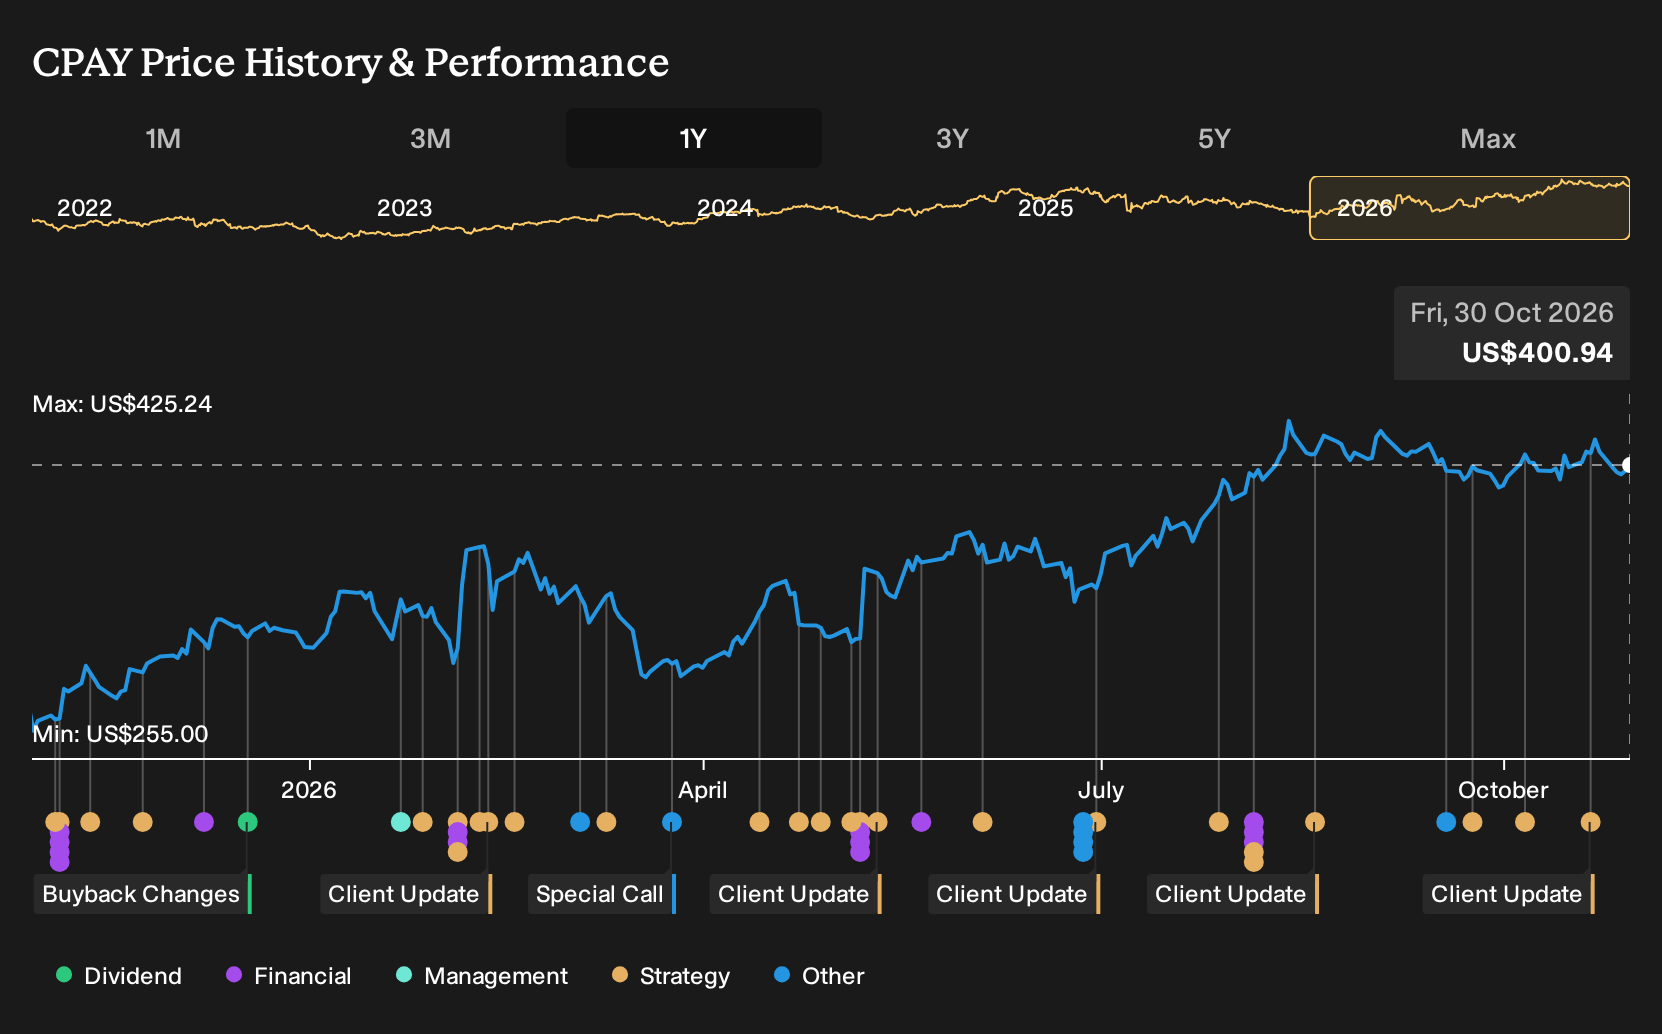
The near term catalyst is the 4 November 2026 earnings release, where revenue and earnings estimates already bake in solid growth across segments. The biggest risk remains pressure on margins and flexibility from legal and regulatory issues around Vehicle Payments pricing and fee practices, alongside Corpay’s reliance on debt funded capital deployment.
The upcoming third quarter report is the announcement that matters most right now. Analysts expect about US$1.36b in quarterly revenue, implying 16.1% year over year growth, and Corpay has exceeded consensus earnings in each of the last four quarters with an average surprise of 3.6%. That backdrop shapes how investors may read the Newcastle United agreement, which reinforces the corporate payments story just ahead of the print.
Corpay holds a Zacks Rank of 3 with an Earnings ESP of +1.07%, which signals a possibility of another beat, while peers like Fiserv and Global Payments face more mixed expectations. If the company meets or exceeds its targets and shows clean execution in Vehicle, Lodging, and Cross Border, the operational narrative around mix shift, compliance costs, and debt load will likely matter more than the headline appeal of a single football club partnership.
What The Corpay Forecasts Assume
Corpay's narrative projects revenue of US$6.6b and earnings of US$1.9b by 2029, based on analyst expectations that the top line will expand at 9.4% a year and that net income will rise by roughly US$0.8b from about US$1.1b today.
Discover how Corpay's fair value reflects a 15% potential upside to its current price before other investors respond to that opportunity.
Exploring Other Perspectives
Fair value estimates from three members of the Simply Wall St Community span from US$461 to about US$633.9b, a very wide range that signals sharply different views on Corpay. Those opinions do not yet reflect the Newcastle United FX agreement or the pending US$100m settlement risk, so you may want to review several contrasting viewpoints before forming your own stance.
Explore 2 other Corpay fair value estimates, including one that suggests it could be worth just $461.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Corpay research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corpay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corpay's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corpay?
If the Corpay story has sharpened your thinking but you want a wider opportunity set, broaden your watchlist with a few focused stock lists built around clear financial traits rather than hype.
- For investors who care most about steady balance sheets and disciplined funding, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without leaning heavily on fragile financing.
- If your priority is limiting downside risk, use the 30 resilient stocks with low risk scores to narrow the field to businesses that score well on resilience instead of headline excitement.
- For readers hunting for under followed opportunities with robust fundamentals, scan the 18 high quality undiscovered gems that may not be on every investor's radar yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com