
Cohu (COHU) Returned To Profit, Is The 22% Undervalued Case Still Convincing?
Cohu (COHU) is back in the spotlight after third quarter 2026 results showed sales of US$172.96 million and a return to profitability, supported by expectations for higher high performance computing revenue and manufacturing expansion plans.
Cohu shares have been volatile around the latest earnings, with the stock down 4.89% on the day to US$50.79 after a recent 7 day share price return of 5.90% and a 30 day decline of 25.46%.
Even with that pullback, momentum over a longer stretch remains strong, with a year to date share price return of 106.38% and a 1 year total shareholder return of 113.49%. The 3 year and 5 year total shareholder returns of 62.11% and 41.36% hint at how investors have gradually reassessed both the growth opportunity and the risks around Cohu as it scales its high performance computing and recurring revenue lines.
Spot emerging peers riding the same high performance computing wave as Cohu by scanning our hand picked 54 AI infrastructure stocks.Cohu now appears to be a stronger business than it was a year ago. After such a sharp share price run, the key question is whether that progress is already fully reflected in the valuation.
Most Popular Narrative: 22% Undervalued
Cohu’s most followed valuation storyline pegs fair value at $65, above the last close at $50.79. This puts the recent pullback in a different light for anyone weighing upside against execution risk.
Recurring revenue already represents about 60% of total quarterly revenue and grew 25% year over year in 2025, which can provide a more stable base of consumables, service and interface income that supports revenue and earnings even if new systems demand softens.
See why 0 investors see Cohu as 22% undervalued.
Result: Fair Value of $65 (UNDERVALUED)
Still, if AI HPC projects slow or high bandwidth memory inspection margins come under pressure, the 22% undervalued narrative on Cohu could quickly look fragile.
Find out about the key risks to this Cohu narrative.
Another View On Cohu’s Value
There is a very different read on Cohu when looking at the SWS DCF model. At a share price of $50.79 the stock screens as overvalued against an estimated future cash flow value of $12.33. That gap raises a simple question: Are analysts too optimistic or is the DCF too harsh?
Look into how the SWS DCF model arrives at its fair value.
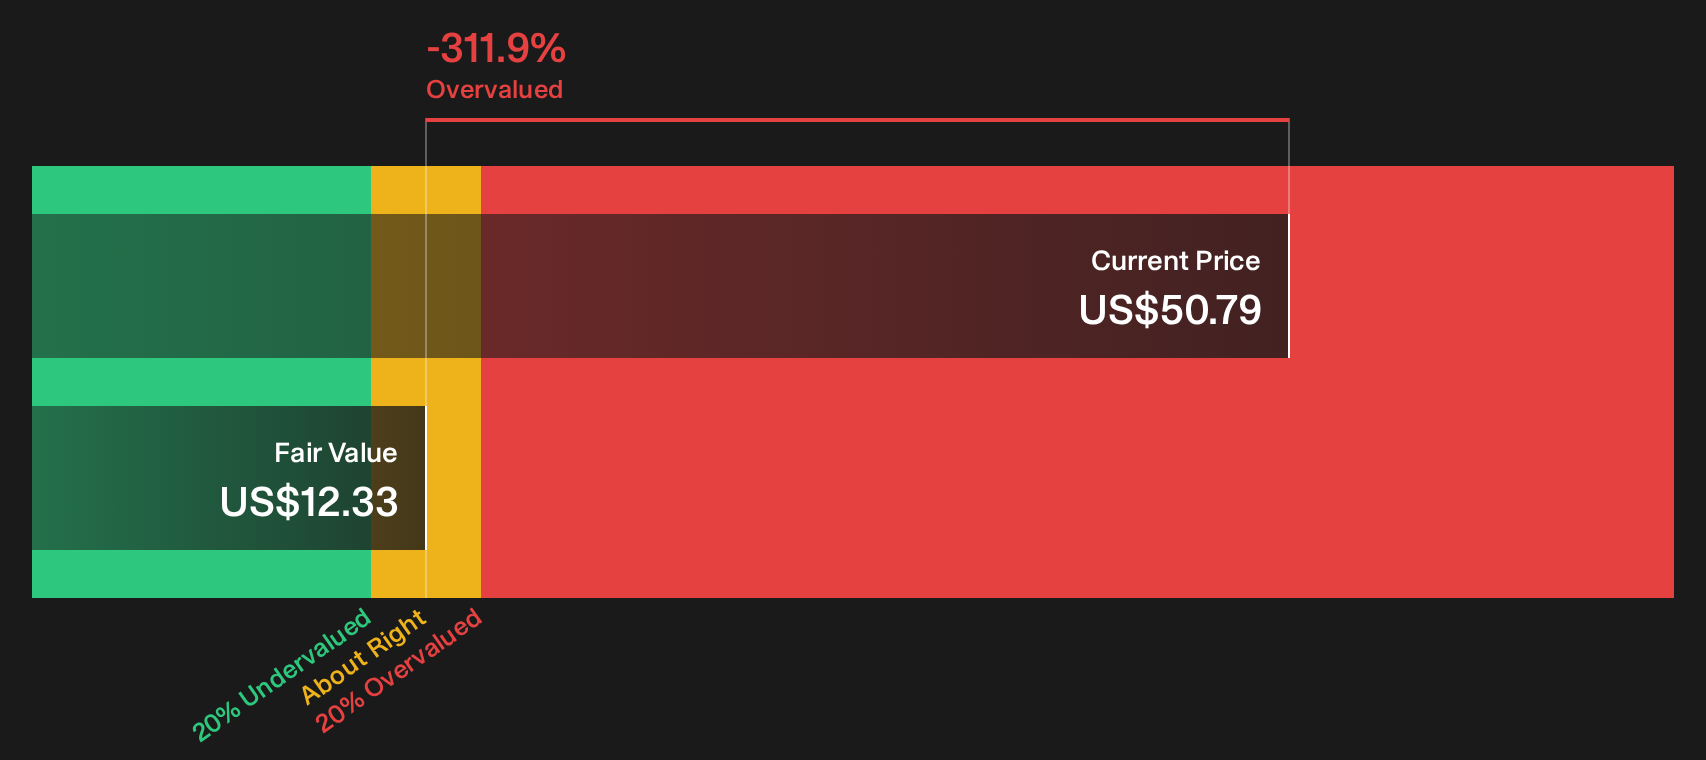
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cohu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Cohu’s value story. Act while the data is fresh and walk through the numbers yourself, starting with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cohu?
You have already done the hard work by understanding Cohu. Do not stop here. Broaden your watchlist now while these themes are still taking shape.
- Target potential bargains trading below estimated worth by running a focused search through 29 high quality undervalued stocks.
- Anchor your portfolio around balance sheets that look resilient in tough conditions by scanning the list of solid balance sheet and fundamentals (25 results).
- Spot lesser known opportunities before they hit everyone’s radar by filtering for 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com