
What Outokumpu Bulls Got Right
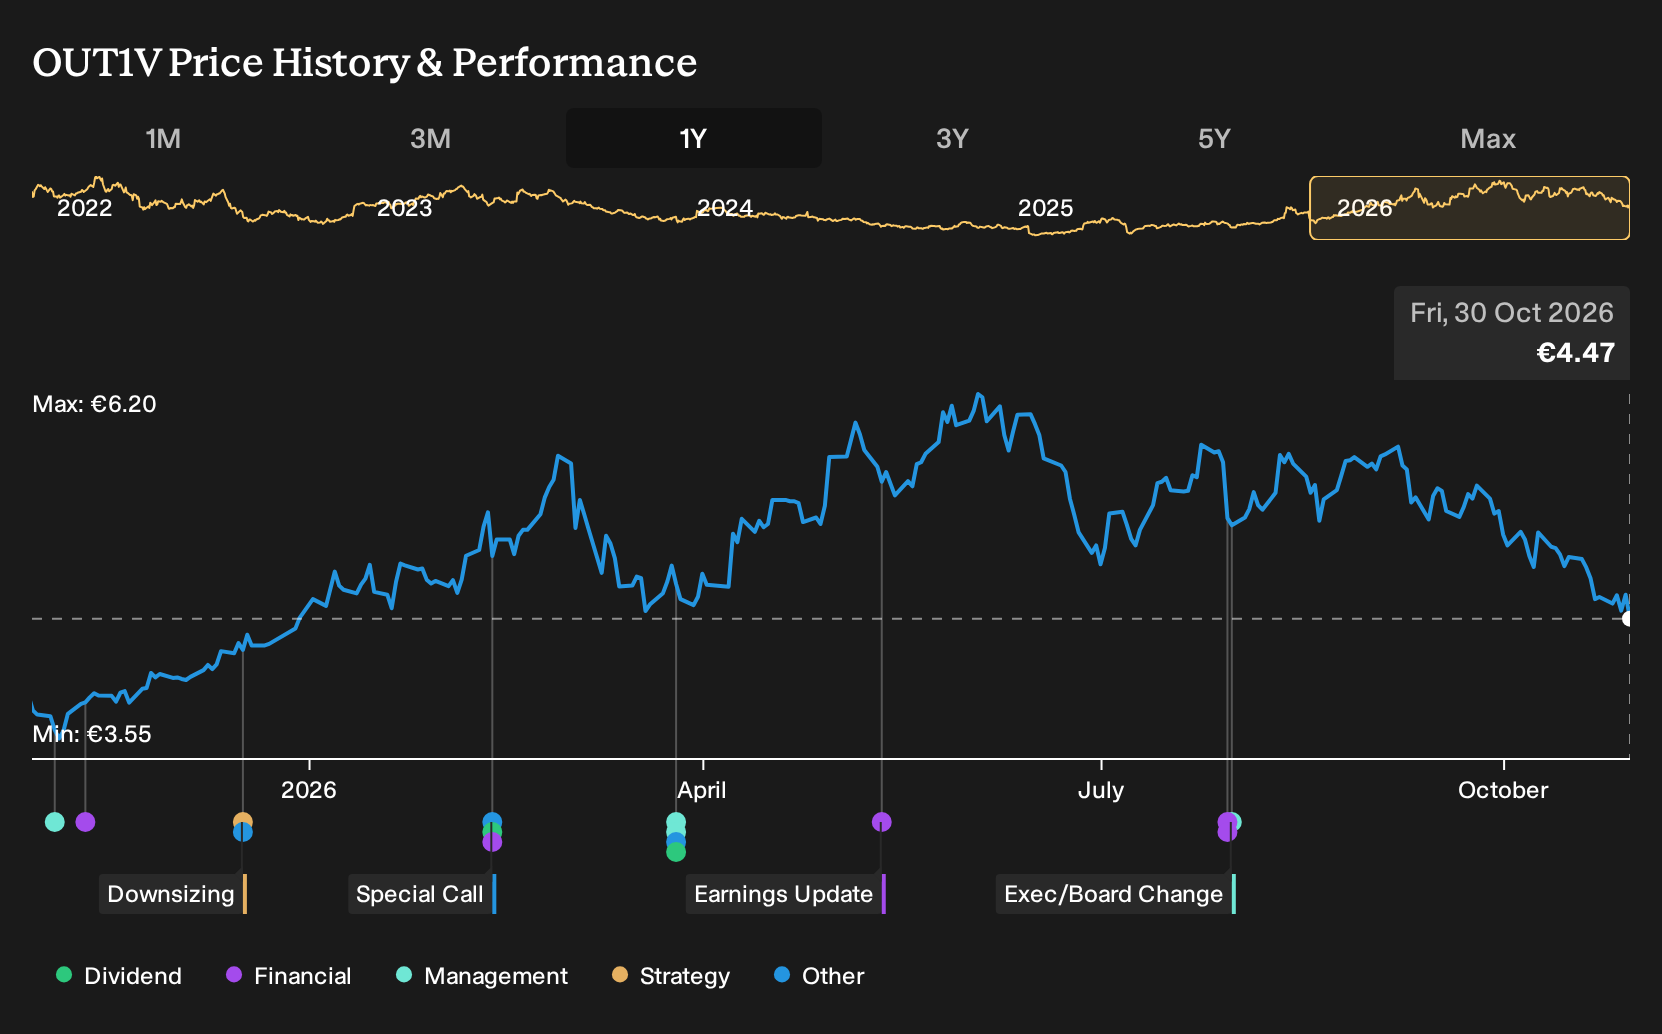
Outokumpu’s year was not defined by headlines about stainless steel in general, but by specific moves such as the long term ground support contract at the Kemi chrome mine that tied a key raw material asset to a dedicated supplier. Holding Outokumpu over the past year would have returned 23.0%, including dividends. If you had been deciding on 30 October 2025, how much conviction would you have needed in that kind of contract backed, decarbonization focused business model?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Outokumpu has already moved. Pinpoint other ways to investigate the theme among 33 best rare earth metal stocks.
The Two Outokumpu Stories Investors Had To Weigh
The shares cost €3.77 at the start of the period, and anyone looking at Outokumpu then had to decide which story felt more realistic.
The bullish Narrative put Fair Value at €4.5, 19% above the start price. It leaned on revenue rising 15.9% a year and profit margins shifting from a loss to 3.4%, helped by accelerated cost savings and premium pricing for low carbon stainless steel.
The bearish view still acknowledged decarbonization but set Fair Value at €3.48, 8% below the start price. It focused on weak European demand, pressure from low cost imports, and the risk that cost cutting would matter more than growth.
What The Results Changed For Outokumpu
Outokumpu’s clearest proof point was operational. Q2 2026 revenue reached €1,582m with net income of €25m, compared with €1,486m and a €19m loss a year earlier, so net margin shifted from a 1.3% loss to a 1.6% profit. That supported the optimistic margin story, while the ongoing EUR 100m restructuring program reminded investors that cautious cost focus still mattered. Overall, the evidence cut both ways.
The lesson travels easily. When a thesis hangs on margin repair, track net income and net margin across several reports and compare them with any cost saving targets before placing too much weight on a broader growth narrative.
What Outokumpu’s One Year Gain Already Prices In
Outokumpu now trades at €4.47, up 23.0% over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s quote as paying for a lot of the cautious scenario already.
The Narrative turns on whether long dated alloy projects, low CO2 metals technology and cost programs turn heavy investment into durable earnings. Anyone buying at today’s level has to judge if those projects can cover higher Finnish mining costs and still support returns on committed capital.
"Although Outokumpu Oyj benefits from reduced stainless imports into Europe and the Americas as trade measures favor regional producers, persistent weakness in European end user demand in consumer, transportation and automotive segments and fading manufacturing PMI readings risk leaving capacity underutilized, which could cap stainless revenue and limit operating leverage in earnings."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 41% below our estimate - targets long term utility and critical infrastructure projects with recyclable access mat rentals.
- Company 2 - 21% below our estimate - shifts its order book toward cleaner fuel vessels while working through a large backlog.
- Company 3 - 43% below our estimate - rolls out AI assisted pricing platforms to deepen consumer savings and partner monetization.
That is three of the list. See the full list of 199 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com