
Has Blue Owl Capital (OWL) Fallen Far Enough To Look Fully Priced?
Blue Owl Capital has seen its share price swing sharply this year, and the question now is whether the current valuation really lines up with what the business is earning. After a tough stretch, investors are weighing fresh fundraising and dividend news against a share price that has moved around a lot in 2026.
- The stock is down 32.5% year to date, which puts the spotlight squarely on whether the earnings behind Blue Owl Capital can support today's market valuation.
- Record institutional fundraising, a larger presence in Abu Dhabi's financial centre and the latest dividend decision may support different expectations for future fee income and profit quality than the recent share performance suggests.
- The analysts covering Blue Owl Capital have run their own numbers. See what analysts think Blue Owl Capital's shares could be worth.
The issue now is whether Blue Owl Capital's current share price is justified by the earnings investors can reasonably expect from the business.
If you want to sanity check Blue Owl Capital against other income-oriented ideas, compare it with companies in the 5 dividend fortresses.
Has Blue Owl Capital Run Too Far on Earnings?
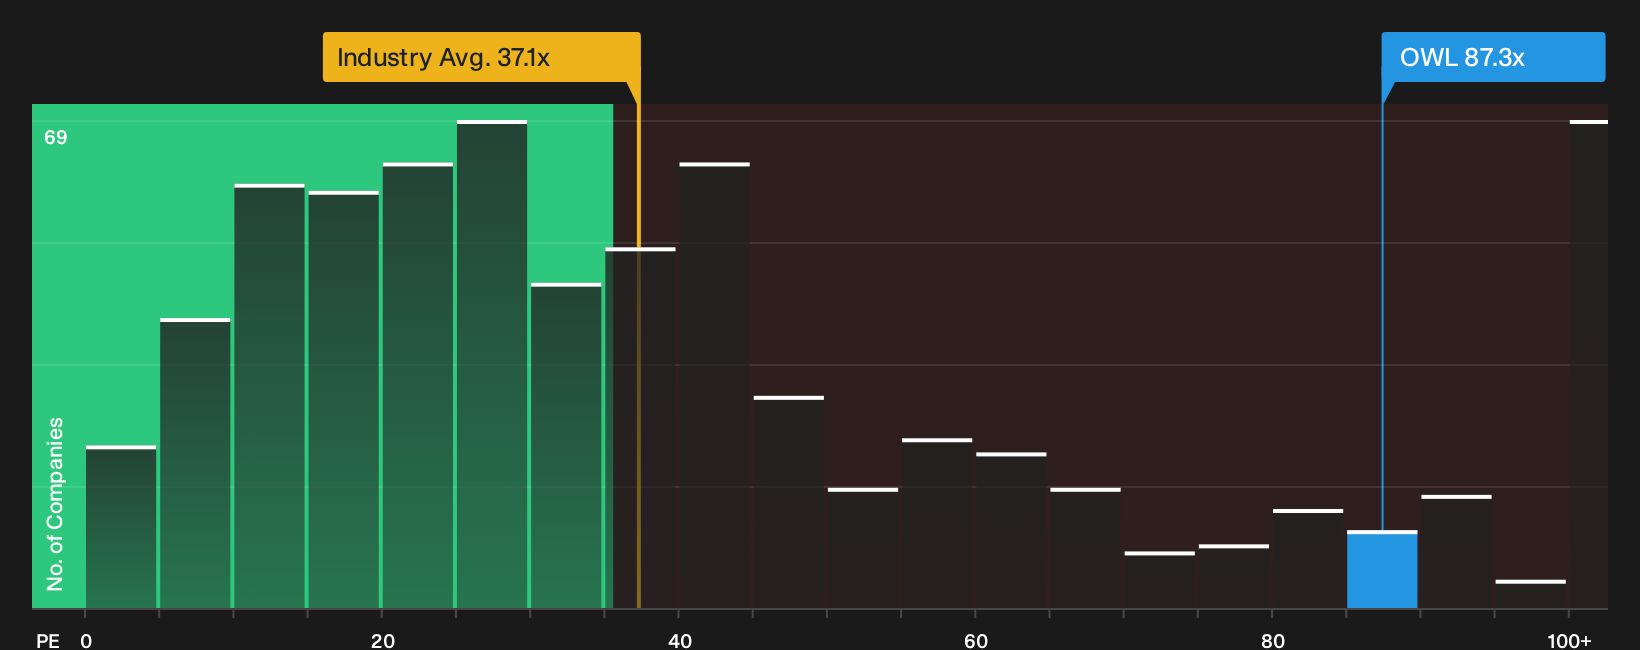
The P/E ratio suits Blue Owl Capital because earnings are the main driver of how this asset manager creates value for shareholders. The stock currently trades on a P/E of 87.3x, which is far above both the Capital Markets industry average of 37.1x and the peer group average of 28.8x. On this metric alone, the shares carry a heavy premium to comparable businesses.
The fair multiple model, which blends Blue Owl Capital's growth profile, profitability, size and risk, flags this P/E as higher than what that framework would usually assign. The gap is wide enough that it reads more as a warning signal than a precise target. Record fundraising and the latest dividend decision give supporters concrete reasons to accept a richer valuation; yet the current earnings multiple already prices in a lot of optimism relative to sector norms. Explore the numbers behind Blue Owl Capital's P/E valuation.
The Blue Owl Capital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Blue Owl Capital leaves off by making clear what kind of future growth, margins and earnings would need to materialise for the shares to be worth meaningfully more or less than today. Each Narrative presents Blue Owl Capital's fair value as a thesis about how the business could evolve that you can revisit over time, and they sit on the stock's Community page.
Community views on Blue Owl Capital split between those who see upside in the fee engine and those who think execution risks already cap the story.
Bull case: 18% undervalued
"Exceptional long term opportunities in digital infrastructure, including a more than 140 data center footprint with about 15 to 15.3 gigawatts of capacity, a pipeline of over US$100b and the planned seeding of a US$6.5b data center REIT, are creating avenues for additional fundraising and deployment that can lift management fee revenue..."
Discover why this Narrative puts Blue Owl Capital at 18% undervalued.
Bear case: 15% overvalued
"Growth in private wealth products such as ORENT, OCIC, OWLCX and ODIT has added a sizeable semi liquid evergreen channel, however, the period of elevated redemption requests at OCIC and reports of a 39% quarterly redemption request rate for OTIC highlight that renewed liquidity stress or sentiment swings in these vehicles could force asset sales or constrain fundraising, which would cap AUM growth and reduce fee related earnings leverage..."
Explore why this Narrative puts Blue Owl Capital at 15% overvalued.
Blue Owl Capital’s price tag is only one piece of the decision
Before you treat Blue Owl Capital’s valuation as the whole story, factor in that Simply Wall St’s checks have flagged specific areas of concern that investors often overlook until they matter most. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com