
Sanofi (ENXTPA:SAN) On Raised Guidance And Strong Q3 The Valuation Debate Returns
Sanofi (ENXTPA:SAN) came into focus after raising its 2026 guidance, with management now expecting low-teens sales growth at constant exchange rates and mid-teens growth in business EPS for the year.
The guidance hike and strong third quarter print come after a sharp short-term rebound in Sanofi’s shares, with a 1-day share price return of 4.71% and a 30-day share price return of 9.77%. By contrast, the year-to-date share price return is down 3.13% and the 1-year total shareholder return is down 3.88%. Over longer periods, total shareholder returns stand at 7.27% over three years and 11.69% over five years, suggesting that momentum has only recently started to rebuild.
Scan how Sanofi’s rebound compares with other large pharmaceutical players by reviewing our hand picked list of 218 resilient stocks with low risk scores with resilient profiles and lower risk scores.
After that quick bounce in Sanofi’s share price, the real question is whether the current level already reflects the upgraded outlook or still leaves a margin of safety for investors who wait.
Most Popular Narrative: 10.4% Overvalued
On Simply Wall St, the leading narrative for Sanofi anchors fair value at €72.23 per share, compared with the recent close at €79.74, which frames the recent guidance upgrade against expectations that investors are paying above that estimate.
Der französische Pharmariese Sanofi bietet Anlegern derzeit eine interessante Kombination aus attraktiver Bewertung, starker Dividendenrendite und solider operativer Dynamik. Attraktive Bewertung und Kursrücksetzer Die Aktie hat in den vergangenen Monaten nachgegeben und bewegt sich im Bereich von rund 76 bis 77 EUR. Damit notiert sie deutlich unter ihren früheren Höchstständen. Für langfristig orientierte Investoren eröffnet dieser Rücksetzer einen günstigen Einstiegspunkt, da das Kurs-Gewinn-Verhältnis (KGV) auf Basis der erwarteten Gewinne moderat ist und Analysten den fairen Wert spürbar höher ansetzen.
See why 6 investors see Sanofi as 10% overvalued.
Result: Fair Value of €72.23 (OVERVALUED)
Still, the Sanofi story can change quickly if key therapies underperform expectations, or if regulatory setbacks slow the broad pipeline of partnered projects.
Find out about the key risks to this Sanofi narrative.
Another View On Sanofi’s Valuation
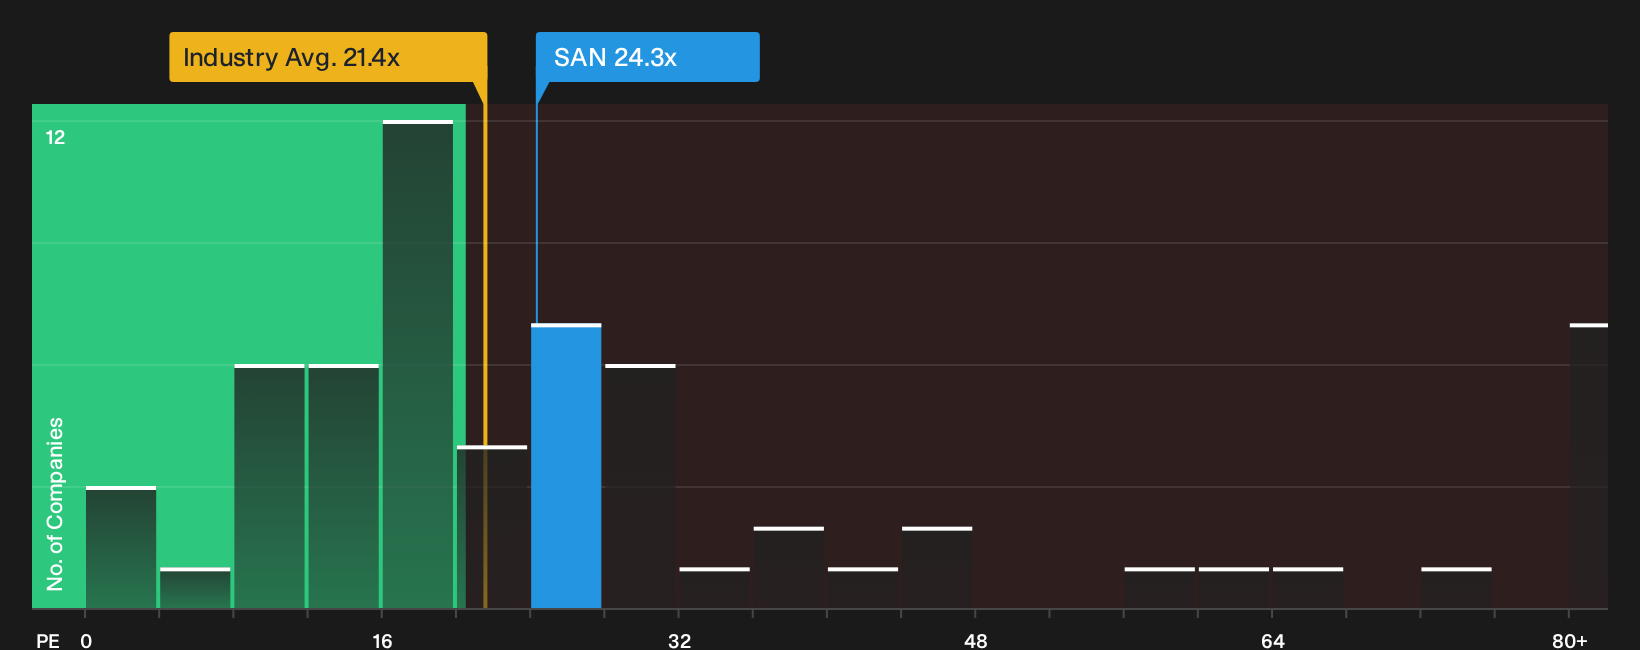
The first lens on Sanofi centered on a fair value of €72.23 and flagged the shares as 10.4% overvalued. A different angle comes from the P/E ratio. The stock trades on 24.3x earnings compared with a peer average of 18x and a European pharma average of 21.6x, while the fair ratio is 38.3x.
That combination sends a mixed message. Relative to similar drug makers, Sanofi appears expensive, yet the fair ratio indicates the market could justify a higher multiple if earnings track expectations. The question for you is which signal deserves more weight at the moment: the premium to peers or the gap to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sanofi’s value and risk profile will not resolve themselves. Check the data, pressure test your own thesis, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Sanofi?
If Sanofi has you rethinking your watchlist, use this momentum to refresh your broader opportunity set with focused screens that cut through the noise.
- Target resilient cash generators by reviewing our list of solid balance sheet and fundamentals (203 results) that can better withstand shocks and funding stress.
- Hunt for potential value opportunities through the 199 high quality undervalued stocks that highlights companies with strong fundamentals priced below their estimated worth.
- Boost your passive income potential with the 221 dividend fortresses that filters for higher yielding businesses with robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com