
Raised Guidance Could Reshape The Case For Benchmark Electronics Stock
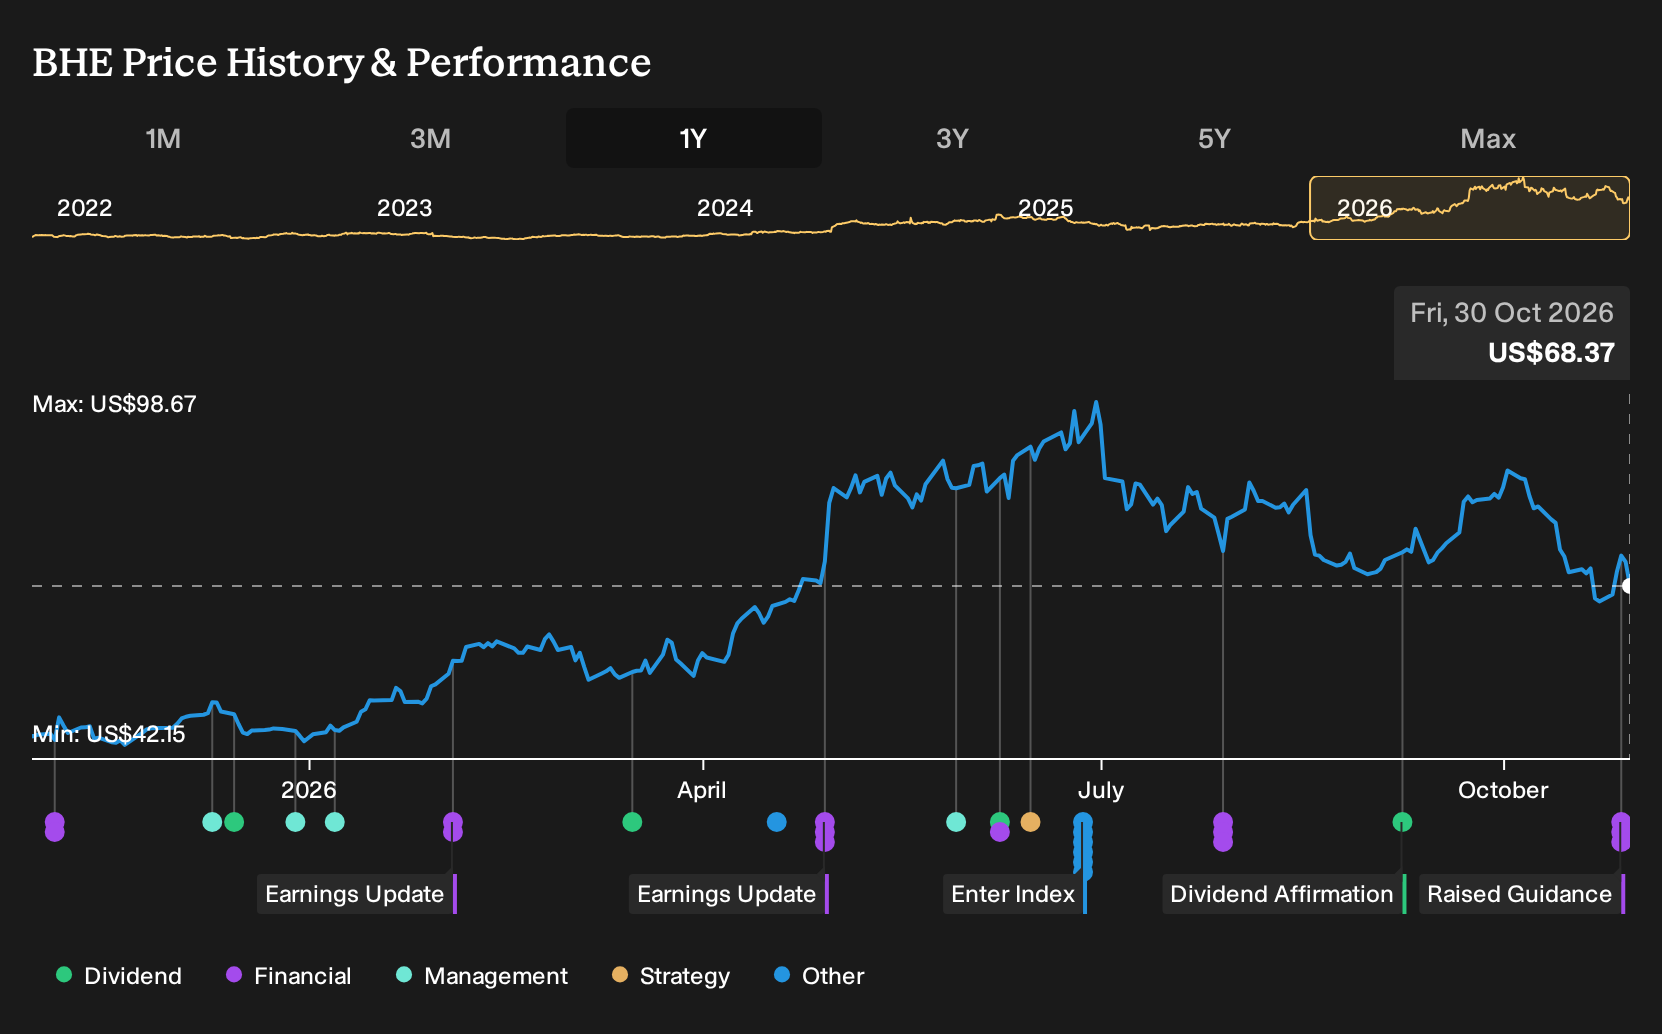
- Benchmark Electronics reported record third quarter 2026 revenue of US$810.9 million and higher earnings, then raised full year and fourth quarter guidance on broad based demand and healthy bookings.
- The company now targets about 16% revenue growth in 2026 and expects to move beyond US$3b in annual sales, which reflects management confidence in its transformation across semiconductor capital equipment, medical, industrial, and advanced computing and communications programs.
- We will now look at how Benchmark Electronics' investment narrative could be reshaped by this record quarter and raised full year guidance.
Benchmark Electronics Investment Narrative Recap
To own Benchmark Electronics, you need to believe the current program ramps in semiconductor capital equipment, medical, industrial, and advanced computing and communications can sustain healthy orders and earnings quality. The raised 2026 outlook and record third quarter results support that view in the near term. The key short term catalyst is continued execution on these new and expanded programs.
The biggest risk is that this stronger operating performance does not keep up with expectations embedded in a relatively full P/E and prior valuation work. Any cooling in bookings or supply chain friction in complex components could pressure margins or delay revenue, which would weaken that core thesis.
The clearest announcement to focus on is the raised full year 2026 guidance, including the target of about 16% revenue growth and management’s expectation of moving beyond US$3b in annual sales. That update links directly to the current quarter’s record US$810.9 million in revenue and faster earnings growth than sales.
For you as a shareholder or potential shareholder, this guidance raises the bar for execution. It frames near term potential around sustained demand across AI related AC&C, Semi Cap and medical programs while sharpening attention on execution risk, working capital discipline, and the company’s ability to manage longer component lead times without eroding earnings quality.
Benchmark Electronics' narrative projects US$3.7b revenue and US$145.3 million earnings by 2029. This projection is based on analysts assuming 9.1% yearly revenue growth and an earnings increase of about US$92 million from US$53.1 million today.
Uncover how Benchmark Electronics' fair value indicates a 26% potential upside to its current price before other investors close that discount.
Exploring Other Perspectives
One alternate view on Benchmark Electronics leans heavily on the risk that AI hardware demand cools. Those bearish analysts were only penciling in about 7.1% annual revenue growth to roughly US$3.6b and earnings of US$119.9 million by 2029. The new guidance could challenge that script, so explore both narratives before deciding what feels reasonable.
Explore another Benchmark Electronics fair value estimate, including one that suggests as much as 33% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Benchmark Electronics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Benchmark Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Benchmark Electronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Benchmark Electronics?
If this update on Benchmark Electronics has sharpened your thinking, use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly surface other stocks that fit the kind of balance sheet strength, valuation profile, or income focus you care about most.
- If capital preservation sits high on your list, start with companies that score well on resilience and risk, using the 30 resilient stocks with low risk scores to filter for businesses with steadier profiles.
- For readers who want quality at a reasonable entry point, the 29 high quality undervalued stocks can highlight stocks where fundamentals and current pricing look out of sync.
- If you are building an income focused portfolio, scan for robust payers through the 5 dividend fortresses and see which businesses might help anchor your yield targets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com