
Brown Forman (BF.B) Q1 Beat Leaves Valuation Questions Ahead Of Q2
Brown-Forman (BF.B) is back in focus as investors look ahead to its upcoming fiscal Q2 2027 earnings, after the stock moved higher on a narrow profit beat in Q1.
Recent trading has been choppy for Brown-Forman, with a 1-day share price gain of 2.39% and a 30-day share price return of 9.58% offset by a weak 3-year total shareholder return that has fallen 47.84%. That mix suggests short term momentum has picked up around the Q1 profit beat and upcoming Q2 results, while longer term holders have endured a much tougher stretch that keeps sentiment and valuation under close watch.
Capitalize on the renewed interest around Brown-Forman by reviewing hand-picked consumer stocks showing stronger price action and fundamentals through the 29 high quality undervalued stocks.The short term rebound in Brown-Forman is clear. The bigger call now is whether recent buyers are early in a recovery or already late to the party as valuation resets.
Most Popular Narrative: 2% Overvalued
Brown-Forman last closed at $28.71, a touch above the most followed fair value estimate of $28.26 that is built on cash flow, margins and steady expansion rather than fast growth assumptions.
The company’s emphasis on a productivity for growth mindset, together with a step down in annual capital expenditure to a guided US$60 million to US$70 million and record prior year free cash flow of just under US$0.9b, points to further room for strong cash generation and potential support for earnings quality even as reported operating income guidance for fiscal 2027 is for a 3% to 5% decline.
See why 26 investors see Brown-Forman as 2% overvalued.
Result: Fair Value of $28.26 (OVERVALUED)
Still, Brown-Forman’s story can be knocked off course if weakness in key developed markets lingers or if the higher cost of whiskey further impacts margins.
Find out about the key risks to this Brown-Forman narrative.
Another View: What Multiples Say About Brown-Forman
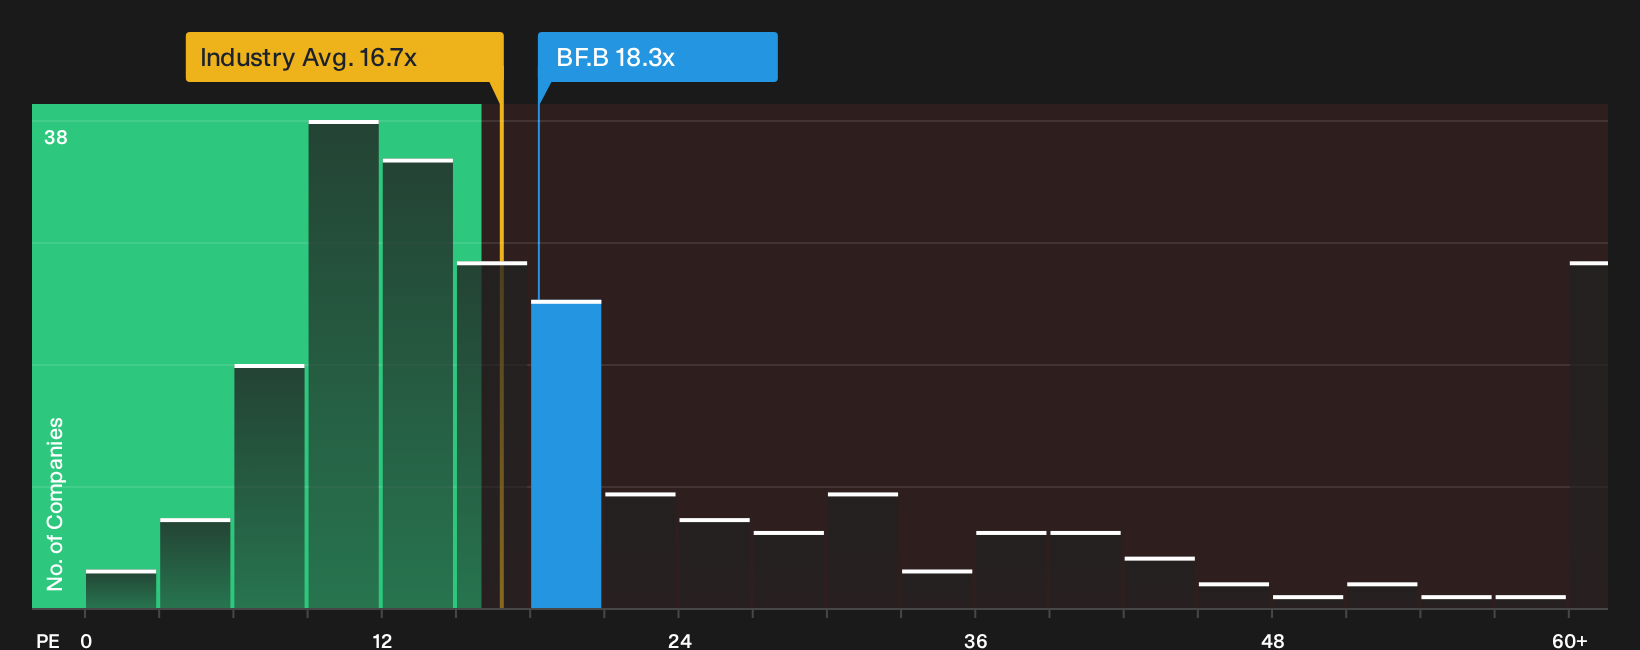
Analysts see Brown-Forman as roughly fairly priced at a $28.26 fair value, yet our ratio work paints a split picture. The stock trades on an 18.3x P/E, which looks cheap against peer averages of 30.1x, but expensive versus a fair ratio of 16.7x that the market could drift toward.
That mix suggests some room for optimism if peers stay richly valued, and some valuation risk if sentiment cools toward the sector. Which side of that trade-off matters more to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Brown-Forman so far. If you want to move quickly and stress test that sentiment against your own read of the numbers, start with the 3 key rewards and 1 important warning sign.
Looking for more Brown-Forman sized investment ideas?
If Brown-Forman has sharpened your focus on price, quality and timing, broaden your watchlist now so you are not reacting after the next move.
- Target potential upside by scanning a curated 29 high quality undervalued stocks that already combine stronger balance sheets with more appealing pricing.
- Strengthen your income stream by reviewing a focused set of 5 dividend fortresses built around higher yields and resilient cash generation.
- Reduce portfolio stress by filtering for 30 resilient stocks with low risk scores that score better on financial health and volatility than the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com