
Is Huron Consulting Group (HURN) Fairly Valued After Joining Key S&P Indexes?
Huron Consulting Group (HURN) just joined the S&P 600 and the broader S&P Composite 1500, slotting into the S&P 600 Industrials sector as index trackers adjust their holdings.
At a share price of US$194.43, Huron Consulting Group has seen a 1-month share price return of 23.97% and a 90-day share price return of 28.11%. The 1-year total shareholder return of 18.24% and 5-year total shareholder return of 261.73% point to momentum that has been building over several years, with the recent S&P index additions likely sharpening investor focus and perceptions of the business.
Scan beyond Huron Consulting Group and review other index-ready compounders appearing in our curated 18 high quality undiscovered gems for ideas that may not yet be fully on the market's radar.
Index inclusion has pulled Huron Consulting Group sharply higher in a short window. After that kind of move, does the current valuation still leave enough upside to justify taking on new risk?
Most Popular Narrative: 4% Undervalued
The most followed narrative on Huron Consulting Group pegs fair value at $202, only modestly above the last close at $194.43. The gap comes down to how much weight you put on its mix of recurring work, margin potential, and capital returns.
Huron Consulting Group ongoing shift toward outcomes-based, fixed-fee and recurring contracts, which reached 67% of revenue before reimbursable expenses by 2025, is increasing exposure to higher margin managed services and contingent-fee work that can support earnings growth.
See why 4 investors see Huron Consulting Group as 4% undervalued.
Result: Fair Value of $202 (UNDERVALUED)
Still, this hinges on Huron Consulting Group turning digital bookings into profitable work, while preventing rising support and technology costs from eroding those higher margin ambitions.
Find out about the key risks to this Huron Consulting Group narrative.
Another Take On Huron Consulting Group’s Valuation
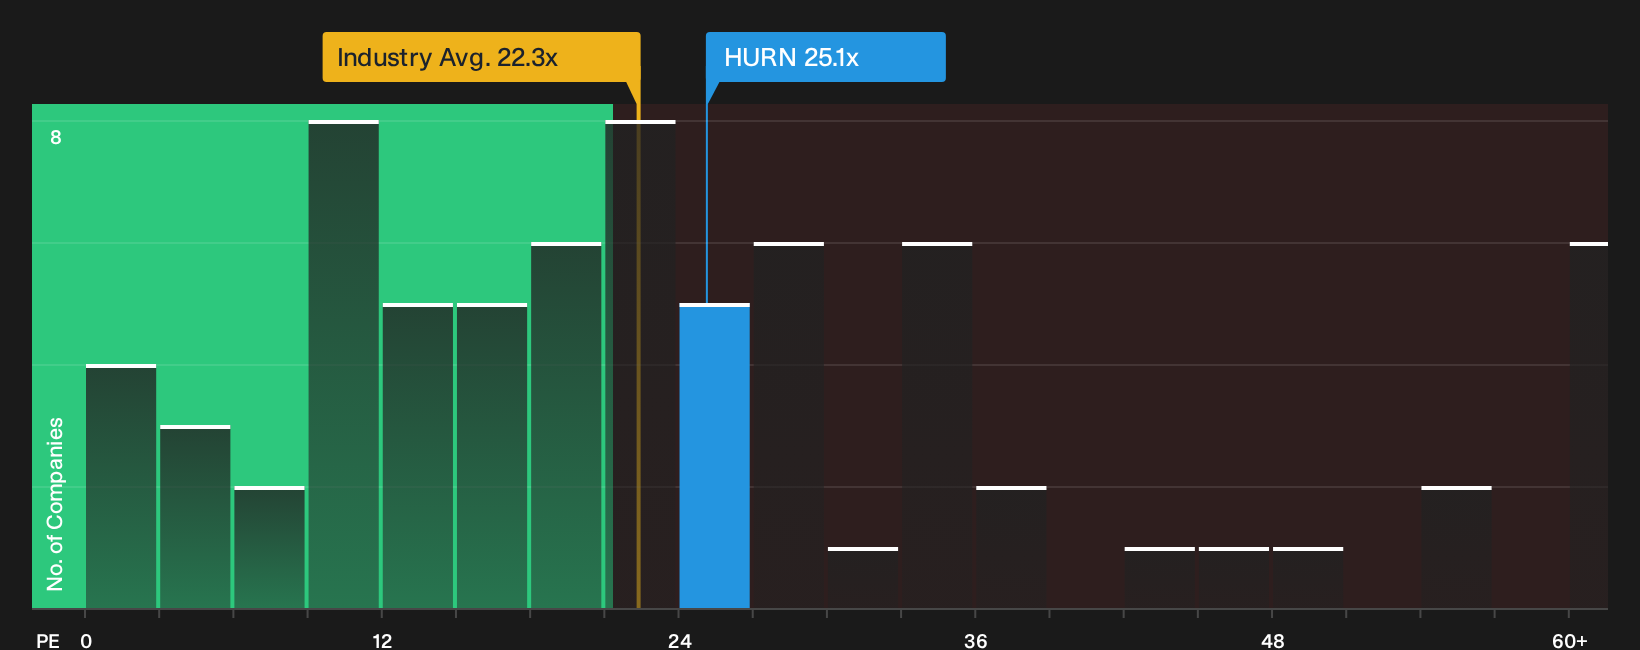
On price targets and DCF work, Huron Consulting Group screens as undervalued. Through the earnings multiple lens, the picture is less forgiving. The current P/E of 25.1x is above both the US Professional Services industry at 22.3x and the 23.5x fair ratio, which points to some valuation risk if sentiment cools.
The fair ratio is simply where the P/E could drift if the market leans back toward its longer run relationship with the fundamentals. The key question is whether you think recent execution justifies paying more than that.
For more context on how this pricing stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Huron Consulting Group's pricing and fundamentals can pull investors in opposite directions, so move quickly to review the data, weigh both the upside and the risk factors, and decide if the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Huron Consulting Group?
If Huron Consulting Group has your attention after its index move, do not stop there because missing other compelling setups could cost you better risk reward trades.
- Target resilient upside by using the 30 resilient stocks with low risk scores that focuses on companies with steadier profiles when markets turn choppy.
- Pursue value-led opportunities through the 29 high quality undervalued stocks that highlights potentially mispriced businesses with stronger fundamentals than their share prices suggest.
- Build a sturdier core portfolio with the list of solid balance sheet and fundamentals (25 results) that spotlights financially sound stocks designed to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com