
Is Global Partners (GLP) Fully Valued Following Its Latest Cash Distribution?
Global Partners (GLP) drew fresh attention after its board declared a third quarter cash distribution of $0.7850 per unit, which equates to $3.14 on an annualized basis, payable on November 13, 2026.
At a share price of US$47.44, Global Partners has eased over the past week and quarter, with the 7 day and 90 day share price returns both declining. Yet the year to date share price return of 12.26% and 5 year total shareholder return of 200.40% point to longer term momentum that this latest cash distribution now feeds into investor sentiment.
Capitalize on this distribution theme by scanning 5 dividend fortresses, which, like Global Partners, puts regular cash returns at the center of its investor proposition.Bulls point to Global Partners’ long record of total returns and fresh cash distribution, while bears focus on recent share softness and flat net income. Which story do the current valuation signals support next?
Most Popular Narrative: 4% Overvalued
Global Partners last closed at $47.44, which sits modestly above the most followed fair value estimate of $45.50 that applies an 8.26% discount rate. That small gap frames a story where valuation is tight, so the bigger question becomes which long term drivers justify paying above that narrative anchor.
Expansion of the company's terminal network through recent acquisitions in key markets is expected to strengthen market presence, enhance distribution efficiency, and drive long-term revenue growth from higher throughput volumes and improved operating leverage.
Ongoing portfolio optimization, with the recent divestment of underperforming retail sites and annual review processes, is likely to focus capital on higher-return assets, supporting better margin performance and earnings consistency.
See why 4 investors see Global Partners as 4% overvalued.
Result: Fair Value of $45.50 (OVERVALUED)
Still, the narrative could crack if long term fuel demand weakens faster than expected, or if heavy asset spending runs into lower utilization and tighter regulation.
Find out about the key risks to this Global Partners narrative.
Another View: Multiples Paint a Cheaper Picture for Global Partners
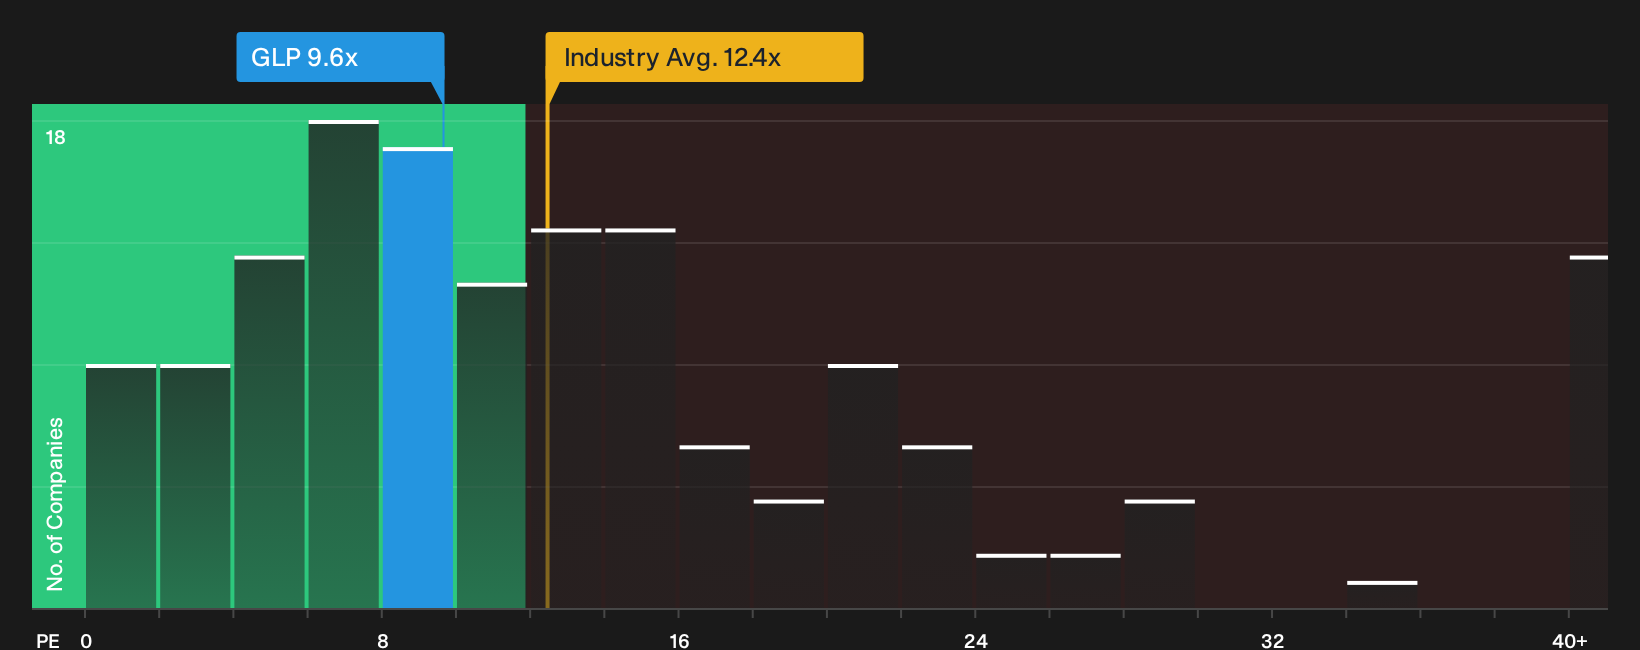
While the most followed fair value narrative pegs Global Partners at $45.50 and labels the stock overvalued, the current P/E of 9.6x tells a different story. It sits well below both the US Oil and Gas industry at 12.4x and the peer average at 14.5x, and under the 11.6x fair ratio that the market could drift toward over time. That gap points to either a discount on today’s earnings power or a market that is pricing in heavier business risks than the DCF style fair value suggests. Which side of that trade-off do you agree with most?
For a closer look at how these earnings multiples stack up against fundamentals, valuation work, and peer data, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Global Partners will always split opinion, so move quickly, test the numbers against your own expectations, then weigh the 4 key rewards and 3 important warning signs.
Looking for more Global Partners style investment ideas?
If Global Partners has you thinking harder about dividends and valuation, do not stop here. The next opportunity you research today could become tomorrow’s core holding.
- Target resilient compounding potential by scanning companies that look undervalued on both quality and price using the 29 high quality undervalued stocks.
- Prioritize financial strength and rest easier at night by filtering for businesses with strong balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Explore potential future market favorites early by reviewing a focused 18 high quality undiscovered gems before more investors take notice.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com