
A. O. Smith (AOS) Stock Faces Q3 Earnings Margin Questions
A. O. Smith came into its Q3 2026 earnings with the stock near US$63, up solidly over the past month, and a reputation as a steady compounder in water heaters and treatment. The headline this quarter is profit resilience. Basic earnings per share reached about US$0.93 as North America delivered US$762 million in sales despite softer water heater volumes. Yet the share price slipped about 0.7% on the day, a muted reaction that sits awkwardly against management’s plan to recycle roughly US$350 million from the China stake sale into buybacks and a tighter, higher margin focused business.
Love A. O. Smith’s earnings resilience and buyback firepower but concerned that softer water heater volumes could cap upside? Take a look at the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$940.5 million vs. US$942.5 million (broadly flat, slightly lower year on year)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$126.3 million vs. US$132.0 million (declined about 4.3%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.93 vs. US$0.94 (eased about 1.6%)
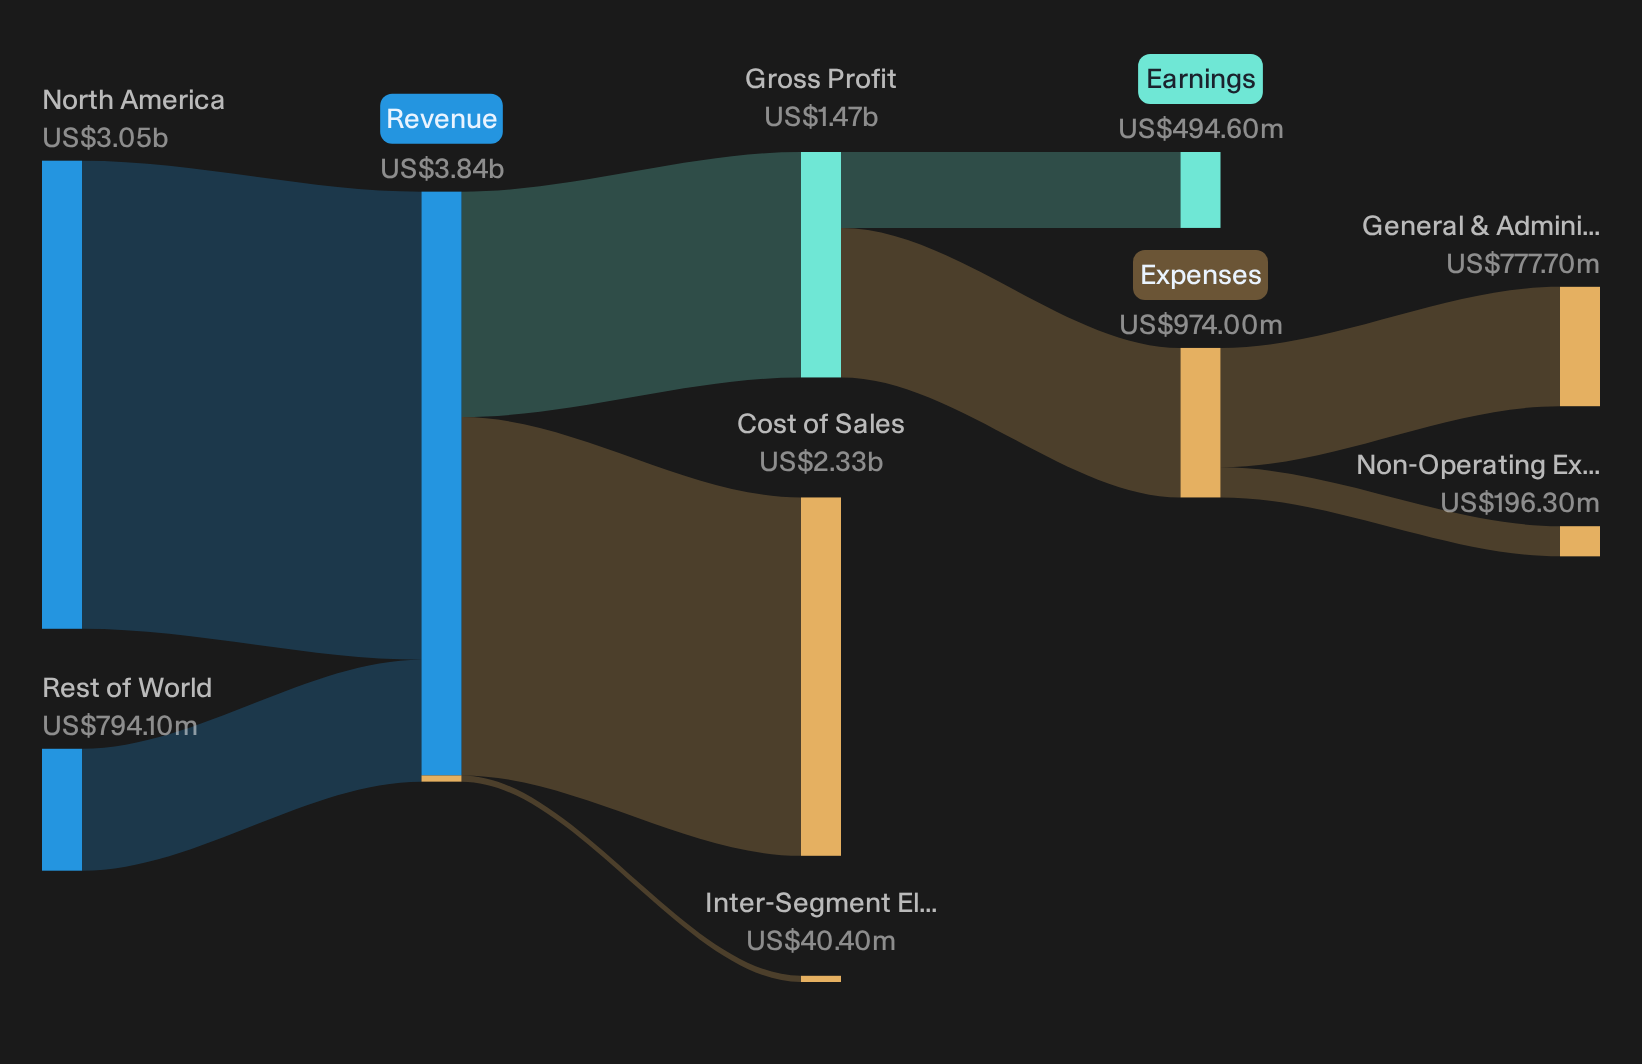
- Trailing 12-Month Net Income, Excl. Extra Items (TTM Q3 2026 vs TTM Q3 2025): US$494.6 million vs. US$530.5 million (down roughly 6.8%)
They’re selling most of China but keeping the brand and upside. Ask Charlie what A. O. Smith’s China sale really changes.
A. O. Smith Bull Case: Margin Levers On Display
The bullish view hinges on A. O. Smith turning product mix and efficiency work into structurally higher profitability.
"Ongoing operational excellence initiatives, including production efficiency, footprint optimization and disciplined tariff mitigation, are already expanding segment margins and should compound into structurally higher net margins and free cash flow conversion."
Q3 shows real progress toward that ambition. North America delivered US$762 million of sales with targeted pricing and a 13% boiler uplift helping offset softer water heaters. Management still aims for roughly 24% North America margin in 2026, even as steel and freight costs are each expected to rise about 15%, which supports the claim that cost programs and mix are doing meaningful work.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
A. O. Smith Bear Case: Cost Gains Still Unproven
The cautious view argues that A. O. Smith’s efficiency push might simply get swamped by rising input costs rather than translate into cleaner profitability.
"While management points to operational excellence programs and AI tools in areas like order management and warranty processing as future efficiency drivers, rising steel, freight, other materials and tariffs that are expected to raise cost of goods by roughly 3% risk absorbing those gains and limiting any improvement in net margins."
Q3 validates the risk, just not decisively. Steel and freight are each expected to rise about 15% and management is leaning on up to 9.5% water heater pricing plus productivity efforts to hold a roughly 24% North America margin. Flat consolidated sales and lower trailing 12 month earnings show cost pressure still biting, even with another small EPS beat and solid cash generation supporting buybacks.
Hunt For Mispriced Earnings Power
A. O. Smith just showed how margin work and buybacks do not always sync neatly with a one day share reaction. The real opportunity sits in finding companies that could be undervalued before the market closes the gap.
- Company 1 - 30% below our estimate - ties together a cloud platform, workplace software and AI tools so enterprise workflows shift onto its stack.
- Company 2 - 46% below our estimate - handles pay-ins and pay-outs for large online platforms expanding into card-light economies and local wallets.
- Company 3 - 35% below our estimate - sells compute racks and a software stack that hyperscalers choose when training generative models strains legacy CPU farms.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com