
Marcus (MCS) Stock Price Drops Despite Record Q3 Earnings
The Marcus stock just took a hit. Shares closed at US$26.55, down 5.4% on the day, even though the company had just posted record Q3 2026 results.
Investors saw the price drop and sold first. The business, meanwhile, printed US$237.8m in quarterly revenue and US$0.60 in basic earnings per share, both ahead of last year. That mismatch between a sliding share price and stronger reported performance is the core sentiment test for Marcus following this earnings release.
Like the revenue and earnings beat from Marcus but uneasy about a share price that dropped on the news? You may want to consider using a list of stocks that pair solid fundamentals with steadier market sentiment by reviewing the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue, Q3 2026 vs. Q3 2025: US$237.8m vs. US$199.5m (up about 19%)
- Net Income, Q3 2026 vs. Q3 2025: US$18.8m vs. US$16.2m (up about 16%)
- Basic EPS, Q3 2026 vs. Q3 2025: US$0.60 vs. US$0.52 (up about 14%)
- Net Profit Margin, Trailing 12 Months vs. Prior Year: 3.2% vs. 1.1% (improved profitability over the trailing period)
Marcus just posted record Q3 results with rising free cash flow. Ask Charlie what makes Marcus confident in more M&A deals.
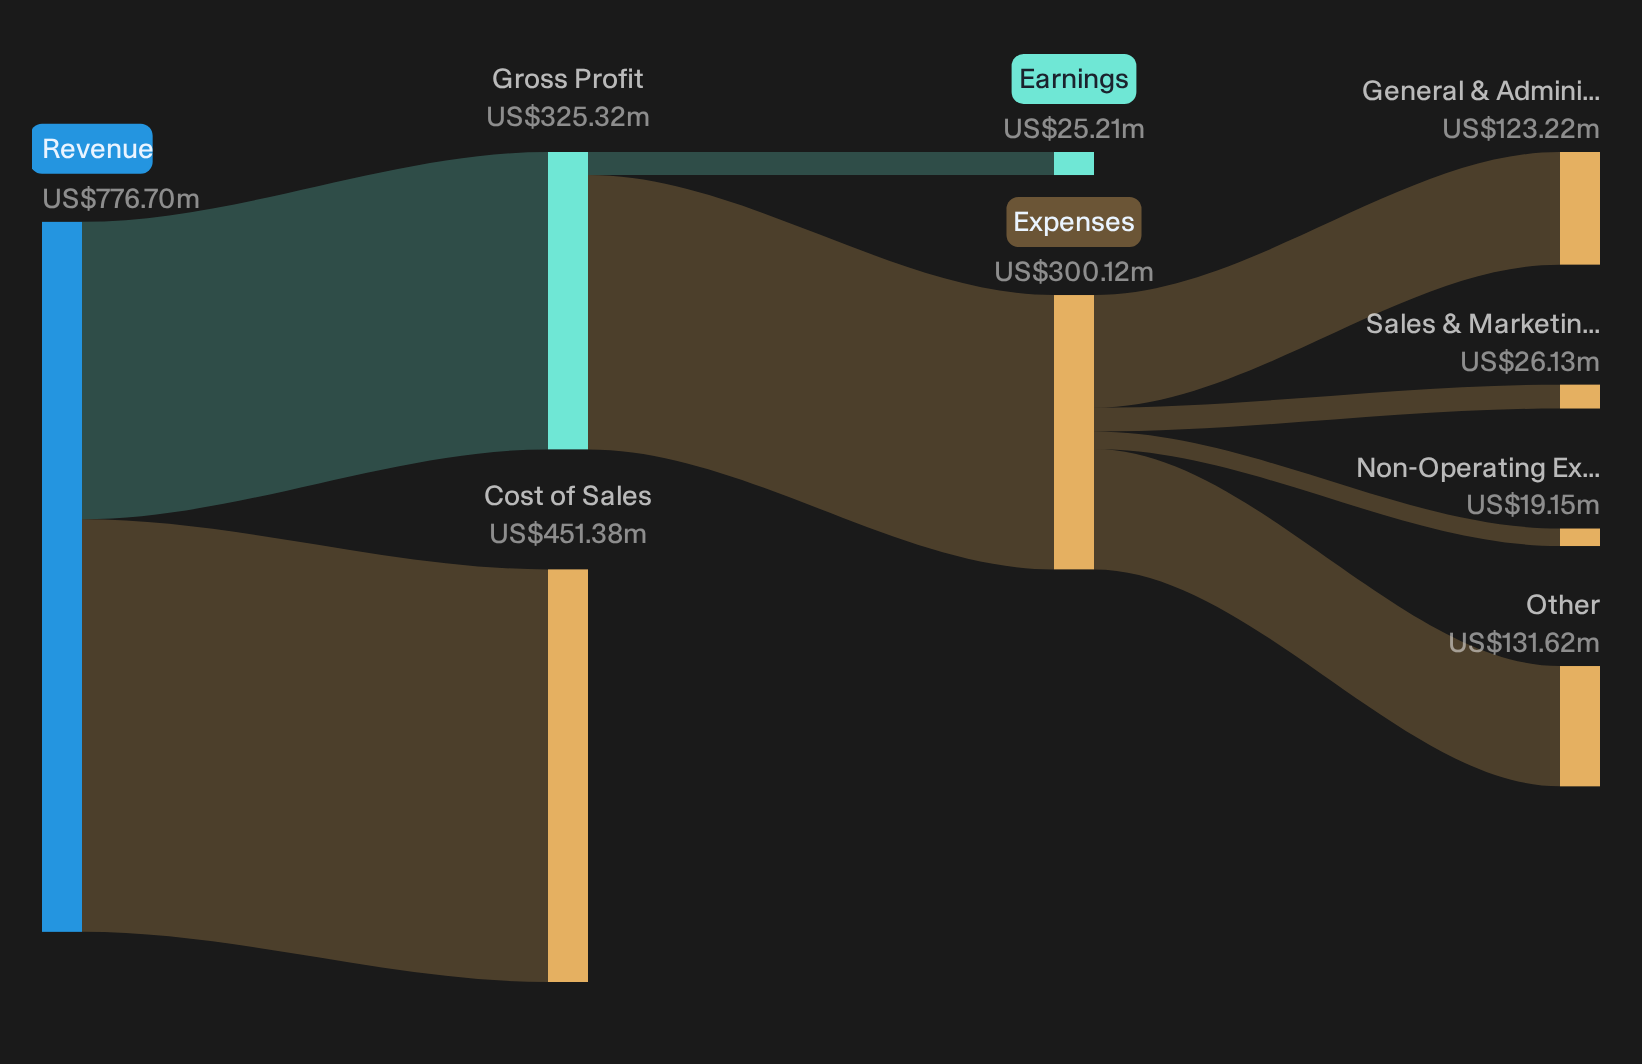
Marcus earnings momentum vs experiential bull story
For anyone leaning into the experiential leisure idea around Marcus, these Q3 numbers mostly back that up. Record quarterly revenue of about US$238m, faster growth in operating income and adjusted EBITDA, and higher net earnings all point in the same direction. Theaters look especially supportive of the thesis, with record seasonal revenue and stronger attendance helping the broader platform story. Hotels did not surge in the same way but still added incremental revenue and stable EBITDA once storm effects are stripped out, which fits a measured, multi leg leisure narrative.
Share pullback and structural worries in focus
The 5.4% price drop after results, together with weaker 1 to 3 month returns, shows that concern around cinemas and asset intensity has not disappeared. Q3 did rely heavily on a strong film slate, which reinforces fears about content driven volatility. Hotel adjusted EBITDA was roughly flat once weather effects are excluded, so that side is not yet clearing every bearish hurdle either. A solid balance sheet with net leverage around 0.8x and more than US$219m of liquidity means near term balance sheet risk looks contained, even if cyclical and structural questions remain.
Are analysts comfortable with Marcus leaning on a strong film slate and record theater performance, or are they trimming their optimism instead? See the consensus price target analysis for Marcus.Hunt For Mispriced Earnings Power
Marcus just showed how a strong report and a weaker share price can collide in the short term. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 41% below our estimate - expands higher margin composite mat rentals as utilities roll out long duration grid and pipeline projects.
- Company 2 - 47% below our estimate - ramps AI powered ad tools and messaging products that help advertisers convert engagement into more measurable campaign outcomes.
- Company 3 - 38% below our estimate - adds manufacturing and supply capacity to support premium protective films sold through installers and dealership partnerships.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com