
Five Star Bancorp (FSBC) Posts Stronger Q3 Earnings, Is It Still A Bargain?
Five Star Bancorp (FSBC) has reported third quarter 2026 results, with net interest income of US$50.93 million and net income of US$21.91 million, both above the prior year’s figures.
The latest move comes after a bumpy few months for Five Star Bancorp. The 7 day share price return of 1.88% and 30 day gain of 6.02% point to improving near term momentum, even though the 90 day share price return declined 4.81%.
Scan beyond Five Star Bancorp to see how other banks with solid earnings trends line up in our hand picked 29 high quality undervalued stocks list.
Five Star Bancorp now trades meaningfully below both analyst targets and one intrinsic value estimate, despite the recent rebound. Does that gap still look like a genuine discount once you compare the price with those ranges?
Most Popular Narrative: 13% Undervalued
Five Star Bancorp is trading at $44.92 against a widely followed narrative fair value of $51.80, so the story currently prices in a discount that investors need to judge for themselves.
The main thing that has to go right is that Five Star Bancorp continues to shift its funding mix toward long-tenured core deposits while managing higher people and expansion costs so that growth remains supported without undue strain on capital.
The current valuation and this narrative’s view that Five Star Bancorp is undervalued together imply that the share price does not fully reflect its core deposit progress, asset-sensitive balance sheet and conservative credit outcomes.
See why 1 investors see Five Star Bancorp as 13% undervalued.
Result: Fair Value of $51.80 (UNDERVALUED)
Still, the narrative around Five Star Bancorp can be tested if higher hiring and expansion costs drag on efficiency, or if rapid loan growth pressures capital and prompts further equity raises.
Find out about the key risks to this Five Star Bancorp narrative.
Another View: What P/E Says About Five Star Bancorp
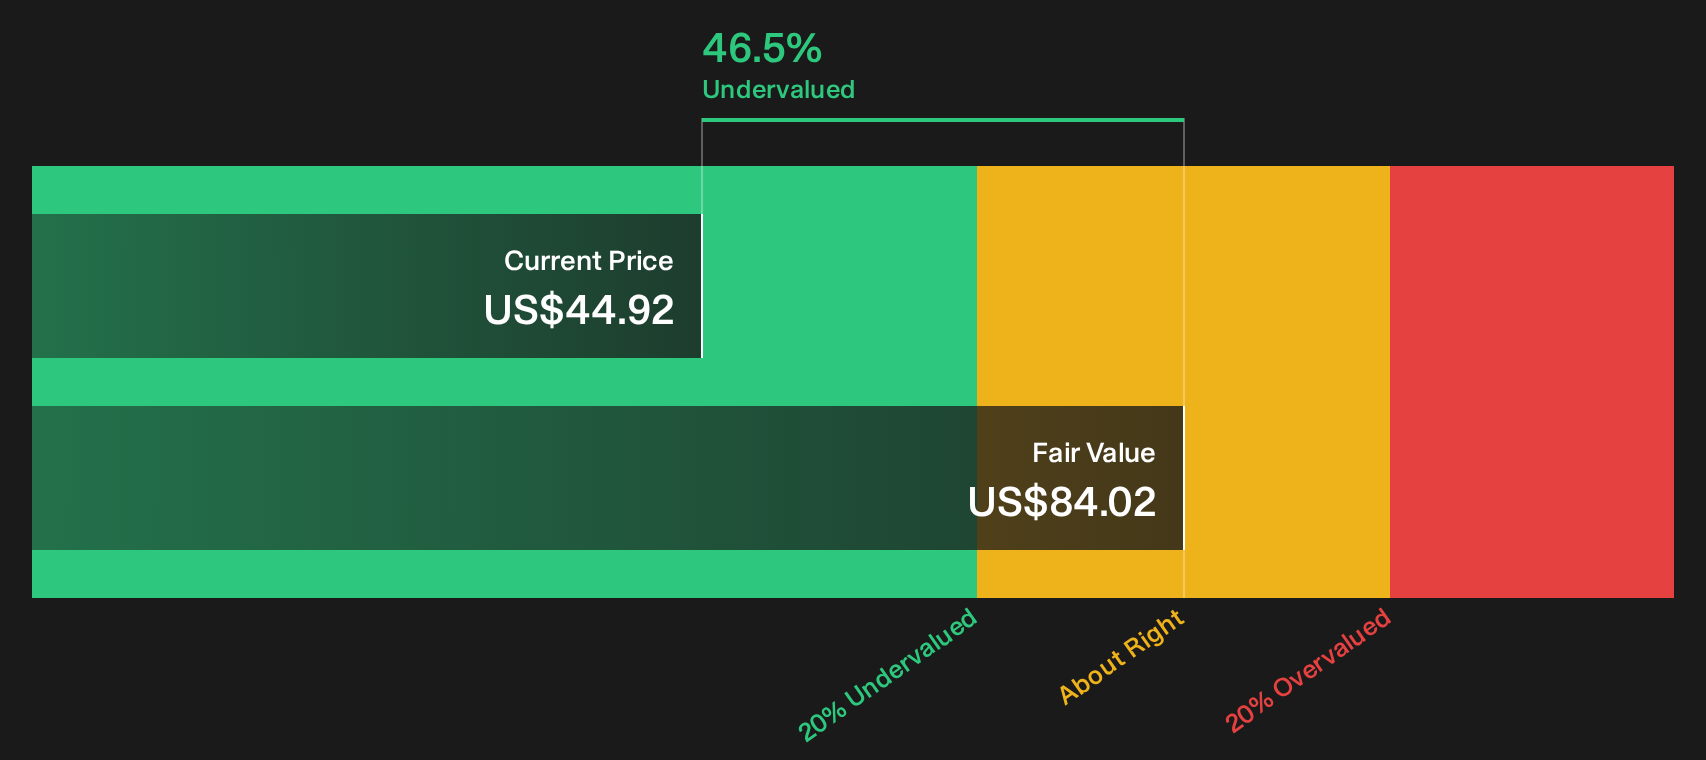
The SWS DCF workup points to Five Star Bancorp trading at a large discount to an estimated fair value of $84.02. The earnings multiple tells a different story. At 14.2x P/E, FSBC trades above both peers at 10.7x and the broader US Banks group at 11.4x, while the fair ratio sits at 12.3x. That gap suggests investors need to weigh a possible valuation cushion from cash flow against richer pricing on earnings.
Before leaning on any one framework, it is worth seeing how the SWS DCF model uses those cash flow assumptions to arrive at that $84.02 figure and where your own expectations differ from it. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Five Star Bancorp is mixed enough that it pays to look under the hood yourself and move before the crowd reacts. To see what current optimists are focusing on, review the 3 key rewards.
Looking for more investment ideas beyond Five Star Bancorp?
If you stop at Five Star Bancorp, you risk missing other setups where quality, income, or mispricing could matter just as much to your portfolio.
- Target potential mispriced opportunities by scanning our carefully filtered 29 high quality undervalued stocks that combine stronger fundamentals with more appealing entry points.
- Strengthen your income stream by reviewing a curated 5 dividend fortresses that focuses on higher yields with an emphasis on staying power.
- Prioritize resilience by checking a 30 resilient stocks with low risk scores that highlights businesses with more robust financial profiles and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com