
TFI International (TSX:TFII) Stock Price Faces Q3 Earnings Reality
TFI International just closed at CA$130.05 after Q3 2026 results that put earnings power in sharper focus than the recent slide in the share price. The stock has dropped about 31% over the past three months, yet the latest quarter delivered Basic EPS of US$1.29 on revenue of US$2,232.2m, with trucking and logistics doing much of the heavy lifting.
In the short term, the tape looks tired. Over a multi year lens, investors are weighing that earnings print and a 4.3% trailing net margin against forecasts that call for much faster profit growth ahead.
Like the earnings power at TFI International but uneasy about the recent 31% slide and margin pressure risk? Check out our list of solid balance sheet and fundamentals stocks (6 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,232.2m vs. US$1,968.7m (up about 13.4%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$105.7m vs. US$84.7m (up about 24.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.29 vs. US$1.03 (up about 25.7%)
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 4.3% vs. 4.1% (modest margin expansion on a trailing basis)
Prefer clean charts over reading dense earnings tables and margin figures for TFI International? Get a full visual breakdown of its business and valuation story in our company report for TFI International.
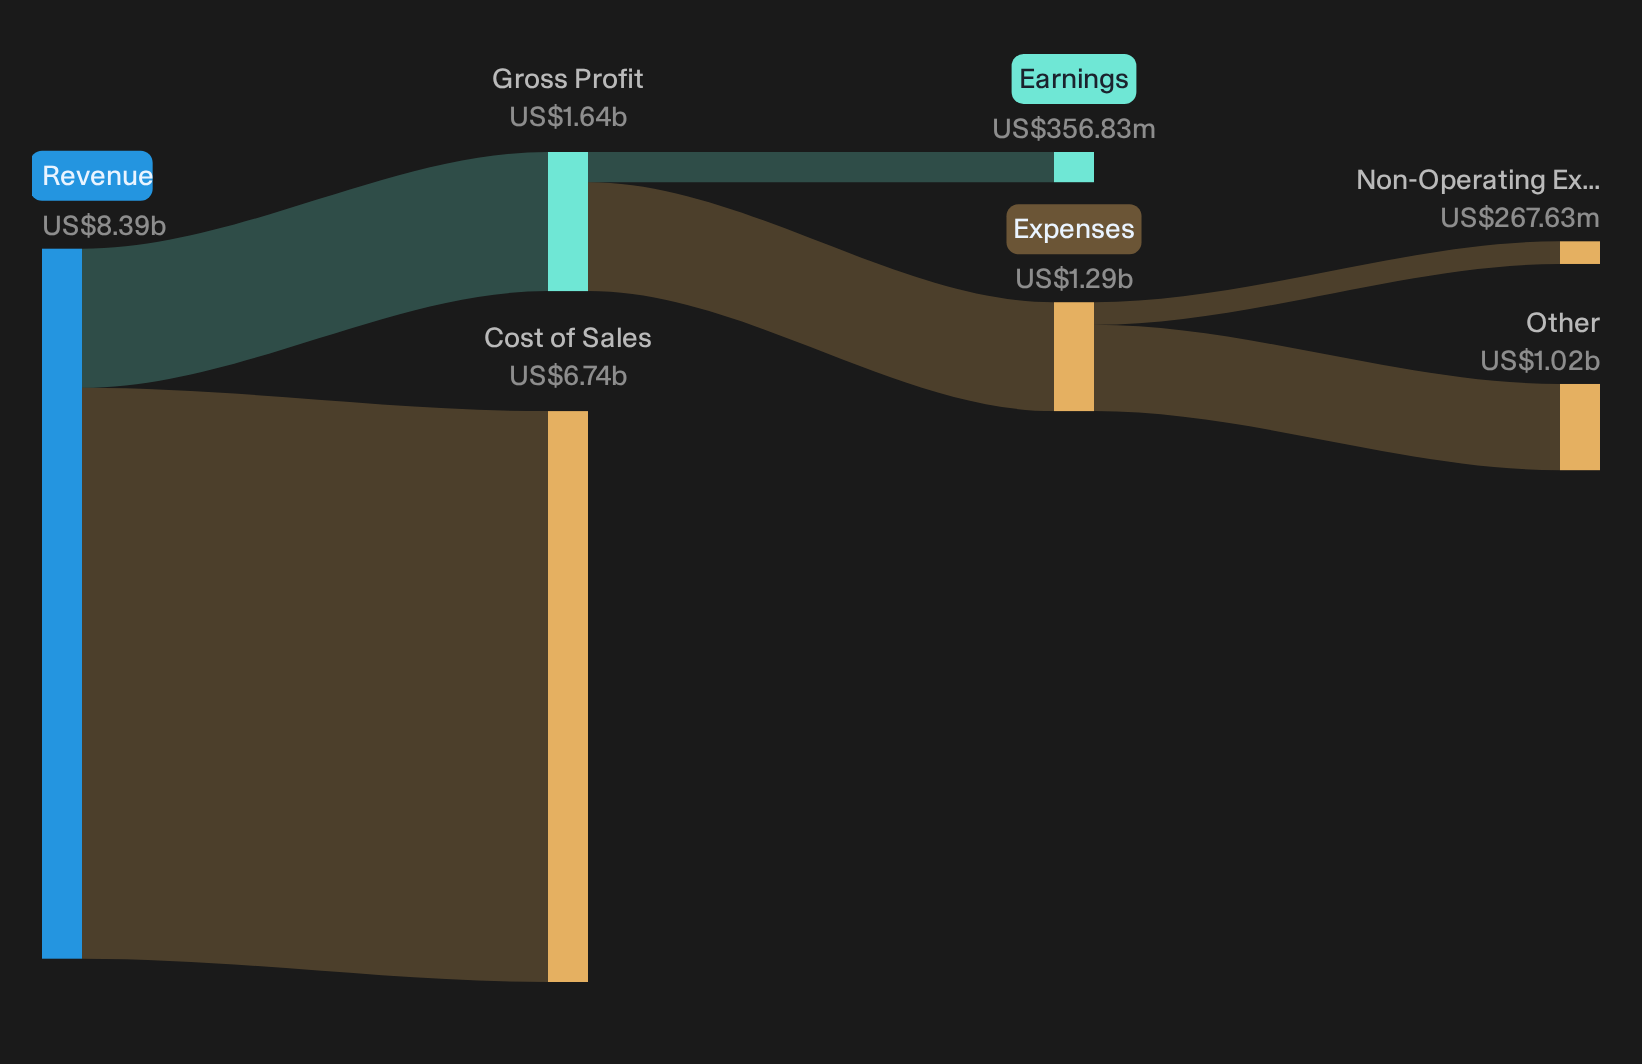
TFI International: Bullish Execution Claims Meet Q3 Reality
The upbeat story depends on TFI International lifting returns through a sharper industrial mix, stronger U.S. LTL pricing and tight capital use.
"The main requirement is that TFI International executes on its U.S. LTL turnaround and service improvement plan so that pricing, mix, and claims costs move closer to its Canadian operations and large peers, while truckload and logistics maintain current margin progress."
Truckload and Logistics just delivered clear milestones. Operating income in truckload nearly doubled, adjusted operating ratio improved by about 560 bps and logistics margin moved above 11%. U.S. LTL is lagging badly with an estimated 97% operating ratio, which is far from the Canadian operation at under 75%. As a result, the turnaround thesis is only partially reflected in current numbers.
The price and this Narrative do not agree. → Uncover what this Narrative says TFI International is actually worth.
TFI International Bear Case: LTL Drag Still Bites
Bears argue that U.S. LTL weakness can offset truckload and logistics strength at TFI International and cap profit progress.
"Even though U.S. LTL is in an operational and commercial turnaround with new pricing tools and AI analytics, current shipment growth combined with yield pressure, weaker density, higher claims and repeated unexpected issues since the UPS Freight acquisition signal that the path to an 80 to 85% operating ratio remains uncertain and could weigh on segment net margins and earnings."
Q3 results keep that concern alive. U.S. LTL still sits near a 97% operating ratio while Canadian LTL runs below 75%. Truckload and Logistics produced strong operating income, yet consolidated margin of 9.7% reflects how far the U.S. network must improve for the bearish thesis to ease.
Hunt For Mispriced Earnings Power
TFI International just reminded investors that reported results and recent share performance do not always move in the same direction. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 21% below our estimate - expands aerospace electronics capacity and adds aftermarket exposure through a recent acquisition targeting recurring aircraft systems work.
- Company 2 - 35% below our estimate - folds in acquired design consultancies and uses shared delivery hubs so large infrastructure and water programs access the same higher margin expertise.
- Company 3 - 46% below our estimate - uses premium mall expansion and a faster online experience so fashion lines refresh quickly and full price sell through improves.
Three companies from the same screener. Open every one of the 3 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com