
Teck Resources (TSX:TECK.B) Stock Can Q3 Earnings Sustain Margin Gains?
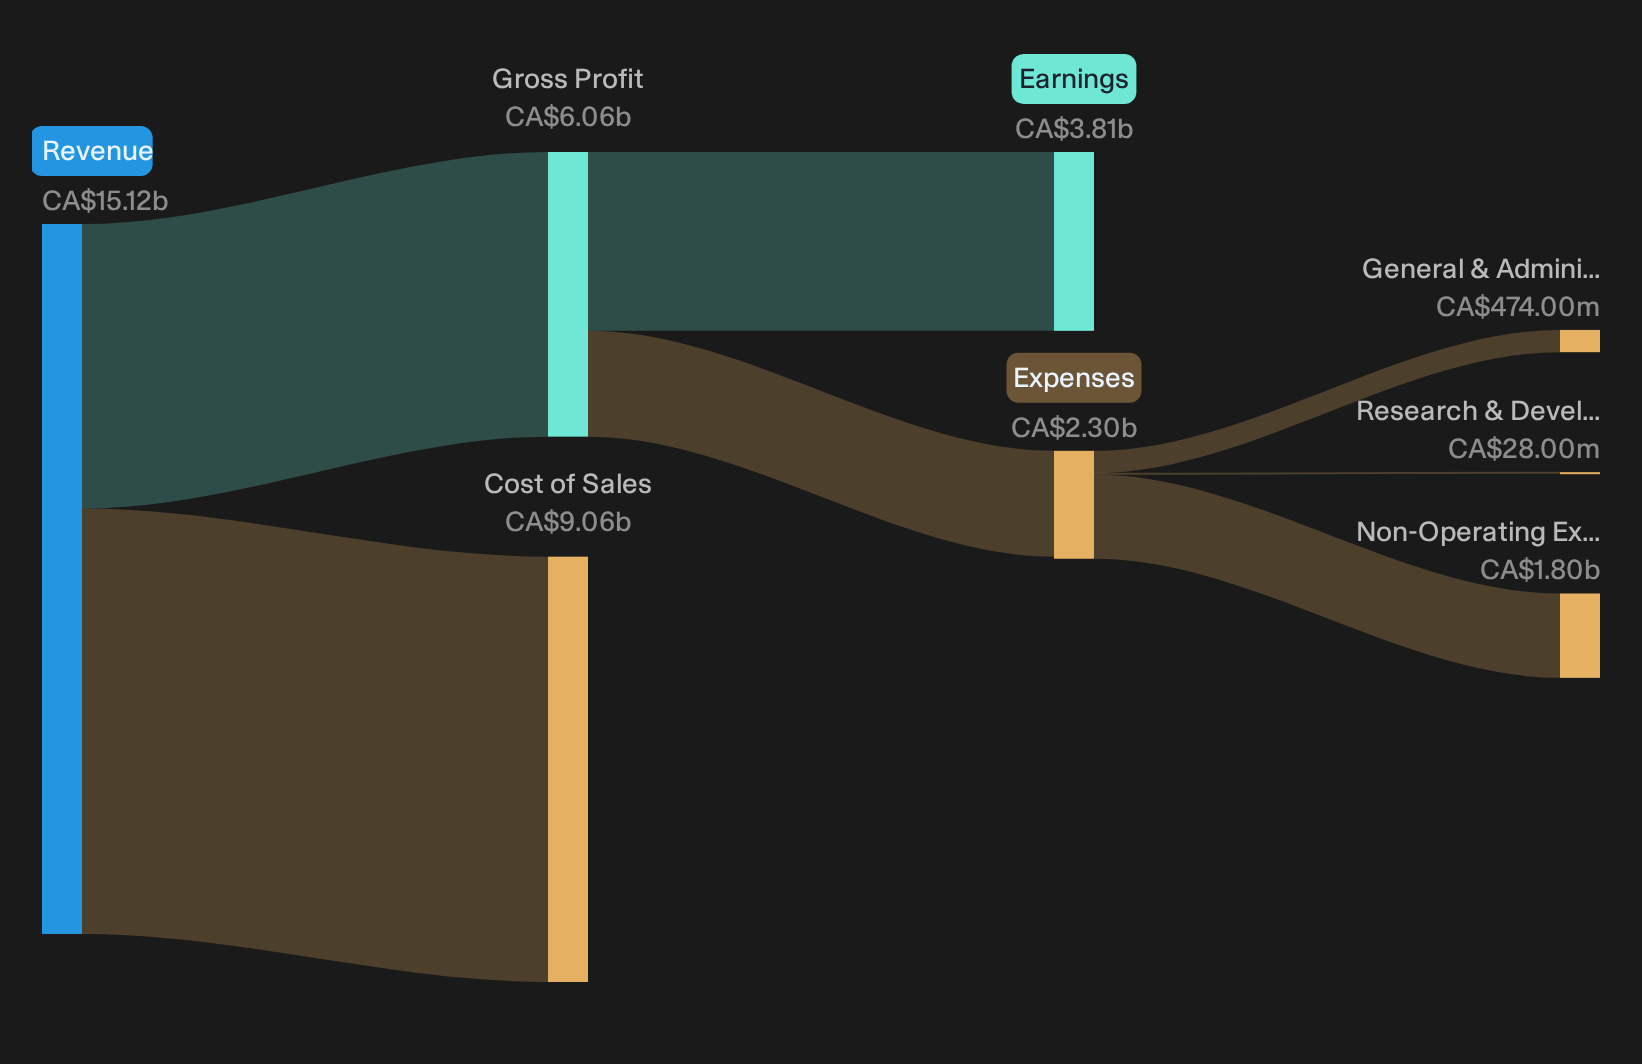
Teck Resources just printed a muscular Q3 2026, yet the stock came into the release looking cautious, down roughly 10% over the past month and barely positive over 90 days. The miner posted CA$3.24 in basic earnings per share on CA$4.5b in revenue for the quarter, with adjusted EBITDA reaching CA$2.3b and margins far stronger than a year ago. That mix of hesitant recent share performance and punchy profitability is exactly where the expectation gap opens up for Teck Resources.
Love Teck Resources' strong Q3 margins but uneasy about the recent share pullback? See how it stacks up against peers with sturdier profitability profiles in our list of solid balance sheet and fundamentals stocks (6 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): CA$4,517m vs. CA$3,385m (up about 33%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): CA$1,592m vs. CA$281m (up more than 5x)
- Basic EPS (Q3 2026 vs. Q3 2025): CA$3.24 vs. CA$0.58 (very large increase, more than 5x)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 51% vs. 35% (strong margin expansion)
Teck tightened zinc cost guidance far more than copper this quarter. Ask Charlie what made Teck slash zinc cost guidance so sharply.
Evaluating Teck Resources’ Copper Upside Claims
The bullish case rests on Teck Resources turning today’s copper projects and Trail reboot into a meaningfully richer earnings mix over time.
"Bullish analysts expect Teck Resources to turn its copper focused Anglo Teck merger, brownfield mine investments and Trail critical minerals expansion into a larger and more cash generative portfolio over time."
Q3 moves that idea from theory toward evidence. Copper net cash unit costs fell, guidance for both copper and zinc costs tightened, and adjusted EBITDA margins reached 51%. Trail’s impairment reversal and higher long term pricing assumptions back the critical minerals angle. Severe weather and the Highland Valley strike show the portfolio is not yet running at full, smooth capacity, yet the cost and margin profile still improved.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Teck Resources: Strong Quarter, Project Risks Still Visible
Bearish analysts worry that Teck Resources will struggle to offset heavy copper capex just as zinc support fades.
"Red Dog’s zinc production is forecast to fall to as low as 410,000 tonnes in 2026 as the mine approaches the end of its current life. Even with higher value byproducts, this shift to lower grades and rising unit costs may erode segment margins and reduce the cash that can be recycled into copper projects."
Q3 results partially cut against that fear. Zinc production at Red Dog moved lower as expected, yet Teck tightened 2026 zinc cost guidance sharply and kept production guidance intact. Trail’s impairment reversal and stronger refined zinc output offset some Red Dog pressure. Execution risk has not disappeared though. The Highland Valley strike, severe weather at Quebrada Blanca and peak capex plans confirm that operational or schedule slippage could still hit future free cash generation even after this strong print.
Hunt For Quiet Fundamental Dislocations
Teck Resources just showed how a strong earnings print can coincide with a cautious share move for some time. The real opportunity sits in finding stocks that could be undervalued before the market closes that gap.
- Company 1 - 46% below our estimate - builds fashion labels, gaining pricing power as shoppers accept fewer markdowns and upgraded products.
- Company 2 - 21% below our estimate - turns an aerospace and defense backlog and a new avionics acquisition into higher margin aftermarket electronics.
- Company 3 - 35% below our estimate - wins recurring infrastructure and water design work that integrates acquired specialists into large multi year programs.
That is three of the list. See the full list of 3 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com