
EMCOR Group (EME) Q3 Results Lift Profit And Backlog Questions
EMCOR Group came into this earnings print with its stock cooling off, down about 10% over the past month even after strong longer term gains. Q3 2026 results hit with a different message. Revenue reached roughly US$5.54b and basic earnings per share landed at US$9.06, while operating cash flow for the quarter approached US$800m. The share price still slipped about 1.4% on the day, which indicates sentiment hesitated even as the core construction and services engine generated substantial profit and cash.
Impressed by EMCOR Group’s strong revenue and cash generation but wary of a stock that still slipped on the print? Compare this setup with a curated list of companies that pair solid fundamentals with resilient balance sheets in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
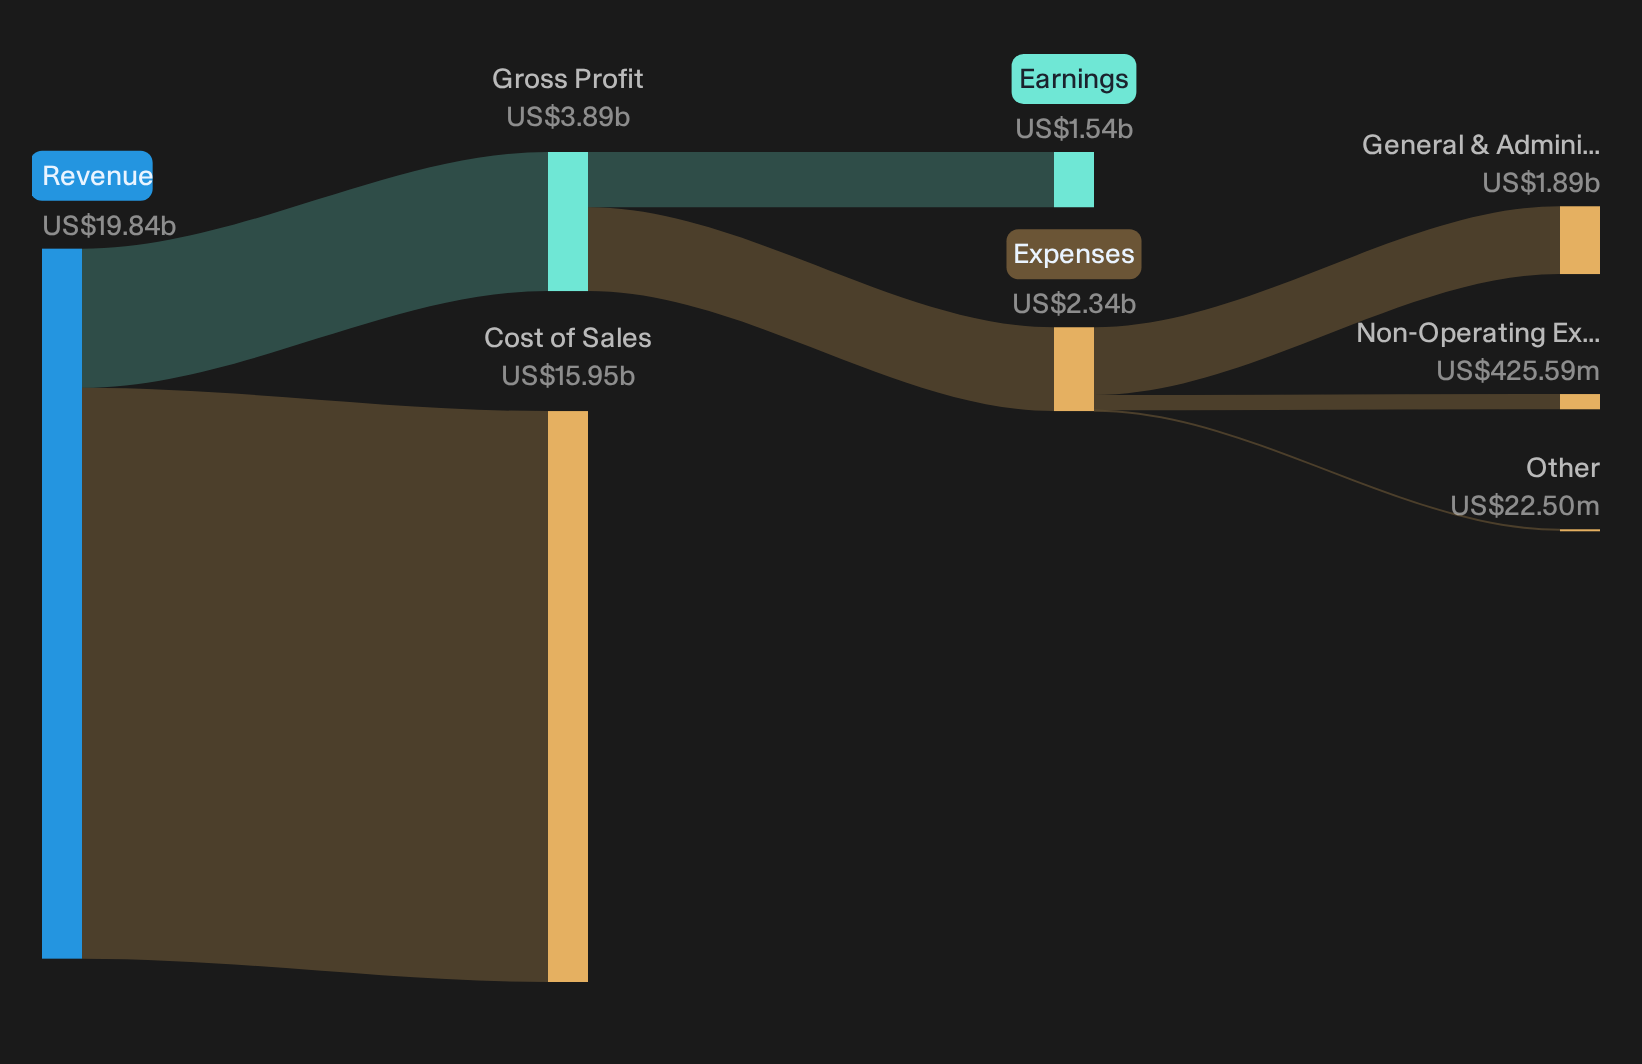
- Revenue (Q3 2026 vs Q3 2025): US$5,541.52m vs. US$4,301.53m (up about 28.8%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$399.93m vs. US$295.37m (up about 35.4%)
- Basic EPS (Q3 2026 vs Q3 2025): US$9.06 vs. US$6.59 (up about 37.4%)
- Gross Margin (Q3 2026 vs Q3 2025): 20.0% vs. 19.4% (improved by about 60 basis points)
EMCOR’s data center orders have more than doubled in a year. Ask Charlie what’s driving EMCOR’s massive data center backlog.
EMCOR Bull Case Hurdle: Bigger Jobs, Stronger Proof
For the bullish view on EMCOR Group to hold, management needs to keep turning AI heavy contracts into tangible project scale, visibility and execution quality.
"The main thing that has to go right is that EMCOR Group continues to win and execute larger, longer duration projects across sectors like data centers, institutional work, and industrial services while maintaining the cash generation and contract discipline shown in recent guidance and results."
Q3 points firmly in that direction. Data center remaining performance obligations reached US$8.74b and overall RPO climbed to US$18.57b. Construction revenue hit records with construction margins at roughly 12.6%. Cash generation was strong, with about US$797m in quarterly operating cash flow and full year guidance for both revenue and EPS moving higher.
One Narrative disagrees with today's price. → See where this Narrative says EMCOR Group should trade.
EMCOR Bear Case: Margin Fears Confront Record Backlog
Bearish investors worry EMCOR Group is trading volume for profitability as contract mix tilts toward lower markup roles.
"While record Remaining Performance Obligations of US$17.14b include large contributions from data centers and institutional projects, a higher mix of lower markup roles where EMCOR Group acts as construction manager or prime contractor suggests more of this backlog may convert into revenue with weaker gross margin."
The latest quarter complicates that story. Construction operating margin sat near 12.6% with gross margin at 20.0%, both higher than a year ago, even as data center RPO climbed to US$8.74b and total RPO reached US$18.57b. Record backlog has not yet translated into margin slippage.
Hunt Mispriced Earnings Stories Now
EMCOR Group just showed how strong results and a cautious share reaction can coexist. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - turn large scale AI infrastructure demand into long term agreements across multi cloud systems.
- Company 2 - 37% below our estimate - tighten carrier screening and use AI tools so complex freight moves toward safer, more productive loads.
- Company 3 - 30% below our estimate - embed AI copilots into daily workflows so existing software users adopt deeper, recurring usage patterns.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com