
Carrier Global (CARR) Q3 Results Deepen Loss Debate For Stock
Carrier Global just released its Q3 2026 scorecard and the headline is blunt. A reported net loss of US$2.6b and basic earnings per share of US$3.16 in the red coincided with a stock that fell only 3.6% today to about US$53.57. That is a sharp move for a single session, yet it still feels small next to the size of the hit on the income statement.
Traders clearly focused on the write-down and income shock. The deeper question is whether that one punch tells the whole story of Carrier’s quarter or just the loudest part of it.
Love the chance to buy Carrier Global after a sharp one day selloff, but worried about big write downs and earnings shocks like this one? Screen for companies with sturdier balance sheets and cleaner income statements in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
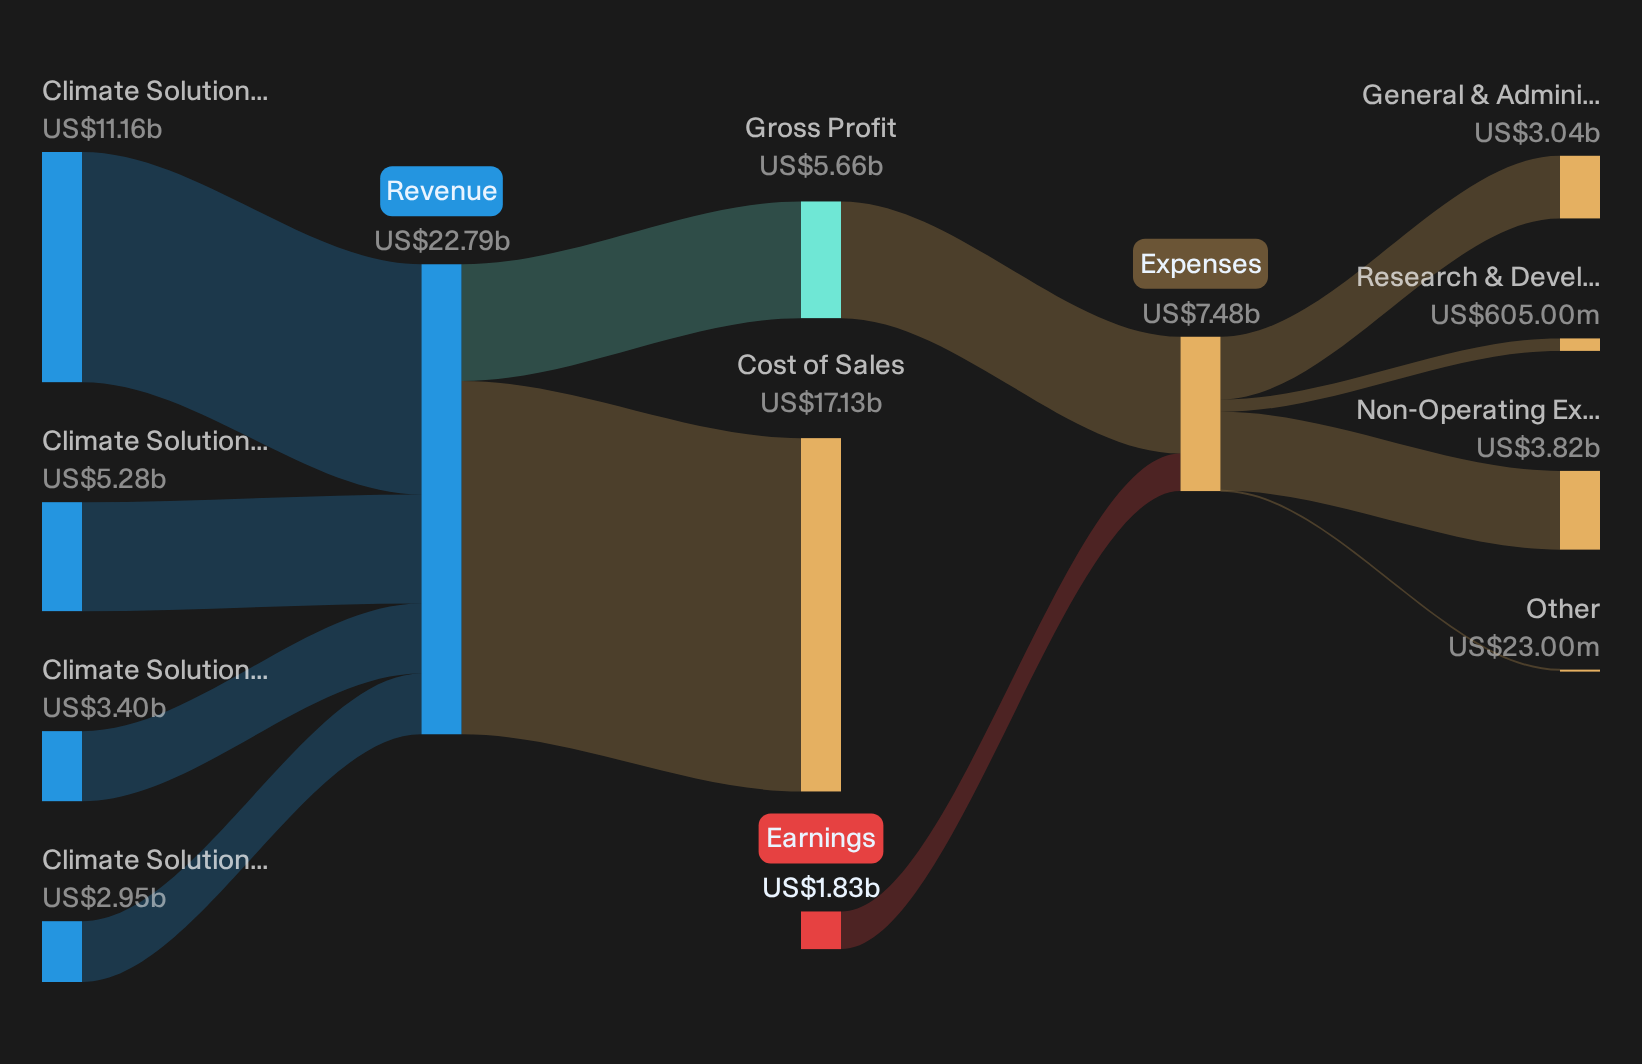
- Revenue (Q3 2026 vs. Q3 2025): US$6,263m vs. US$5,579m (top line higher year on year).
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$2,593m vs. profit of US$407m (swing from profit to sizeable loss).
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$3.16 per share vs. earnings of US$0.48 per share (sharp deterioration in per share result).
- Free Cash Flow (Q3 2026 vs. Q3 2025): about US$700m in Q3 2026 vs. a lower level a year ago based on management commentary (cash generation stronger than the income statement suggests).
Prefer clean charts over another wall of earnings tables and one off charges? See Carrier Global’s full financial picture, including how the new loss compares with the balance sheet and cash generation, in our company report for Carrier Global.
Evaluating Carrier Global’s Capacity And Services Milestones
The bullish story hinges on Carrier Global turning big capital projects and digital plans into durable earnings power.
"Carrier Global’s more than US$600 million investment in the Fort Worth advanced manufacturing and engineering center, which is scheduled to begin operations in 2027 and includes new commercial chiller capacity for data centers, creates room for higher equipment revenue and follow on service income beyond what the current backlog and short term guidance capture."
Q3 results move this from theory toward execution. Data center orders grew very sharply, full year data center sales are on track for US$2b, and backlog reached more than US$8.5b. That record order book, together with a hyperscaler agreement above US$3b with minimum volume commitments, is direct evidence that planned Fort Worth capacity aligns with visible demand rather than a build it and hope scenario.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Carrier Global: Margin Fears Meet Mixed Evidence
Bearish analysts worry that Carrier Global’s factory under absorption and cost issues will keep profitability unstable even as sales climb.
"Despite aggressive structural cost actions, including about 3,000 indirect headcount reductions and targeted use of AI tools, the company is still carrying higher inventories in CSA Residential and is accepting under absorption in factories. This can keep segment operating margins volatile until volumes normalize."
Q3 adjusted operating margin expanded 260 bps with help from IEEPA refunds, yet management cut CSA segment margin guidance to about 19% and flagged roughly US$800m of input cost headwinds. Strong data center and residential volumes are easing the volume side of that concern, but pricing slippage and tariffs show the margin volatility risk is still present.
Hunt For Mispriced Earnings Power
Carrier Global just reminded investors that headline earnings surprises and price reactions do not always align. The real opportunity is in stocks that may be undervalued before the market reassesses them.
- Company 1 - 30% below our estimate - ties a dedicated AI layer into productivity, developer and security tools used by existing customers.
- Company 2 - 35% below our estimate - sells high end accelerators and racks that are widely selected for demanding AI data center build outs.
- Company 3 - 42% below our estimate - shifts toward complete AI focused server and storage solutions that bundle hardware, software and services into larger integrated orders.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com