
Merit Medical Systems (MMSI) Stock Price Drops After Strong Q3 Earnings
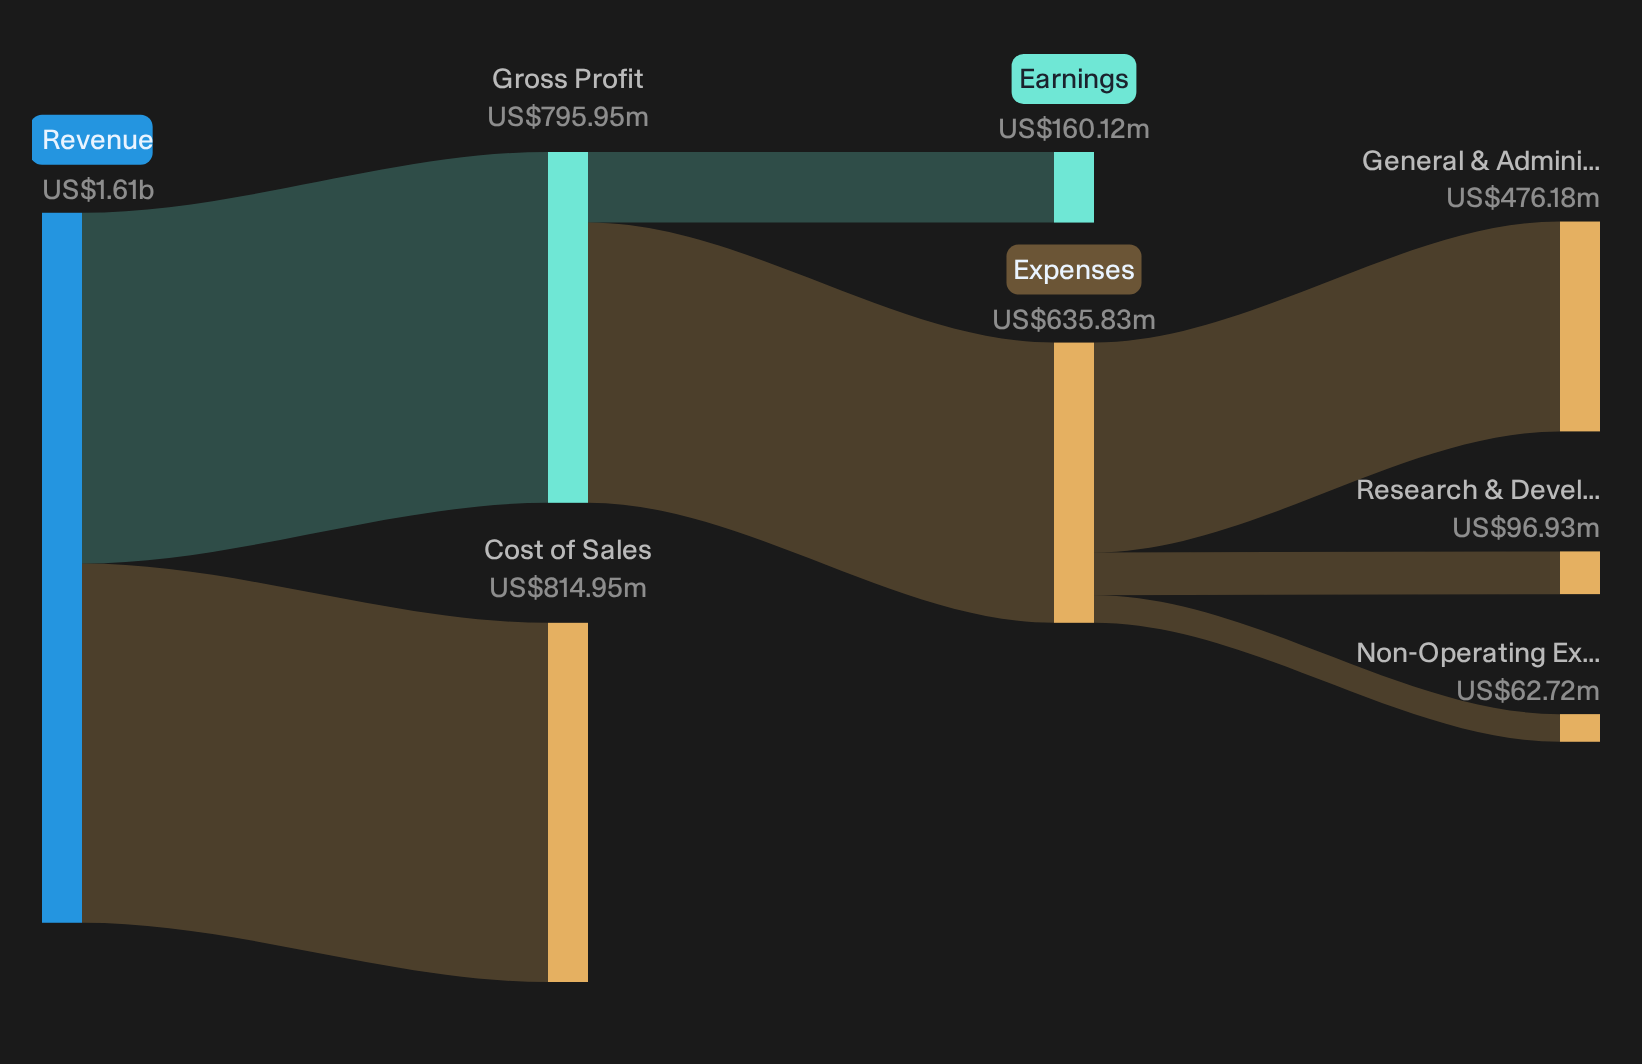
Merit Medical Systems has spent years earning a reputation as a steady compounder in medical devices. Q3 2026 results kept that earnings machine intact, yet the stock dropped about 8% to close near US$86 after the release. That disconnect is striking. Revenue reached about US$416 million and basic earnings per share landed around US$0.71, while non GAAP operating margin held above 21%. For a business built on procedure volumes and recurring hospital demand, the share price reaction appears to reflect shaken expectations rather than a visible crack in the quarter just reported.
Love Merit Medical Systems' resilient margins but uneasy about the sudden 8% share price drop on Q3 earnings day? Look at the 30 resilient stocks with low risk scores as a reference point for stocks where fundamentals and risk scores line up more cleanly with recent trading action.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$416.2m vs. US$384.2m (up about 8%)
- Net Income Excl. Extra Items (Q3 2026 vs. Q3 2025): US$42.3m vs. US$27.8m (up about 52%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.71 vs. US$0.47 (up about 51%)
- Non GAAP Operating Margin (Q3 2026 vs. Q3 2025): about 21.3% vs. about 19.7% (up about 1.6 percentage points)
Merit Medical beat expectations and raised 2026 guidance again. Ask Charlie what Merit Medical’s new guidance really signals.
Evaluating Merit Medical’s Bullish Execution Milestones
The optimistic storyline around Merit Medical Systems hangs on higher margin platforms doing more of the heavy lifting over time.
"Merit’s focus on higher margin platforms such as oncology, endoscopy, cardiac therapies and vascular intervention, supported by tuck in acquisitions like Biolife, C2 CryoBalloon and View Point that have strong gross margin profiles, is designed to shift the mix toward therapeutic products and support non GAAP gross margin and operating margin improvement over time."
Q3 shows some numbers supporting that narrative. Therapeutic products grew organically faster than foundational lines, and oncology increased about 16%. Non GAAP operating margin reached about 21.3%, and full year guidance implies a similar level. Even with gross margin pressure from manufacturing and freight, cost discipline turned mix and scale into higher earnings and stronger free cash flow.
One Narrative disagrees with today's price. → See where this Narrative says Merit Medical Systems should trade.
Merit Medical Bear Risks Versus Q3 Reality
One of the key worries around Merit Medical Systems is that acquisition complexity and EPS dilution could outweigh the upside from a larger oncology and biopsy footprint.
"Although the acquisition of View Point Medical expands the breast and soft tissue localization offering and triples the addressable biopsy procedure opportunity, integration risk and the initial non-GAAP EPS dilution of around $0.05 in 2026 could limit how much of that larger procedure pool converts into revenue and earnings growth."
Q3 oncology revenue rose about 16% and OneMark integration is progressing, which directly challenges the fear of early execution stumbles. The raised 2026 non GAAP EPS range, despite that US$0.05 dilution, indicates the expected hit to earnings is currently contained rather than worsening.
Hunt Mispriced Earnings Stories Now
Merit Medical Systems just showed how expectations and price can briefly pull apart. The real opportunity is spotting companies that could be undervalued before the market closes that gap.
- Company 1 - 42% below our estimate - sell modular data center systems that buyers prefer as complete AI ready infrastructure building blocks.
- Company 2 - 38% below our estimate - expand a device trade in network that policy support and younger consumers push into everyday recycling habits.
- Company 3 - 37% below our estimate - use an asset light freight model where new AI tools tighten carrier screening and claims control.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com