
Howmet Aerospace (HWM) Stock Price Slides As Q3 Earnings Fuel Debate
Howmet Aerospace just dropped its Q3 2026 scorecard and the stock reacted with a jolt. Shares closed at US$199.30, down 3.2% on the day, even though the company posted US$2.7b in revenue and US$1.46 in earnings per share for the quarter. The tension is clear. Traders focused on the immediate price move while the underlying story is a powerful profitability surge, with net income at US$567m and trailing net margins at 21.1%. The strongest positive trend is earnings strength, and sentiment is struggling to keep up.
Impressed by Howmet Aerospace’s strong margins but uneasy about the share price drop on the earnings print? Check out the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,703m vs. US$2,089m (up 29.4%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$567m vs. US$384m (up 47.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.42 vs. US$0.95 (up 49.6%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 21.1% vs. 18.2% (margin improved by 2.9 percentage points)
Earnings paint a strong picture for Howmet Aerospace, but investors who care about what they are actually paying for the business usually focus on the cash moving through the system instead. Looking at Howmet Aerospace's cash flows alone, the stock could be a narrow 10% undervalued.
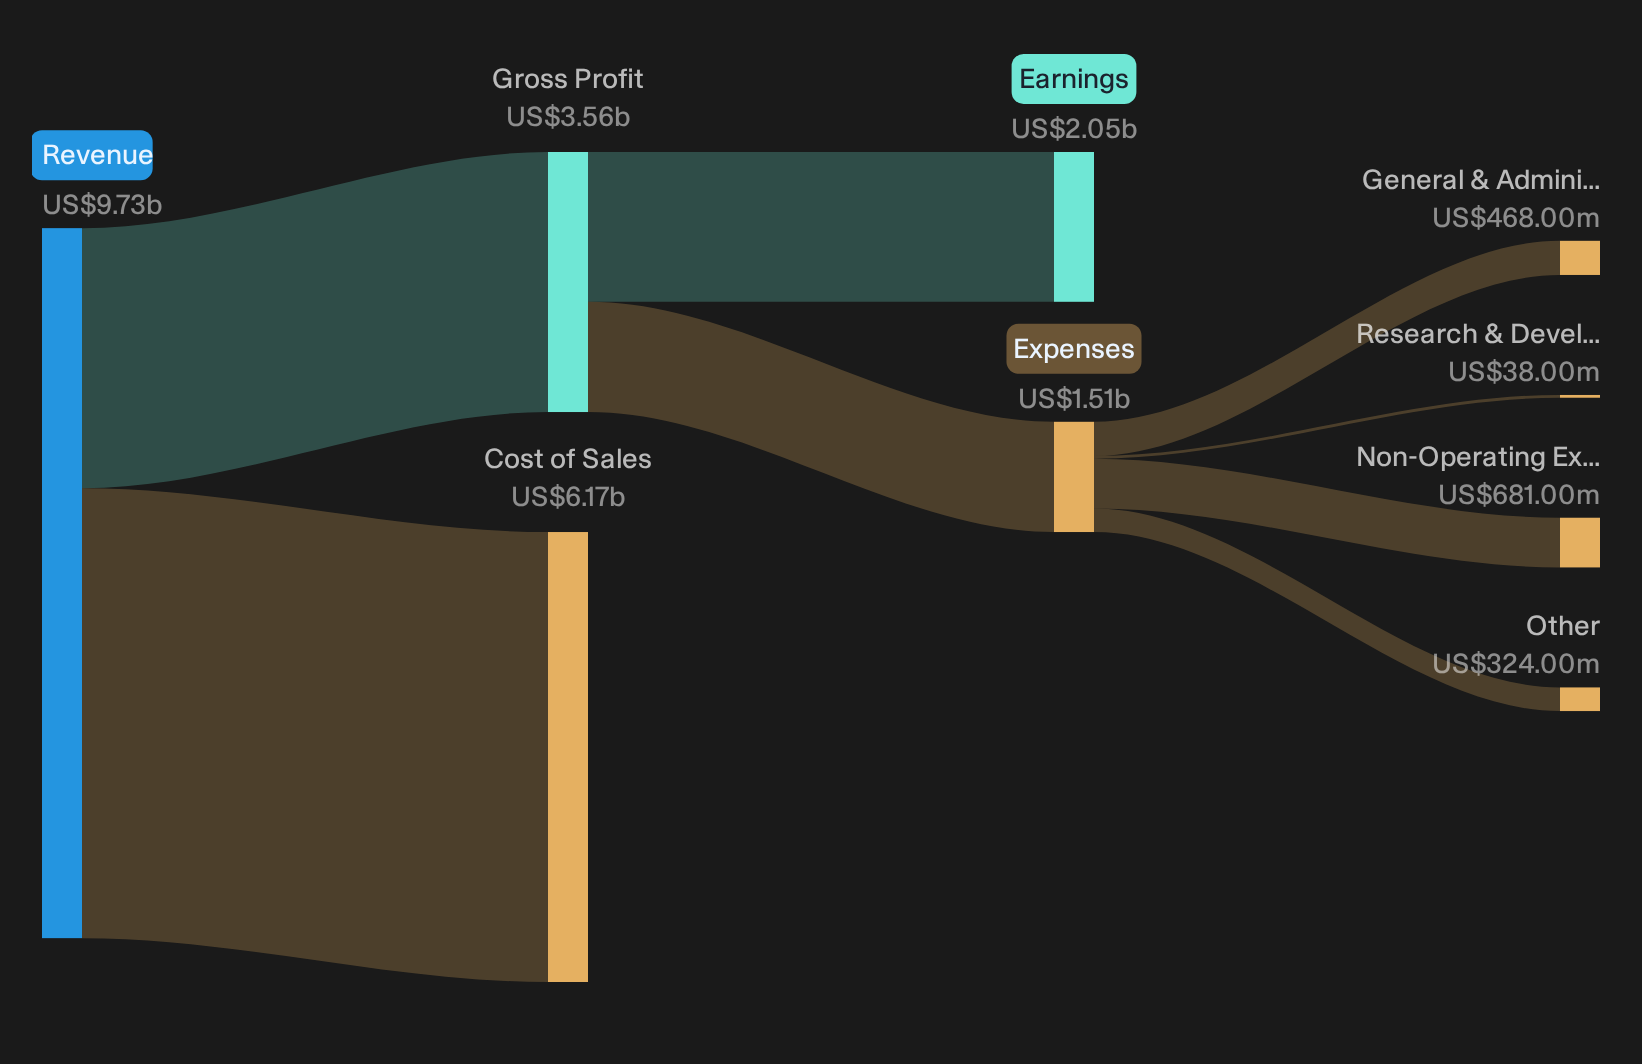
Evaluating Howmet’s Margin And Cash Flow Ambitions
The bullish script assumes Howmet Aerospace can turn heavy investment into sustained profitability and strong cash generation.
"The main requirement for the bullish thesis is that Howmet Aerospace continues to convert strong demand in engines, industrial gas turbines and defense into sustained high margins and free cash flow, while executing its elevated capex and integrating its fastener acquisitions."
Q3 numbers move that idea from theory toward evidence. Engine Products posted a 39.1% EBITDA margin, while group EBITDA reached US$879m on US$2.7b of sales. Free cash flow of US$562m came after record quarterly capex of US$147m. Fastening Systems margins were diluted by the CAM deal, yet revenue there climbed to US$630m, which indicates that integration is occurring within a still profitable group.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Howmet Aerospace: Testing Fears On Turbine Competition
Bears argue that Howmet Aerospace could stumble if big engine customers pull more blade and vane work in house and squeeze a concentrated supplier group. That concern is real because capacity is tight and OEMs are investing.
"Although Howmet Aerospace has secured long duration contracts across industrial gas turbine customers, the shift by large clients such as GE toward in-house blade and vane casting through acquisitions introduces a credible risk that future turbine blade share and pricing could be diluted."
Q3 revenue from gas turbines rose 44% and Engine Products margins reached 39.1%, which points to share and pricing holding up so far, not eroding. The worry has not disappeared though. The stock has dropped 3.2% on the print and is down 29.4% over 90 days, which shows investors still price in execution and competition risk despite the strong turbine contribution this quarter.
Hunt For Mispriced Strength
Howmet Aerospace just showed how strong financial progress can clash with a weak share price reaction. The real opportunity could sit in stocks the market has not fully corrected yet.
- Company 1 - 37% below our estimate - builds an asset light freight network that leans into heavy haul demand using AI tools to tighten carrier vetting.
- Company 2 - 30% below our estimate - embeds AI copilots into everyday productivity software so existing customers gradually convert standard workflows into paid automation layers.
- Company 3 - 42% below our estimate - assembles modular AI server platforms that turn very large infrastructure orders into higher margin integrated data center solutions and services.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com