
Federal Signal (FSS) Stock Slips Even As Q3 Earnings Showcase Margin Strength
Federal Signal stock slipped 2.2% to US$112.67 in regular trading today, giving the impression of a market taking profits rather than cheering fresh news. That reaction sits awkwardly beside a Q3 2026 report built on one clear theme. Margins and earnings power are doing the heavy lifting.
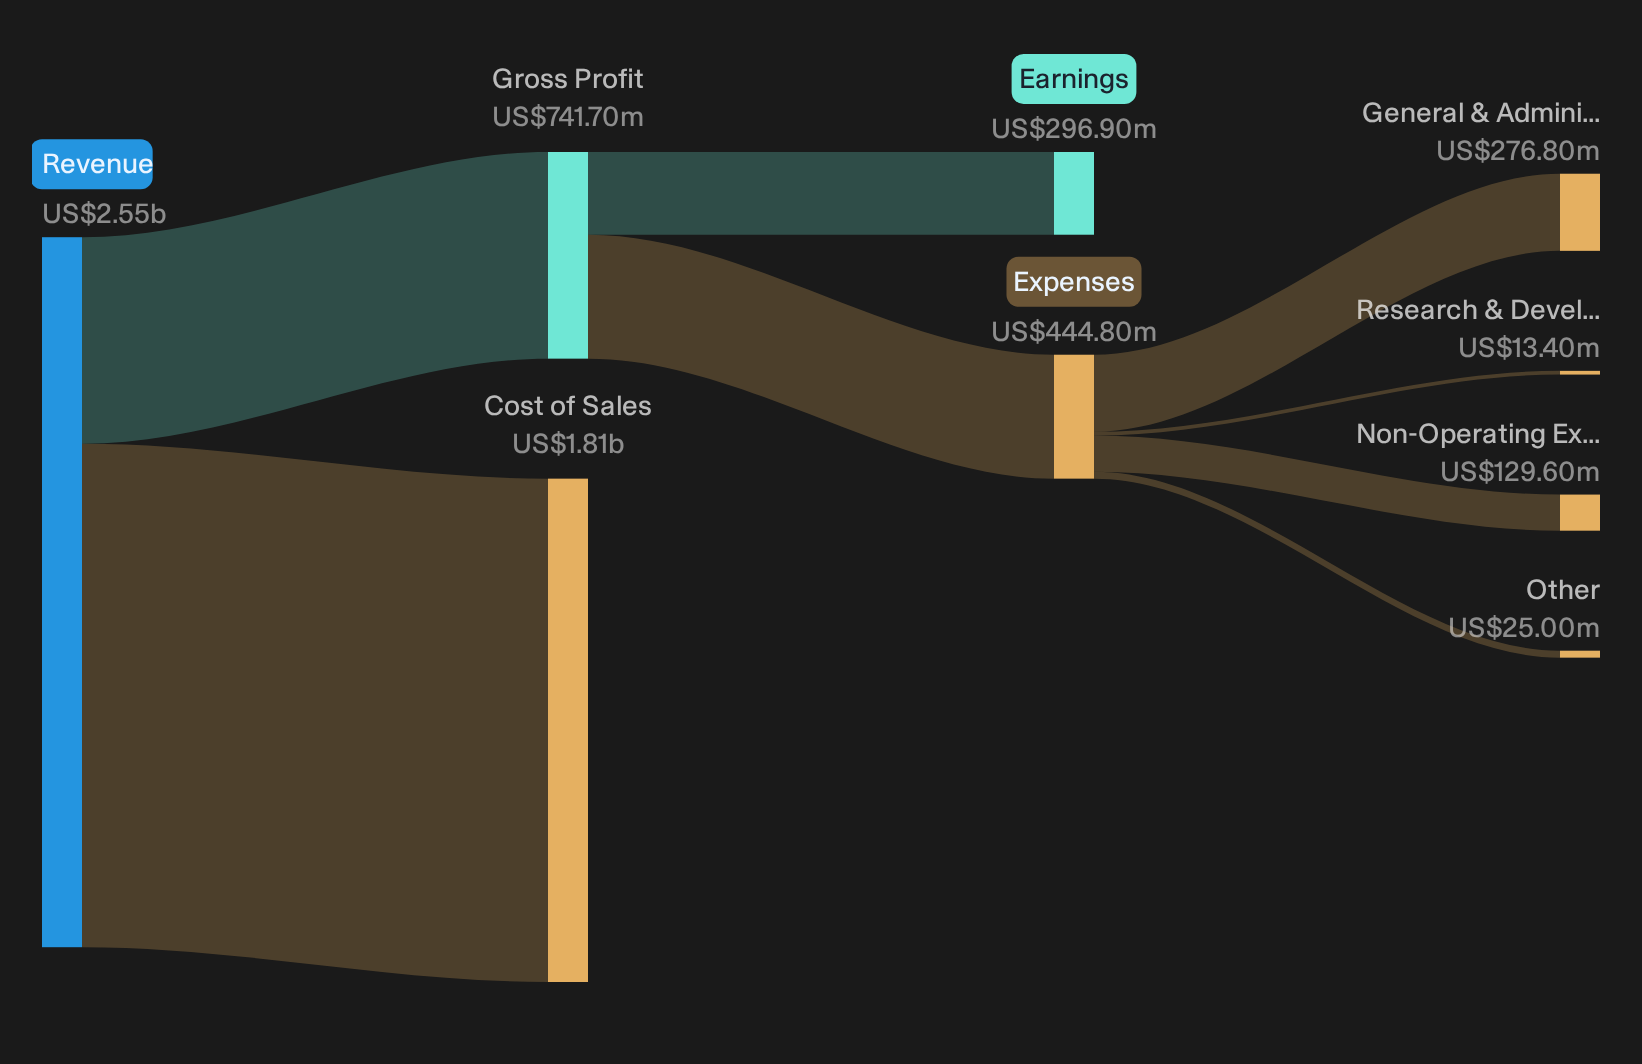
The company posted US$656m of quarterly revenue with adjusted earnings per share of US$1.34, backed by a 21.4% adjusted EBITDA margin and a US$967m backlog. For anyone thinking beyond today’s tick-by-tick move, Federal Signal now appears more like a multi-year margin story than a one-day trading event.
Like Federal Signal’s margin story but want a broader set of industrials with sturdy finances and earnings power? Scan our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$655.5m vs. US$555.0m (higher year over year)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$79.6m vs. US$68.1m (higher year over year)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.30 vs. US$1.12 (higher year over year)
- Adjusted EBITDA Margin (Q3 2026 vs Q3 2025): 21.4% vs. 20.9% (up 50 bps year over year)
Aftermarket sales jumped and now make up over a quarter of ESG revenue. Ask Charlie what makes Federal Signal’s aftermarket growth so important.
Federal Signal aftermarket thesis meets early milestones
For the bullish aftermarket story to hold, Federal Signal needs more than a one quarter spike. It needs a system that keeps pulling through higher margin work.
"Ongoing growth in Federal Signal’s aftermarket ecosystem, with aftermarket revenue already about 25% of Environmental Solutions Group revenue and rising faster than the group overall, supports a shift toward higher margin and more recurring revenue that can lift net margins and earnings."
Q3 points in the right direction. ESG aftermarket rose about 21% and reached roughly 26% of ESG revenue, while group adjusted EBITDA margin hit 21.4% with operating leverage and cash conversion both strong.
Bear case on public budgets and integration risk
The cautionary view is that public funding and deal integration could quietly chip away at the Federal Signal story even while headline results look solid.
"Federal Signal still relies on publicly funded and North American customers for a little over half of its revenue. A period of tighter public budgets or slower approvals across U.S., Canadian or European programs could weigh on orders and reduce revenue and earnings compared with what this narrative assumes."
Q3 mechanics argue against that concern for now. Orders climbed 33% to US$620m, backlog reached US$967m, and management reported New Way and MEGA ahead of internal margin plans despite Labrie delivery delays and export softness earlier in 2026.
The price and this Narrative do not agree. → Uncover what this Narrative says Federal Signal is actually worth.
Hunt Quiet Disconnects In Industrials
Federal Signal just showed how a solid quarter and a soft price move can diverge in industrials. The real opportunity is hunting stocks that could be undervalued before the market closes those gaps.
- Company 1 - 38% below our estimate - uses strong power systems demand to expand high horsepower capacity and prioritize core engine projects.
- Company 2 - 29% below our estimate - runs a growth engine that raises customer revenue per user while new markets move toward breakeven.
- Company 3 - 41% below our estimate - scales a higher margin rental platform as utilities and project owners expand long duration worksite access spending.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com