
Olin (OLN) Stock Rallies After Q3 Earnings Even As Leverage Lingers
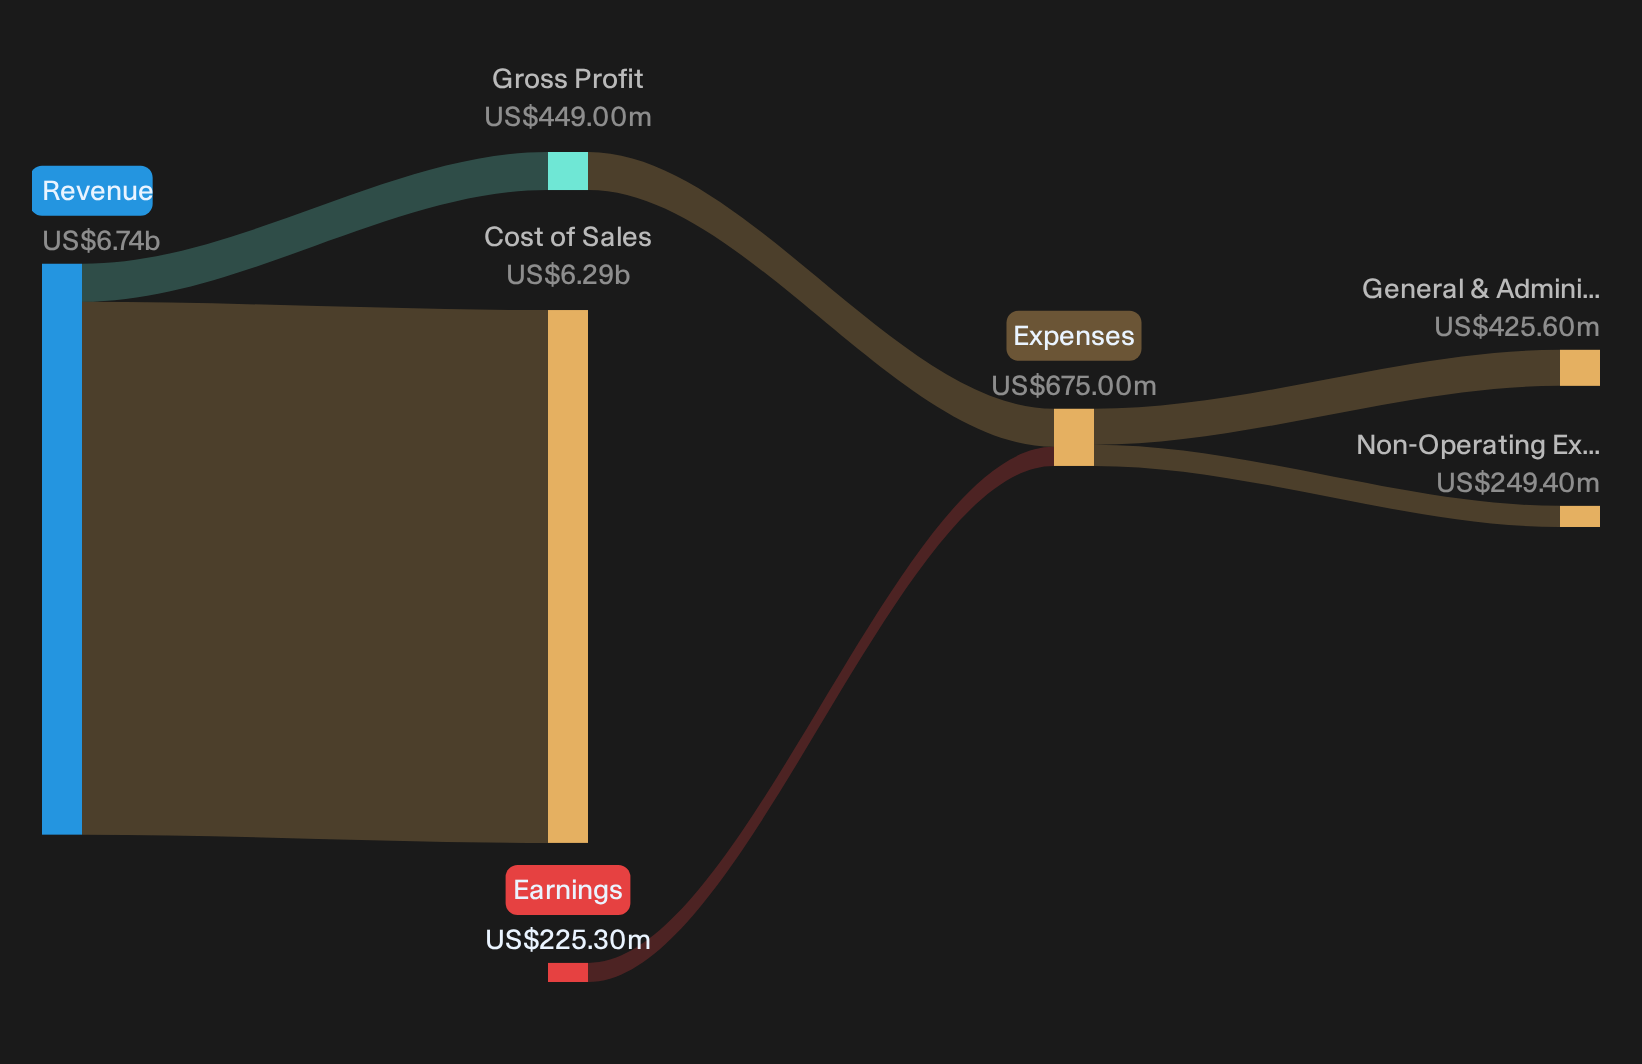
Olin stock jumped 9.6% to about US$17.59 in regular Thursday trading as investors cheered a cleaner third quarter tape. The reaction came after the chemicals producer swung back to a modest profit for Q3 2026, with basic earnings per share of US$0.13 on revenue of US$1.75b. That relief rally tells the short term story. The longer view still revolves around a business that remains loss making over the last twelve months and a balance sheet carrying higher leverage. This is where the real investment debate now sits.
Love the relief on Olin swinging back to profit but uneasy about the recent losses and higher leverage? Compare this setup to other balance sheet focused ideas with our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,747.7m vs. US$1,713.2m (steady top line with a small uplift)
- Net Income (Q3 2026 vs Q3 2025): profit of US$14.4m vs. profit of US$42.8m (profit remained positive but at a lower level)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.13 vs. US$0.37 per share (earnings per share were positive but eased year on year)
- Trailing 12-Month Net Income (Q3 2026 vs Q3 2025): loss of US$225.3m vs. profit of US$53.6m (moved from profit to a sizeable loss over the last year)
Prefer clean visuals to another wall of earnings tables and leverage ratios? See Olin’s full financial picture, including a clear view of its balance sheet strength and debt profile, in the company report for Olin.
Evaluating Olin’s Cost And Synergy Milestones
The bullish view hinges on Olin turning programs and merger plans into durable margin gains rather than just talking about them.
"Bullish analysts expect Olin to use structural cost reductions, epoxy restructuring, Winchester efficiency gains and the planned Huntsman merger to build a more integrated and higher margin chemicals and ammunition platform over the next several years."
Q3 shows real, if early, traction. Beyond250 is delivering US$110 to 120m of incremental structural savings in 2026, with another US$60 to 80m targeted next year, already exceeding the original US$250m goal by 2028. Epoxy margins are improving as structural costs come out and mix tilts toward formulated solutions. Winchester secured more than US$1b of new military contracts, which supports the efficiency push. Huntsman integration work is underway, and management reaffirmed more than US$400m of targeted merger synergies.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Olin Bear Case: Cost Wins Masked By Cash And Outages
Bearish voices argue Olin’s cost wins could be swallowed by integration and outage friction.
"Although the planned merger with Huntsman is framed around more than US$400 million of cost and raw material synergies, the roughly US$150 million to US$200 million required to achieve these savings and the complexity of integrating a combined revenue base of about US$12.5b could strain Olin’s already higher projected 4.5x leverage and limit how much of the promised earnings uplift ultimately reaches net income."
Q3 supports that concern. Beyond250 is ahead of plan and Epoxy profitability is better, yet trailing 12 month results still show a sizeable loss and leverage is guided to about 5x or slightly higher, with litigation cash outflows and outage costs absorbing a meaningful share of operating progress.
Spot Hidden Setups Before Consensus
Olin’s quarter shows how quickly sentiment can change when earnings, cash, and leverage move in different directions. The real opportunity is finding stocks that could be undervalued before the market reassesses them.
- Company 1 - 22% below our estimate - target surging data center buildouts with segment backlogs rising and operating cash flow supporting expansion without long term debt.
- Company 2 - 31% below our estimate - anchor critical digital infrastructure by supplying custom silicon and software that handle, secure, and manage traffic across large scale computing environments.
- Company 3 - 46% below our estimate - convert a near record construction backlog of complex mega projects into fee based work while addressing legacy legal disputes.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com