
How Leak Detection Rollout At United Utilities Group (LSE:UU.) Has Changed Its Investment Story
- United Utilities Group has been rolling out satellite imaging, telecoms fiber networks and other advanced tools to find leaks, aiming to cut water loss and reduce operating costs across its regulated water and wastewater network.
- The same technology push that tightens leak control also reshapes the long term cost base, which could influence how regulators view future investment allowances and returns.
- We will now look at how United Utilities Group's leak detection technology rollout could reshape its investment narrative for long term investors.
Scan how United Utilities Group's technology push compares with other regulated plays by zeroing in on a hand picked shortlist of 5 resilient stocks with low risk scores.
United Utilities Group Investment Narrative Recap
To own United Utilities Group, you need to be comfortable with a regulated water business that leans heavily on long term capital spending and stable, policy driven revenue. The leak detection rollout speaks directly to that thesis. Better visibility on water loss can support service quality and operational control, but the near term benefit for earnings looks gradual rather than dramatic.
The more immediate swing factor still sits with funding costs and allowed returns under AMP8. Higher operating expenses and depreciation, plus rating agencies’ negative outlook, keep balance sheet resilience in focus. If financing terms or cost inflation bite harder, that would test United Utilities Group more than any single technology project.
The most relevant development here is the broader AMP8 capital program of about £11.5b, with a heavy emphasis on asset health and environmental projects such as Lake Windermere. Leak detection technology plugs straight into that effort by helping the utility target spending and reduce wasted water across its 122,000 kilometers of pipes.
Ofwat’s annual totex re opener process and the draft allowance of £975m of year one spending give some visibility on how that program may be funded and remunerated. For you as a potential shareholder, the key question is whether United Utilities Group can deliver this capex plan efficiently enough to justify its current P/E and absorb higher leverage without straining cash generation or dividend cover.
United Utilities Group's current analyst storyline points to £3.1b of revenue and £774.7m of earnings by 2029, implying 5.9% yearly top line growth and an earnings increase of about £188m from the £586.8m reported today.
Uncover why United Utilities Group's fair value indicates it is trading roughly in line with its current price.
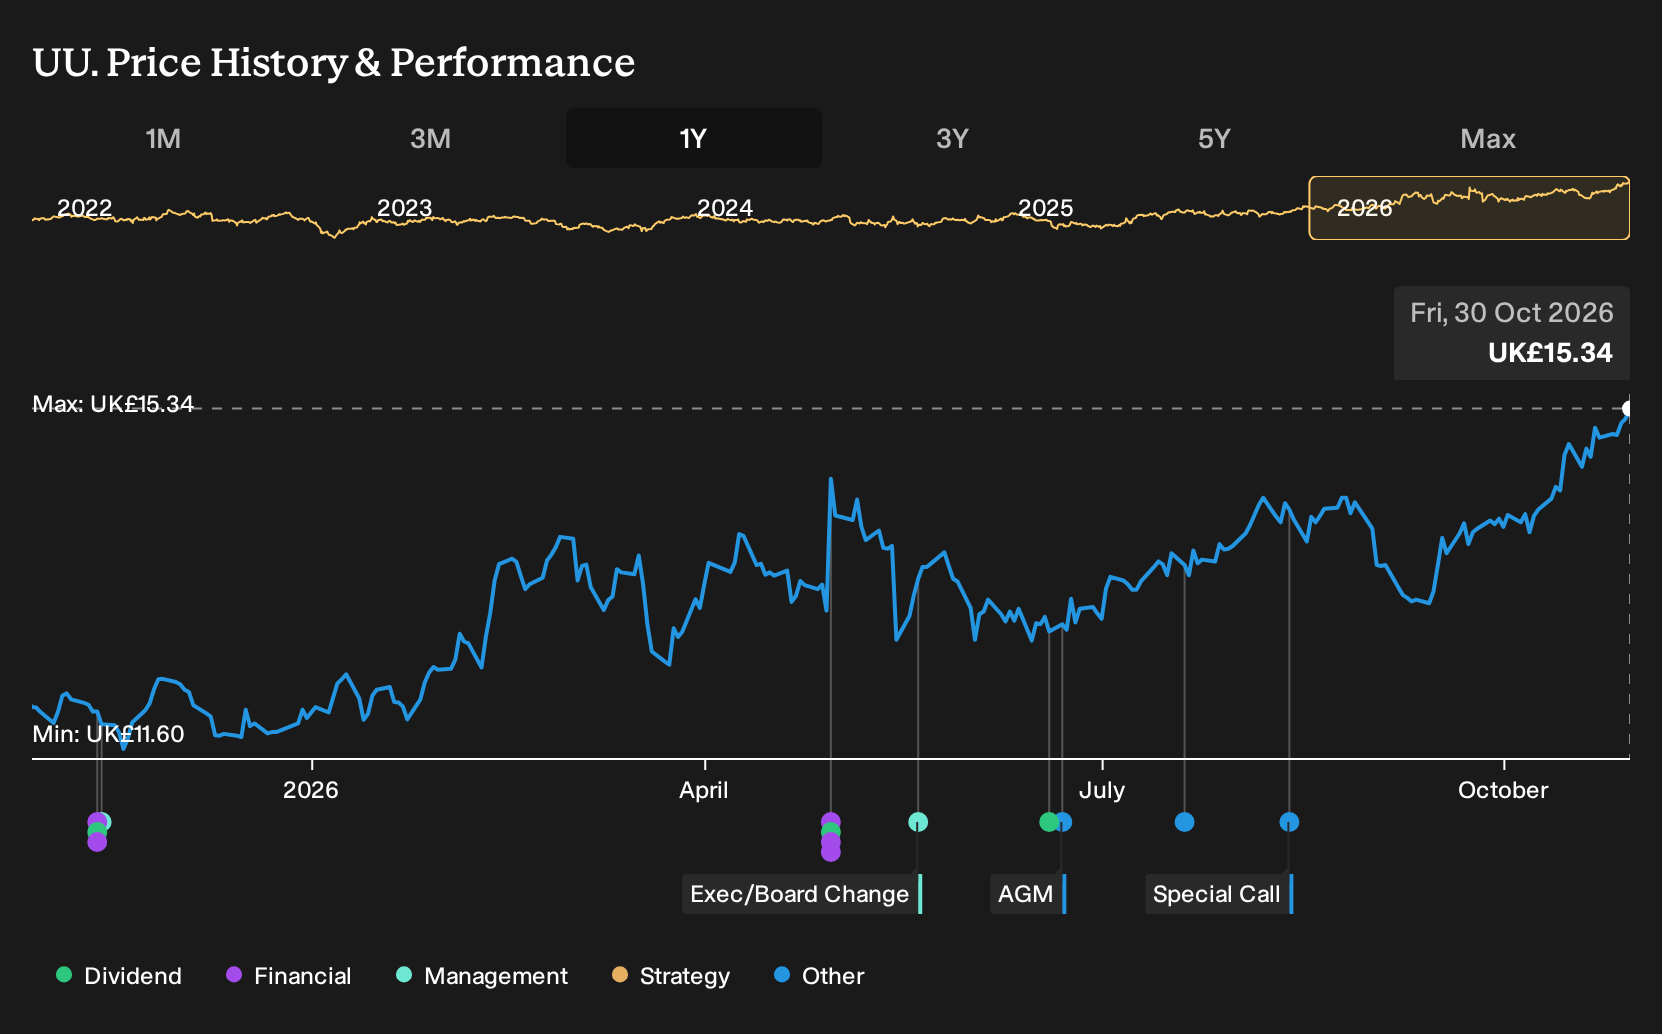
Exploring Other Perspectives
Retail investors in the Simply Wall St Community are split, with just 2 fair value views for United Utilities Group stretching from about 5.17 to 15.12. That is a wide gap. Set those opinions against live issues like rating agency pressure and rising operating costs, which could heavily influence how the AMP8 plan feeds through to future performance. You should treat this as a prompt to examine several alternative viewpoints before committing capital.
Explore another United Utilities Group fair value estimate, including one that suggests it could be worth as much as £15.12.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so go with your instincts.
- A great starting point for your United Utilities Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Utilities Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Utilities Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Utilities Group?
If the United Utilities Group story has sharpened your thinking about risk, income and balance sheet strength, use that same lens on a wider watchlist. The Simply Wall St Screener lets you quickly sift through companies that match your own tolerance for volatility, income needs and financial resilience.
- If capital preservation is your priority, start by scanning a curated group of relatively steady candidates through a 5 resilient stocks with low risk scores that keeps downside risk front and center for you.
- For readers focused on resilient finances and cleaner balance sheets, a targeted pass through the list of solid balance sheet and fundamentals (10 results) can surface companies with stronger fundamentals than the broader market average.
- Those hunting for mispriced quality can cast a wider net across the 12 high quality undervalued stocks and see which stocks currently combine fundamental strength with more modest valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com