
Harley Davidson (HOG) Stock Rallies While Q3 Earnings Stay Fragile
Harley-Davidson just put Q3 2026 on the table and the stock answered first. Shares closed at US$31.22 on Friday, up 2.9% on the day, after a week and quarter that were already solid in price terms.
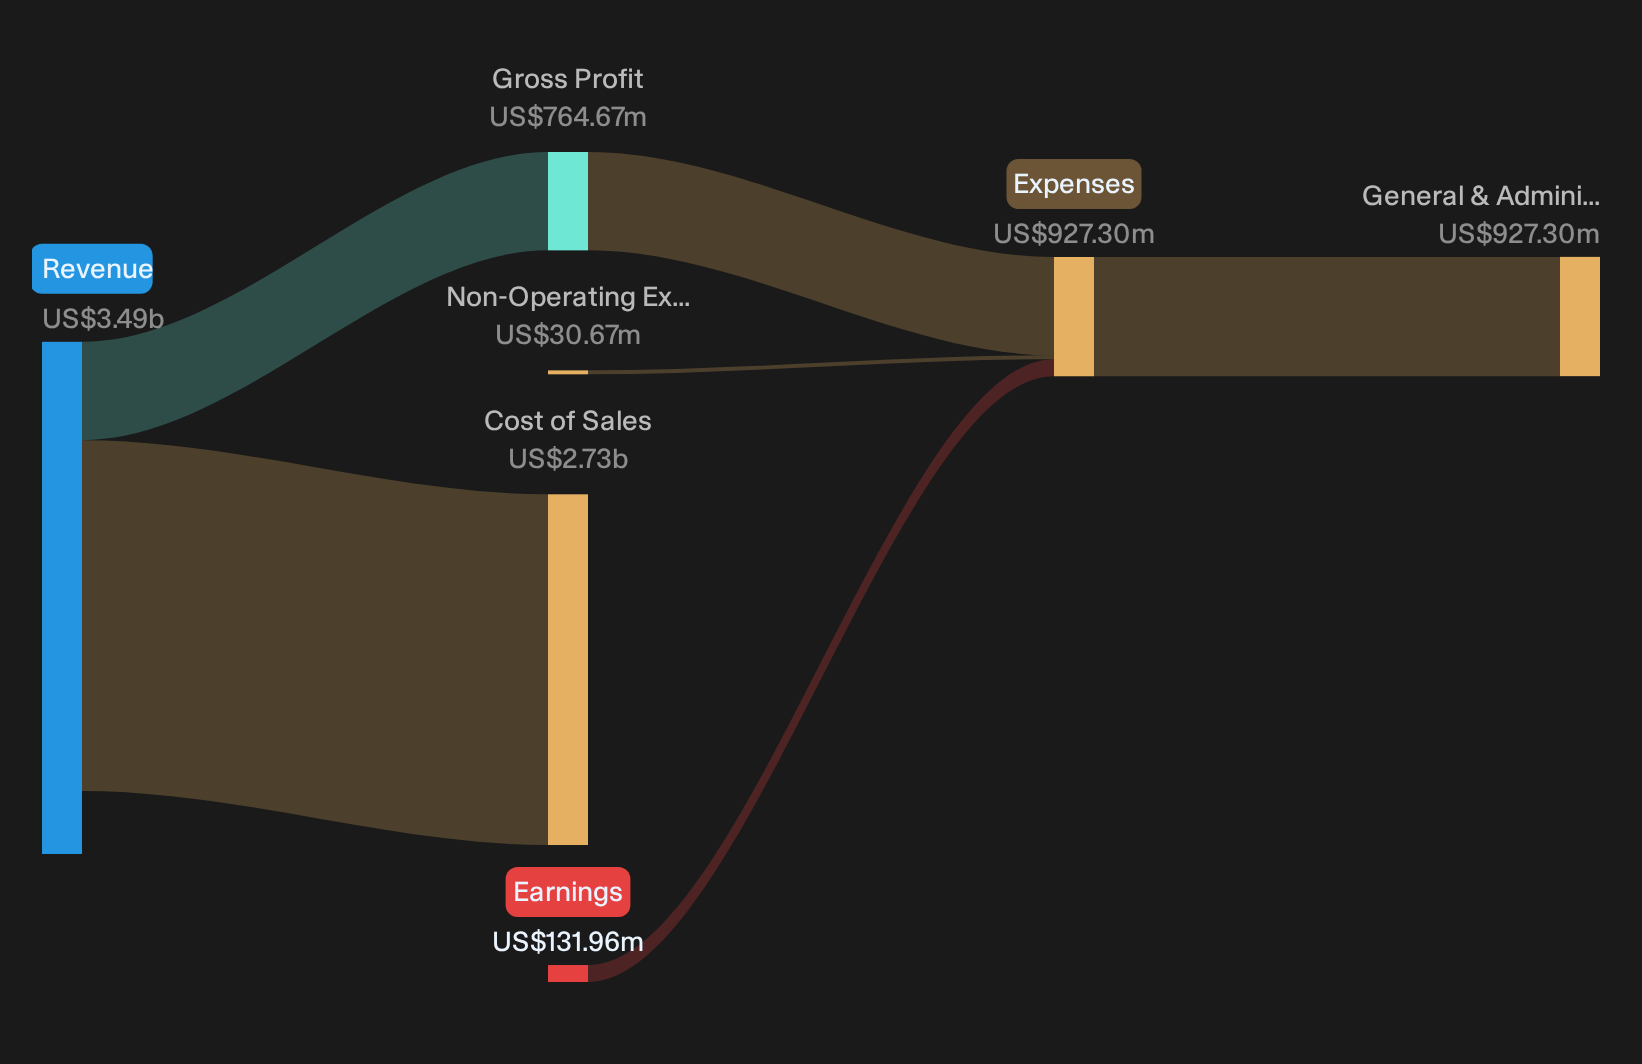
The reaction suggests relief. The headline print is more mixed. Basic earnings per share landed at about US$0.41 on US$1.08b of revenue, and trailing twelve month figures still show the business in a loss position. The gap between a rising share price and an unprofitable year sets the stage for what really matters in this quarter.
Love the Harley-Davidson brand strength but concerned that trailing twelve month earnings are still in the red? Compare this setup with companies that pair resilient balance sheets and solid fundamentals in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,082.6m vs. US$1,340.7m (down 19.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$42.8m vs. US$377.4m (down 88.7%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.41 vs. US$3.13 (down 86.8%)
- HDMC Operating Margin (Q3 2026): 4.6% reported margin, including US$14m of restructuring costs, with adjusted EBITDA margin at 9.7%
Prefer clean, visual charts instead of wading through dense financial reports and spreadsheets? See Harley-Davidson's full picture, including a clear view of its valuation, in the interactive company report for Harley-Davidson.
Evaluating Harley-Davidson’s Balance Sheet Led Reset
The bullish reset hinges on Harley-Davidson proving that dealers, products and financing can knit together into a sturdier profit engine.
"The main thing that has to go right is for Harley-Davidson to convert its Back to the Bricks product and P&A reset, dealer profitability improvement and capital structure changes into steady earnings despite tariff costs, rating pressure and LiveWire losses."
Q3 edges toward that vision but does not yet secure it. Retail motorcycles grew and dealer inventories look healthier, which supports the dealer profitability goal. P&A and apparel posted better performance, in line with the mix shift story. Yet consolidated EPS of about US$0.40 and a basic loss over the past year show that the steady earnings piece is still missing, even with raised HDMC and HDFS guidance and a firmer net cash position.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
Harley-Davidson Tariff Fears Meet Thin Earnings
Bearish investors worry Harley-Davidson will not earn enough to comfortably cover higher trade costs and LiveWire drag. That concern focuses on earnings quality rather than just headline growth.
"Even with tariff exemptions on selected parts and the move to reshore some production, Harley-Davidson still guides to US$75–90 million of incremental tariff costs in 2026 versus 2024 and has already absorbed US$67 million in the first half, which could keep gross margin and operating margin under pressure even if motorcycle volumes hold up."
Q3 data lines up with that fear. HDMC gross margin expanded, yet consolidated operating margin fell sharply and EPS dropped versus last year while LiveWire losses and weaker Europe weigh on overall profitability.
Hunt For Mispriced Earnings Power
Harley-Davidson reports a quarter that leaves investors debating the gap between profits and price. The real opportunity sits in finding companies that could be undervalued before that gap closes.
- Company 1 - 34% below our estimate - converts long term optical and solar supply agreements and customer prepayments into a higher margin infrastructure backlog.
- Company 2 - 38% below our estimate - extends coconut based drinks from niche shelves into mainstream aisles while scaling private label volumes without losing pricing discipline.
- Company 3 - 30% below our estimate - ties AI centric networking gear and data center hardware into recurring cloud and consumption contracts built around a large acquisition.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com