
Joby Aviation (JOBY) Stock Looks Priced For Perfection On Sales
Joby Aviation has gone from high expectations to a sharply lower share price, and that raises a straightforward question for you as an investor. Is the current US$4.90 stock price adequately supported by the sales this air taxi developer is generating today and is expected to produce from its emerging operations?
- The share price has fallen 71.7% over the past year, which puts the spotlight squarely on whether the remaining market value still lines up with Joby Aviation’s sales profile.
- Recent news around FAA certification timing, a US$116.9m jury verdict and ongoing work to build commercial air taxi and defense-related revenue can all shape how quickly sales may grow and how much capital the business might need along the way.
- The analysts covering Joby Aviation have run their own numbers. See what analysts think Joby Aviation's shares could be worth.
The issue now is whether Joby Aviation’s current valuation can be explained by its sales relative to what the Fair Ratio benchmark would suggest.
If you want to stress test this same sales based question beyond Joby Aviation, you can benchmark it against 30 high quality undervalued stocks
Does Joby Aviation Look Pricey on Sales?
P/S fits Joby Aviation because the business is still focused on building out commercial operations rather than reporting consistent earnings.
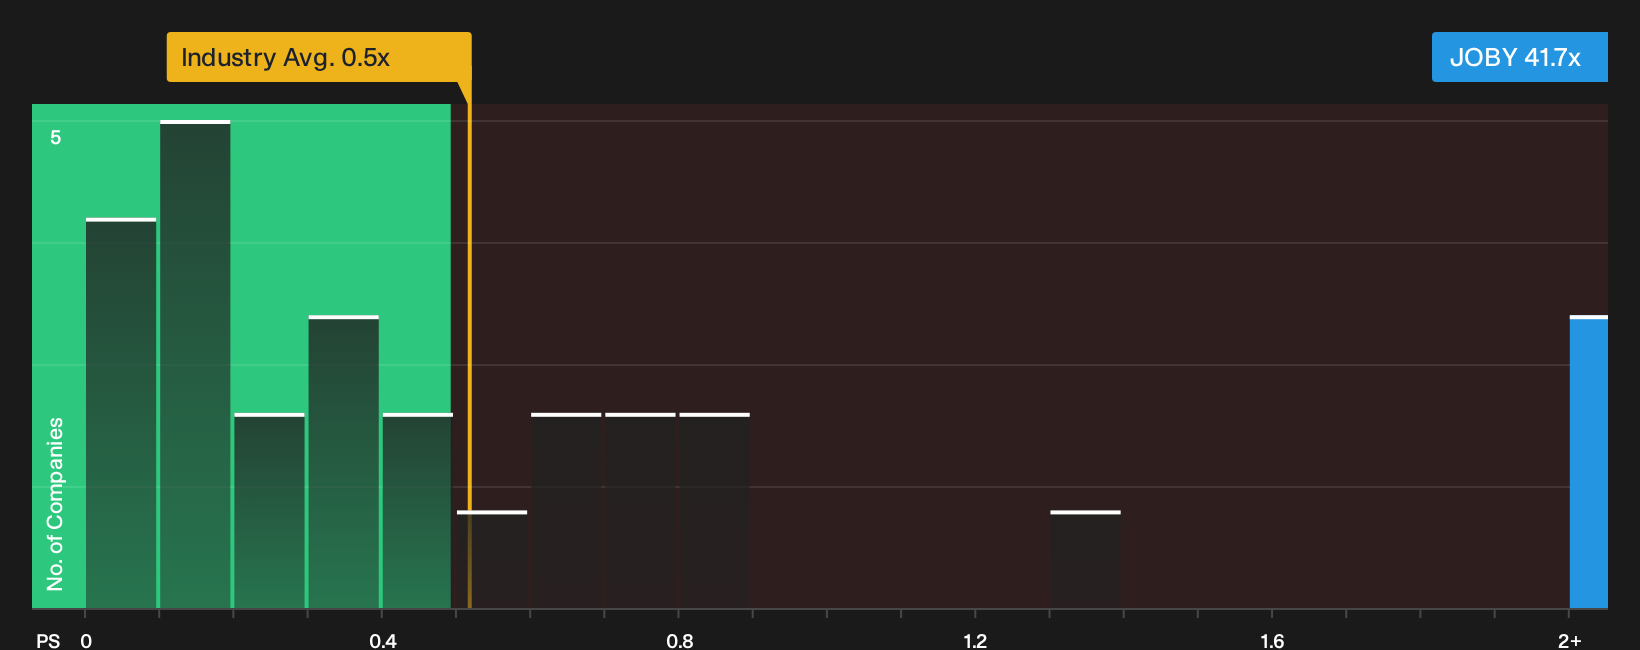
On this metric, the stock trades on a P/S of about 41.7x, compared with an Airlines sector average of roughly 0.5x and a peer group closer to 0.6x. A Fair Ratio model that factors in growth potential, margins, size and risk points to a much lower multiple as a reference point, and the gap is so wide that it mainly flags how aggressively the current price values future progress rather than acting as a precise target. Because the FAA certification delays and the recent US$116.9m jury verdict keep execution risk in focus, that rich P/S ratio leaves very little room for disappointment if Joby Aviation’s revenue build out takes longer or proves lumpier than the market currently expects. Explore the numbers behind Joby Aviation's P/S valuation.
The Joby Aviation Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Joby Aviation valuation puzzle leaves off. They spell out the specific assumptions on future growth, profitability and earnings power that would need to hold for Joby Aviation's share price to look meaningfully higher or lower than it is today, and each one frames fair value as a thesis about the business that you can track over time rather than a static snapshot on a single day.
Community views on Joby Aviation split sharply between those who see a heavily discounted air taxi platform and those who see a very expensive story.
Bull case: 73% undervalued
"The combination of around US$2.3b in cash and guided second half cash use focused on certification, eIPP operations and commercialization gives Joby Aviation room to fund additional programs…"
Discover why this Narrative puts Joby Aviation at 73% undervalued.
Bear case: 1481% overvalued
"Joby’s quarterly free cash flow burn consistently exceeds $150M-$200M as manufacturing facilities, conforming test aircraft, and flight campaigns expand…"
Explore why this Narrative puts Joby Aviation at 1481% overvalued.
Joby Aviation’s valuation still leaves one crucial angle unexplored
Price, sales and growth stories only go so far if you do not know who is steering Joby Aviation or how their incentives are structured. That is where the next layer of analysis starts. See who runs Joby Aviation and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com