
How Raised Earnings Guidance At East West Bancorp Stock Has Changed Its Investment Story
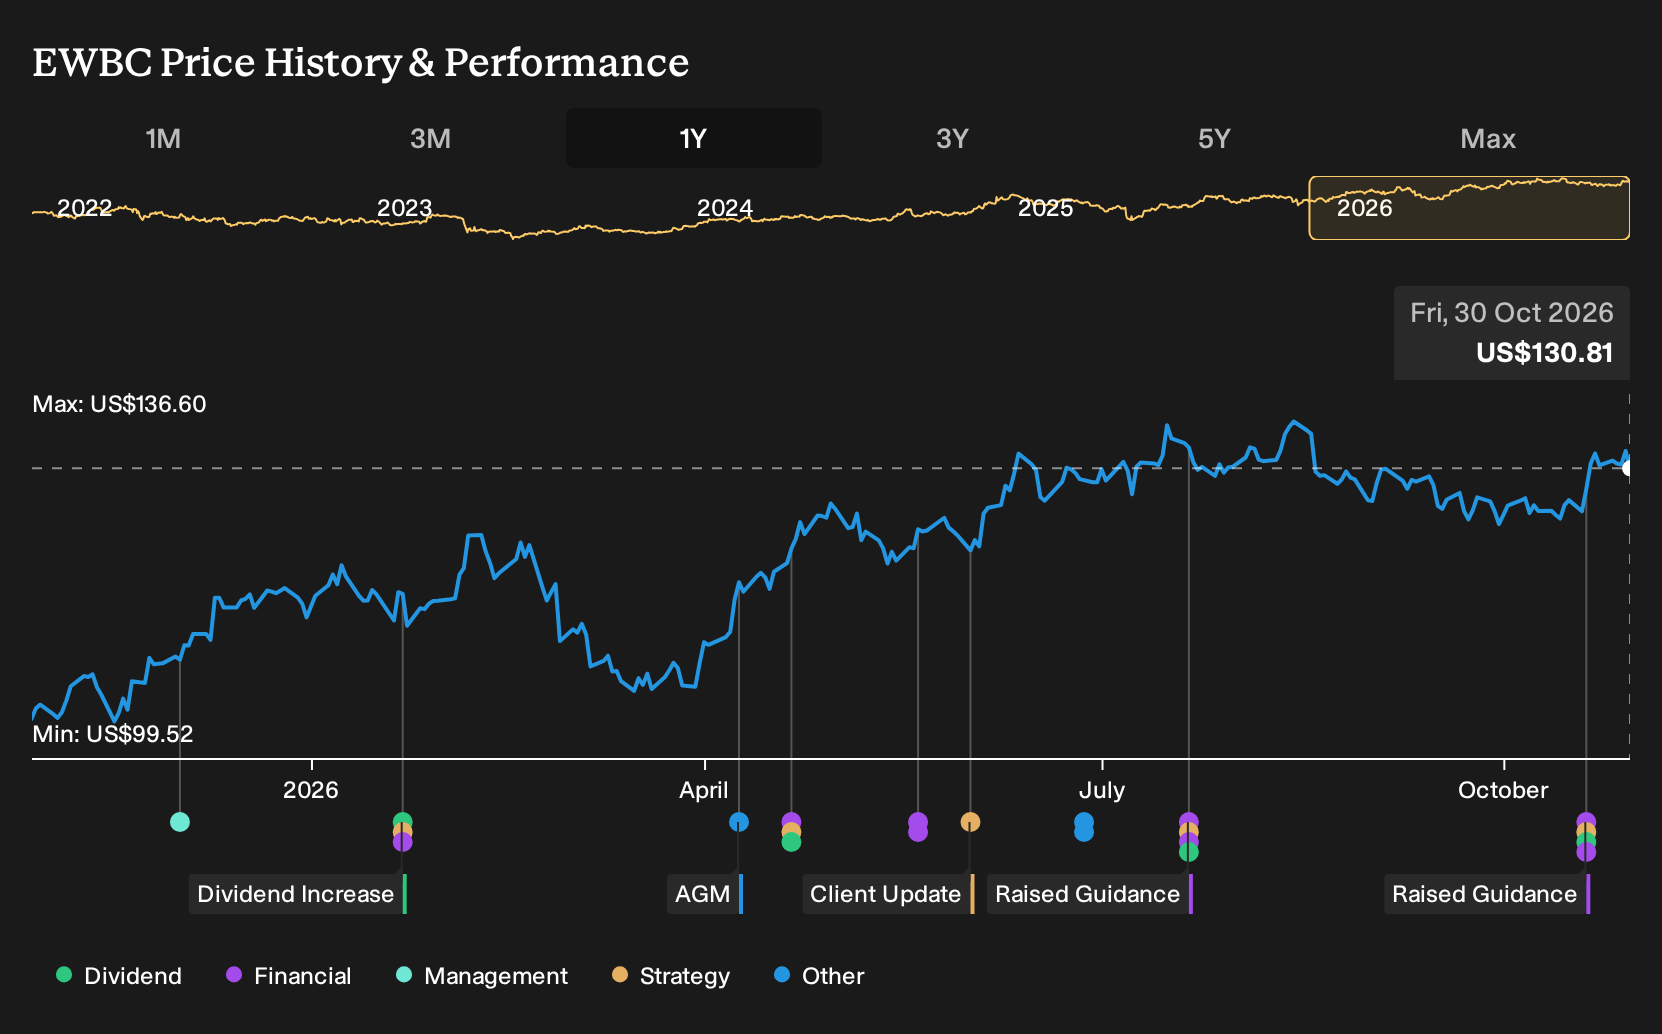
- East West Bancorp raised full year 2026 earnings guidance after a third quarter that included higher net interest income of US$718.9 million and net income of US$382.2 million compared with the prior year period.
- The updated outlook for 9% to 10% full year net interest income growth highlights how rate moves and loan performance are feeding directly into East West Bancorp’s core earnings power.
- Investors can now observe how East West Bancorp’s higher full year net interest income guidance could influence its broader investment narrative.
Compare East West Bancorp's earnings-driven story with a handpicked group of banks and financials that show resilient balance sheets and income trends through our 30 resilient stocks with low risk scores
East West Bancorp Investment Narrative Recap
To own East West Bancorp, you need to believe the bank can keep turning its U.S.–Asia niche and deposit franchise into steady net interest income without letting credit costs or funding pressures eat into that story. The higher 2026 NII growth guidance sits right at the center of that belief, because it ties recent rate moves and loan performance directly to earnings power.
The key short term swing factor is how deposit pricing and loan demand hold up after September’s rate hike, since both feed straight into NII and return on equity. The biggest risk is that competition for deposits and any uptick in credit losses compress margins faster than guidance assumes, especially with large CDs regularly rolling and fee income already showing some quarter to quarter variability.
The most relevant fresh data point for that thesis is the third quarter earnings print. Net interest income of US$718.9 million, net income of US$382.2 million and diluted EPS of US$2.76 give you a concrete sense of how East West Bancorp is currently monetizing its loan book and deposit base under the new rate backdrop.
Net charge offs of US$22 million, or 0.15% of average loans held for investment, provide an important read on asset quality alongside the updated NII outlook. Credit losses at that level support the idea that the current allowance for credit losses and diversified portfolio mix are still doing their job, although any future stress in loans or more aggressive deposit pricing could quickly become the main pressure points on the guidance investors are watching.
East West Bancorp's analyst narrative points to revenues of US$3.9b and earnings of US$1.7b by 2029. This implies forecast revenue growth of 10.3% per year and an earnings increase of about US$300m from current earnings of US$1.4b.
Uncover why East West Bancorp's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from US$150 up to about US$268.95, so some retail investors see East West Bancorp as much cheaper than others do. Consider those opinions alongside the raised 2026 NII guidance, dividend commitment, and ongoing credit and funding risks, then explore the full spread of views before deciding where you sit.
Explore 2 other East West Bancorp fair value estimates, including one that suggests it could be worth just $150.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your East West Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for East West Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate East West Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond East West Bancorp?
If the East West Bancorp story has sharpened your thinking about banks and financials, use that momentum to review a wider set of opportunities. A focused screener helps you turn loose ideas into a concrete shortlist that actually fits your risk profile and return goals.
- For investors who want potential value on their side, scan a curated set of companies that screen as attractively priced with stronger fundamentals through 30 high quality undervalued stocks.
- If resilience matters most to you, compare businesses that pair stronger balance sheets with steadier financial profiles using our broader list of solid balance sheet and fundamentals (23 results).
- For those who prize income, review companies that currently offer higher yields and more established payout track records with the help of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com