
Is OBICLtd (TSE:4684) Overvalued Following Its Raised Earnings And Dividend Guidance?
OBIC Ltd (TSE:4684) has drawn fresh attention after revising its full year earnings forecast upward and lifting dividend guidance. The company links these moves to stronger first half performance and its shareholder return policy.
Investor interest has picked up around OBICLtd, with the share price gaining 23.59% over the past month and 35.45% across 90 days, while the 1-year total shareholder return of 30.82% indicates that recent momentum follows a longer, steadily positive track record.
Scan how OBICLtd fits into a wider field of strong performers by comparing it with a hand picked group of 15 high quality undervalued stocks that also pair fundamentals with momentum.
After a 23.59% surge in a month and fresh guidance from management, OBICLtd now sits at an interesting crossroads. Is the recent jump most of the story, or does the valuation still leave meaningful upside on the table?
Price-to-Earnings of 32.1x: Is it justified?
Valuation on OBICLtd now leans toward a richer side of the spectrum, with a P/E of 32.1x anchored against a last close of ¥6,129 and a discounted cash flow estimate of ¥4,664.62 suggesting the share price is above that modelled value.
The P/E ratio compares what investors pay today for each unit of earnings, so a higher figure often reflects strong confidence in a firm's profit profile. For a software and IT services player like OBIC Ltd, where earnings quality is described as high and net profit margins sit at 57%, that kind of earnings multiple can signal that buyers are comfortable paying a premium for the current earnings base.
Earnings growth of 17.8% over the past year, alongside 13.6% per year over five years, gives some context for why the market might accept a richer valuation. That said, forecasts pointing to earnings growth of 8.29% per year, slower than the broader JP market at 9.6% per year and below a 20% high growth threshold, mean the existing multiple implies strong confidence rather than rapid future expansion. The estimated fair P/E of 26.4x is materially lower than the present 32.1x level. This is a valuation zone the market could also gravitate toward if sentiment cools.
Against peers, the contrast is stark. The JP IT industry average P/E of 16.1x is roughly half OBICLtd's current 32.1x, which points to a clear premium relative to the wider sector even if the stock is framed as better value than a peer group average at 64.3x. That mix of high profitability and stronger historical earnings growth helps explain why the shares trade where they do, but it still leaves the current P/E looking expensive on both industry and fair ratio checks.
Explore the SWS fair ratio for OBICLtd.
Result: Price-to-Earnings of 32.1x (OVERVALUED)
Still, a premium P/E and share price above some value models leave OBIC Ltd exposed if earnings momentum or sentiment around Japanese software stocks weakens.
Find out about the key risks to this OBICLtd narrative.
Another view on OBIC Ltd using the SWS DCF model
The SWS DCF model points in the same direction as the P/E work. With OBICLtd at ¥6,129 against a discounted cash flow estimate of ¥4,664.62, the stock screens as overvalued on cash flows as well. That raises a simple question for you: How comfortable are you paying above that DCF mark for quality earnings and revenue growth that are forecast, but not rapid?
Look into how the SWS DCF model arrives at its fair value.
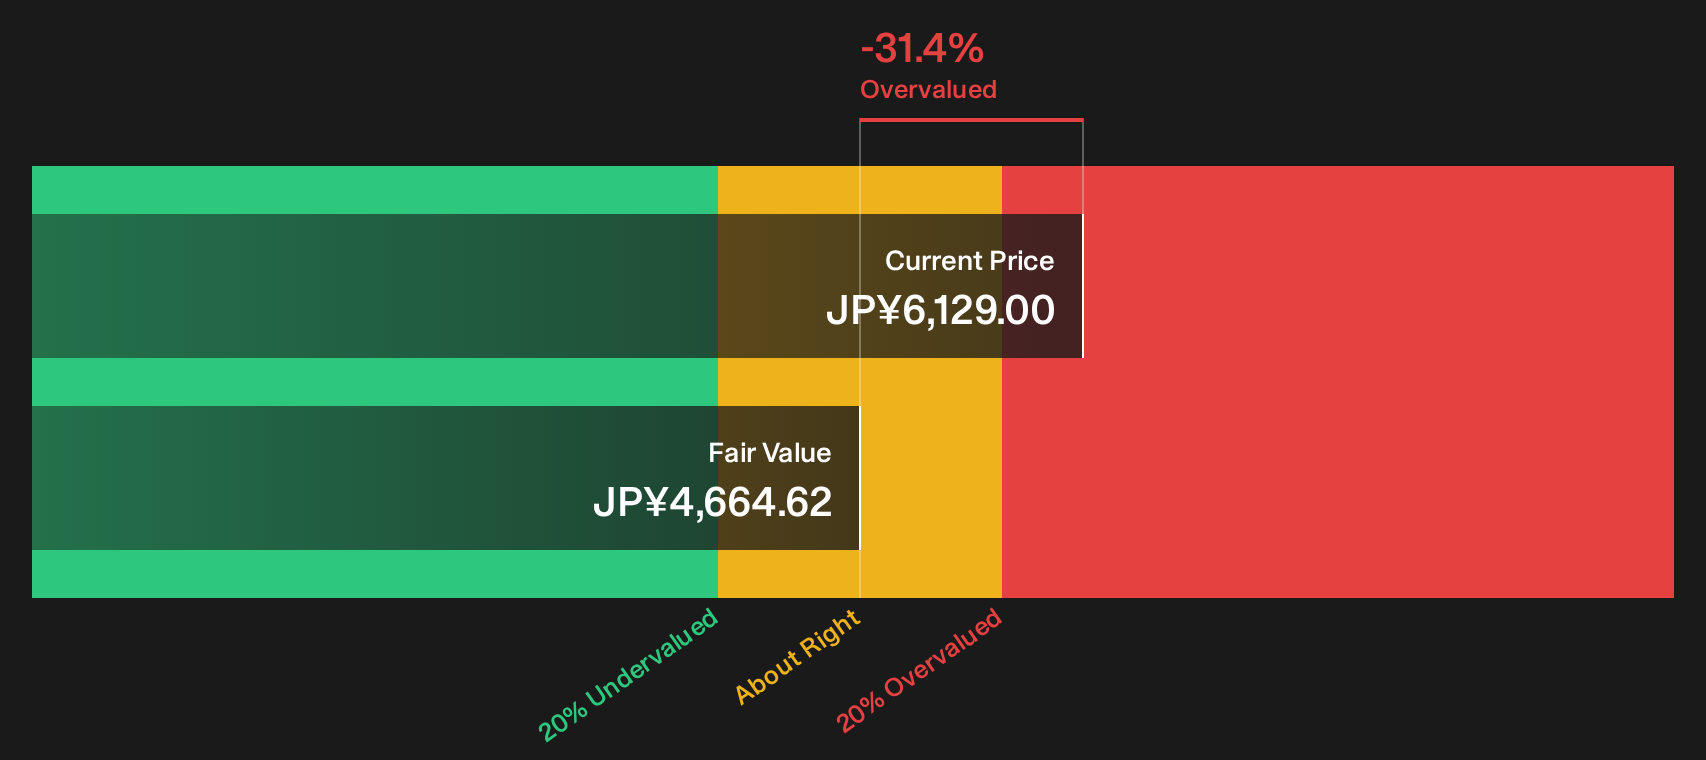
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OBICLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the upbeat tone around OBIC Ltd really fits your own risk and reward tolerance, or if the premium story feels stretched? Take a few minutes to test the assumptions against your own framework and then weigh them against the 2 key rewards.
Looking for more investment ideas beyond OBIC Ltd?
If OBIC Ltd feels fully priced to you, broaden your watchlist now. Fresh ideas often appear first in focused screens before they reach a wider audience.
- Target income resilience by reviewing a curated set of 27 dividend fortresses that aim to pair higher yields with balance sheet strength.
- Search for quality at a reasonable price with our 71 high quality undiscovered gems, where solid fundamentals meet limited market attention.
- Reduce portfolio fluctuations by scanning through 24 resilient stocks with low risk scores that score well on financial stability and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com