
ESCO Technologies (ESE) Earnings Growth Puts Fair Value Back In Focus
ESCO Technologies (ESE) caught investor attention after reporting year over year EPS growth of 23.51%, as the share price moved 1.13% higher to close at US$238.23, despite generally cautious technical signals.
Set against a 1-day share price return that fell 2.94% to about US$237.70, ESCO Technologies is still up 20.28% on a year to date share price basis, with 1-year total shareholder return of 8.44% and a strong 3-year total shareholder return of 138.74%. This indicates that long term holders have seen robust gains even as shorter term momentum has cooled.
Scan other industrial and defense suppliers that show similar earnings momentum to ESCO Technologies by checking our hand picked list of 30 high quality undervalued stocks.
Strong earnings and a solid niche in aerospace, defense and utilities give ESCO Technologies a compelling story. After this mix of gains and a recent pullback, the key issue is whether the current share price still offers value.
Most Popular Narrative: 33% Undervalued
The most followed valuation narrative for ESCO Technologies pegs fair value at about $352.75, which sits well above the recent $237.70 close. As a result, the spotlight shifts to whether the underlying growth story can support that gap.
Continued long-term growth in global electricity demand driven by trends such as electrification of transportation, grid expansion for data centers and AI, and increased renewable integration is described as positioning ESCO Technologies' Utility Solutions Group and Doble for sustained order momentum and rising recurring revenues in utility infrastructure, supporting future top-line growth and improved earnings visibility.
See why 3 investors see ESCO Technologies as 33% undervalued.
Result: Fair Value of $352.75 (UNDERVALUED)
Still, ESCO Technologies carries clear pressure points, including weak conditions in its renewables focused NRG unit and execution risk around the large Megger integration and related debt load.
Find out about the key risks to this ESCO Technologies narrative.
Another View: ESCO Technologies Through The Earnings Multiple
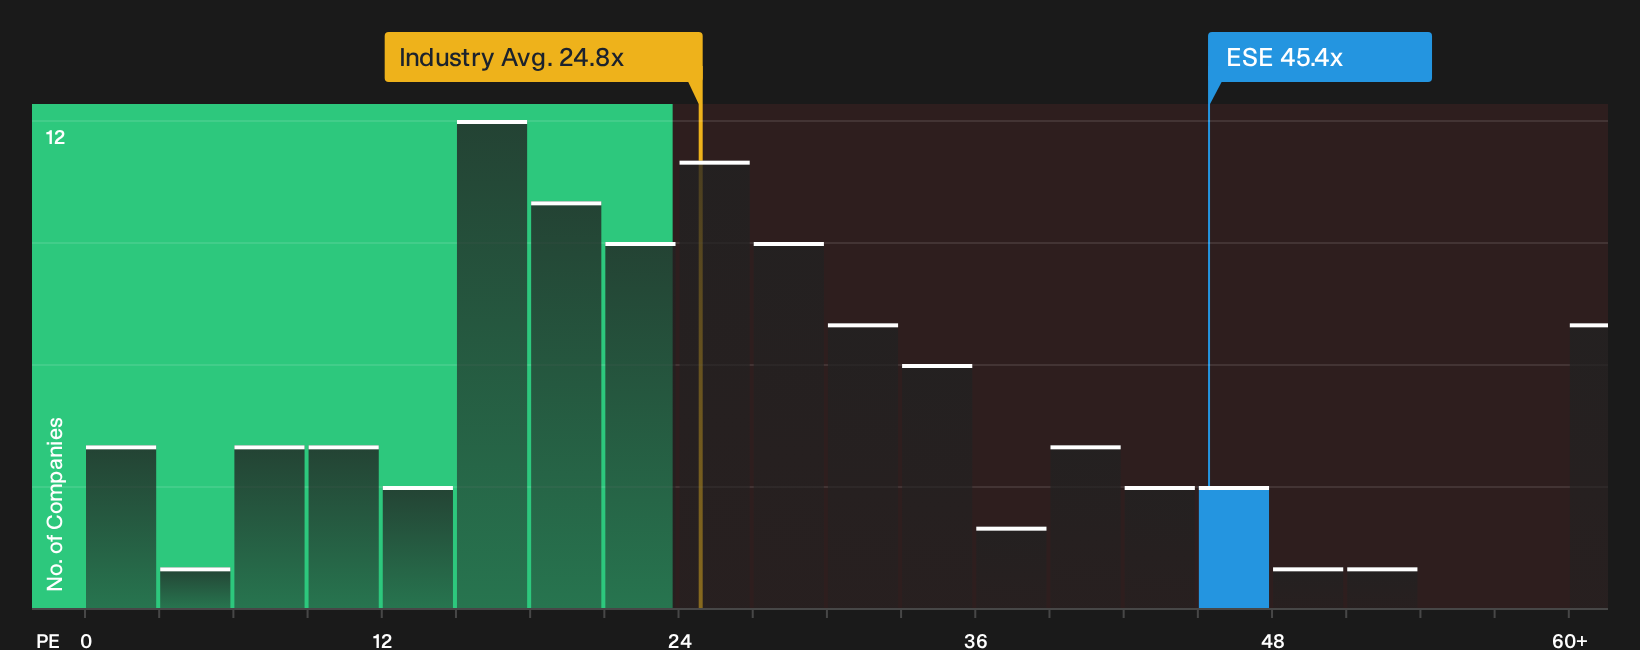
That 33% undervalued story leans on long range growth and cash flow assumptions. The current P/E of about 45.4x tells a different story. It sits well above the US Machinery industry on 24.4x and also above an estimated fair ratio of 29x, which points to meaningful valuation risk if expectations soften.
Compared with peers on roughly 53.5x, ESCO Technologies trades at a discount to its closest comparison group, yet still on a rich multiple for the wider sector. The key consideration is whether the quality of earnings growth and backlog justifies that premium or whether the share price could move closer to the fair ratio over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this ESCO Technologies story is mixed, with strong numbers set against valuation questions, so treat the data as your starting point and pressure test it. Look through the rewards investors are focusing on by checking the 4 key rewards.
Looking For More ESCO Technologies Style Ideas?
If ESCO Technologies has sharpened your focus on quality, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh, data driven opportunities before others react.
- Target resilience first and scan a 30 resilient stocks with low risk scores universe where balance sheets and risk scores take center stage.
- Hunt for value and review a curated 30 high quality undervalued stocks set that blends quality metrics with pricing that still looks appealing.
- Spot potential future leaders early by checking a focused 18 high quality undiscovered gems pool of fundamentally strong but less followed stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com