
Tabcorp Holdings (ASX:TAH) Foxtel Talk Tests Whether Its Valuation Still Stacks Up
Talk around a possible Foxtel acquisition has put Tabcorp Holdings (ASX:TAH) back under the spotlight, as investors weigh how a larger media footprint might reshape earnings mix and future funding choices.
Recent trading tells a mixed story. The A$0.89 share price has climbed over the past week, with a 7 day share price return of 4.09%. However, year to date it is down 9.64% on a share price basis. That drop sits against a 1 year total shareholder return decline of 13.84%, even though longer holders have seen total shareholder returns of 17.87% over 3 years and 48.44% across 5 years, which suggests that sentiment has cooled recently even as longer term investors remain in profit.
Compare Tabcorp Holdings with other betting and media stocks that may offer a cleaner earnings story or cheaper valuation by scanning our hand picked 1 high quality undervalued stocks list.
Tabcorp Holdings now pairs a long running betting and media franchise with fresh Foxtel speculation and a share price that has slipped this year. The key question is whether that mix is actually cheap or already fully valued.
Most Popular Narrative: 13% Undervalued
On the narrative view, Tabcorp Holdings screens as undervalued, with a fair value of A$1.03 against the A$0.89 last close. This view puts more weight on future digital execution and regulatory outcomes than the recent share price does.
Ongoing digital transformation initiatives including new customer offerings (e.g., in-play betting and omnichannel experiences) and tech upgrades to both digital and retail platforms position Tabcorp to capture higher online wagering volumes as mobile and digital betting become more mainstream, directly supporting future revenue growth and improved net margins.
See why 11 investors see Tabcorp Holdings as 13% undervalued.
Result: Fair Value of A$1.03 (UNDERVALUED)
Still, the Tabcorp Holdings story could be knocked off course if wagering volumes remain under pressure or offshore online rivals continue to chip away at digital share.
Find out about the key risks to this Tabcorp Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Tabcorp Holdings
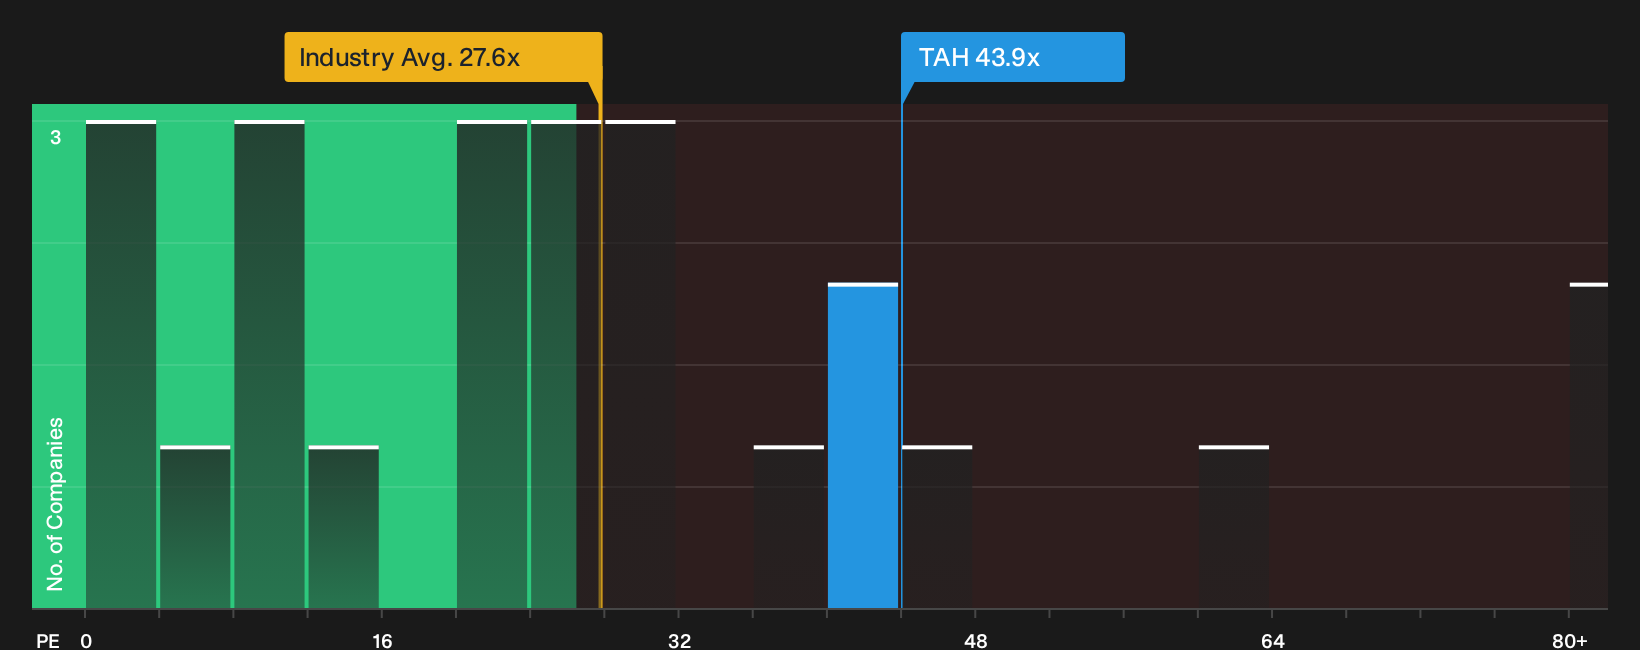
There is a catch. While the narrative and fair value work suggest Tabcorp Holdings looks undervalued, the current P/E of 43.9x is rich compared with the Oceanic hospitality sector on 27.6x, peers on 25x and a fair ratio of 24.9x, which points to real valuation risk if sentiment cools.
For investors who lean on earnings multiples, this kind of premium can matter when expectations reset or growth disappoints. It is worth pressure testing how much confidence you really have in the earnings ramp that would justify it before leaning too hard on the A$1.03 fair value anchor.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Tabcorp Holdings can cut both ways. Move quickly, compare the upside and downside for yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tabcorp Holdings?
If Tabcorp Holdings has sharpened your focus, do not stop here. Fresh opportunities often sit just outside your current watchlist, and skipping them can cost you.
- Hunt for stronger value by checking stocks that appear mispriced on fundamentals through the 1 high quality undervalued stocks.
- Prioritise resilience by scanning companies with cleaner finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (12 results).
- Stay early to potential market favourites by reviewing the 15 high quality undiscovered gems before they draw wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com