
USA Rare Earth (USAR) Stock Looks Cheap After Reshoring Opportunity Buzz
USA Rare Earth has been in the spotlight as investors weigh its role in supplying critical minerals against a share price that has seen sharp swings over the past year. With the stock now around US$10.52, the open question is whether that level can be squared with what the business is worth based on its book value.
- Over the past 12 months the share price has fallen 45.9%, which puts fresh pressure on the question of whether the current valuation is still aligned with the underlying balance sheet.
- Recent coverage highlighting USA Rare Earth as a potential reshoring play for critical minerals can shape expectations for future capital spending needs and the pace at which assets on the balance sheet may start to earn meaningful returns.
- The analysts covering USA Rare Earth have run their own numbers. See what analysts think USA Rare Earth's shares could be worth.
The issue now is whether USA Rare Earth's present market price is well supported by its book value when set against the industry average.
If you are weighing USA Rare Earth against other critical minerals plays tied to reshoring, it can help to compare it directly with 33 best rare earth metal stocks.
Is USA Rare Earth Still Cheap on Book Value?
P/B fits USA Rare Earth because the story today is about assets on the ground more than current earnings power.
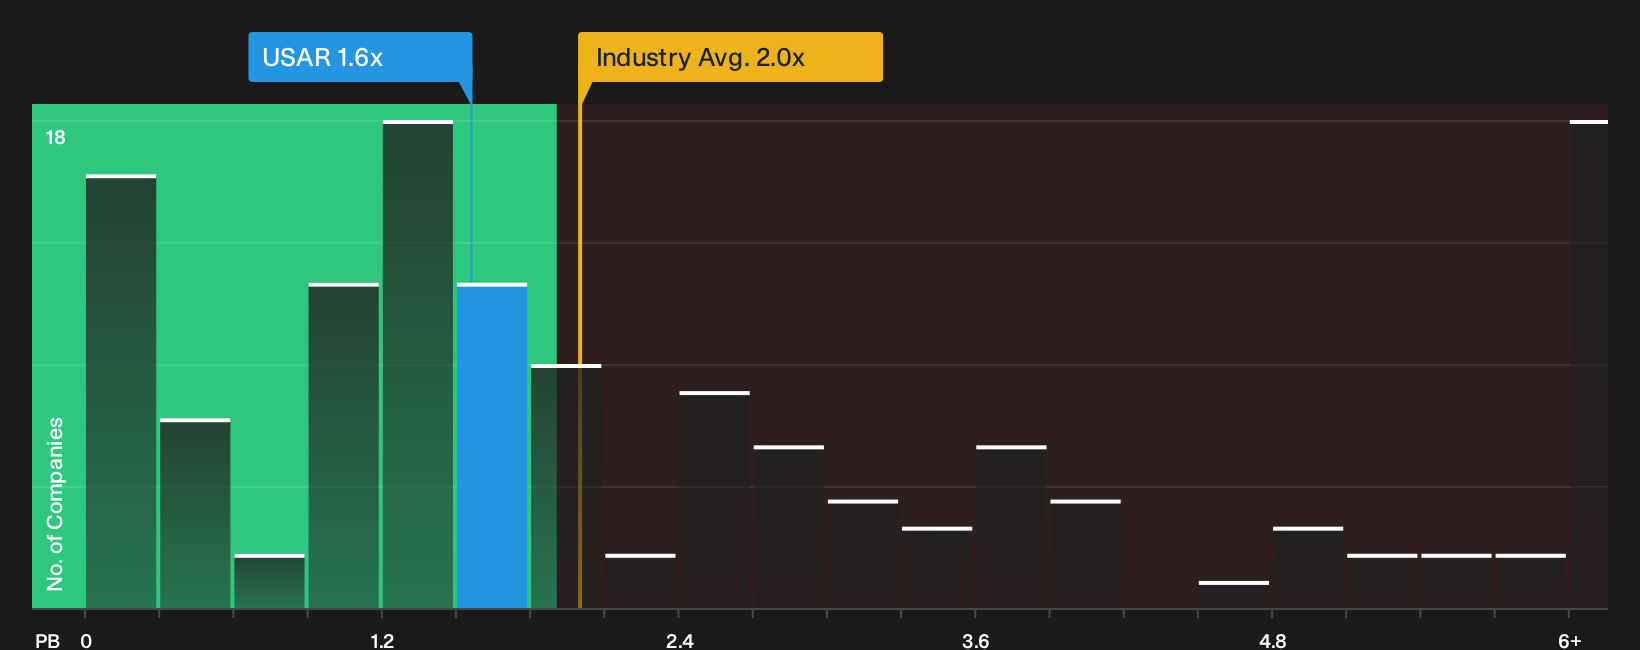
At roughly 1.6x P/B, USA Rare Earth trades below the broader metals and mining sector, where the average is around 2.0x, and also well under the 5.4x level seen across peers. That gap indicates the market assigns a lower premium to each dollar of equity here than it does for comparable miners. Because recent coverage has framed USA Rare Earth as a once in a generation reshoring play, the discount suggests investors are not paying up heavily for that narrative at the current quote.
For anyone comparing critical minerals stocks, this lower P/B multiple hints at an undervalued balance sheet against the industry benchmark. However, it still leaves the question of how effectively those assets can be turned into returns over time. Explore the numbers behind USA Rare Earth's P/B valuation.
The USA Rare Earth Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the USA Rare Earth valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the share price to land meaningfully above or below where it trades today on the market. Each view links a specific number to a clear stance on how USA Rare Earth's growth path, margin profile and risk picture might evolve, so you can revisit those assumptions on the Community page as fresh information comes through.
Community views on USA Rare Earth split sharply between those who see a vertically integrated rare earth chain taking shape and those who focus on execution and policy risk.
Bull case: 70% undervalued
"USA Rare Earth is building an integrated rare earth supply chain, from mining and processing to metal, alloy and magnet manufacturing, focused on ex China customers…"
Discover why this Narrative puts USA Rare Earth at 70% undervalued.
Bear case: 3088% overvalued
"This development adds another federal endorsement to USAR’s role in strengthening the domestic critical materials ecosystem and highlights the growing policy focus on securing U.S. access to rare earth supply chains…"
Explore why this Narrative puts USA Rare Earth at 3088% overvalued.
For USA Rare Earth, the share price is only one piece of the puzzle
Before you lean too hard on the numbers, it helps to understand who is steering USA Rare Earth and how their pay packets line up with your interests. See who runs USA Rare Earth and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com