
PG&E (PCG) Reports Mixed Earnings, Is The Valuation Gap Still There?
PG&E earnings jolt investor focus
PG&E (PCG) has drawn renewed attention after reporting third-quarter and nine-month 2026 results, with softer quarterly figures contrasting with higher revenue and profit over the longer period.
PG&E shares now trade at US$13.23, and the 1 month share price return of 8.62% and 7 day gain of 1.93% suggest a short term rebound. However, the 1 year total shareholder return has declined 15.7% and the 3 year total shareholder return is down 19.35%, pointing to momentum that has faded over a longer stretch.
Scan beyond PG&E and see how other regulated utilities are priced for potential rebounds with our curated list of 41 power grid technology and infrastructure stocks.
After a sharp move off the lows but a multi year record that still shows declines, the real puzzle for PG&E holders is whether most of the rerating has already happened or if the valuation still points to room ahead.
Most Popular Narrative: 25% Undervalued
PG&E is trading at $13.23 against a widely followed fair value estimate of $17.56. This frames today’s rebound as a move that still leaves a sizeable valuation gap according to the prevailing narrative built on regulated earnings, wildfire risk and capital spending assumptions.
Strong alignment of capital strategy and balance sheet flexibility is reinforced by PG&E maintaining FFO to debt around 13%, reaffirming 2026 core EPS guidance and initiating 2027 guidance while planning to avoid additional equity for its US$73b plan. Together with the pursuit of investment-grade ratings and lower financing spreads, this points to future support for earnings and potential dividend capacity.
See why 27 investors see PG&E as 25% undervalued.
Result: Fair Value of $17.56 (UNDERVALUED)
Still, wildfire liability reform setbacks and pressure on California bill affordability leave PG&E exposed to regulatory decisions that could tighten returns or raise financing costs.
Find out about the key risks to this PG&E narrative.
Another View: PG&E on Cash Flow Terms
There is a catch. While the popular PG&E story leans on a fair value of $17.56, the Simply Wall St DCF model values the stock at $9.38 based on future cash flows, which frames the current $13.23 share price as expensive rather than cheap. Which lens do you trust more when cash generation is the anchor?
Look into how the SWS DCF model arrives at its fair value.
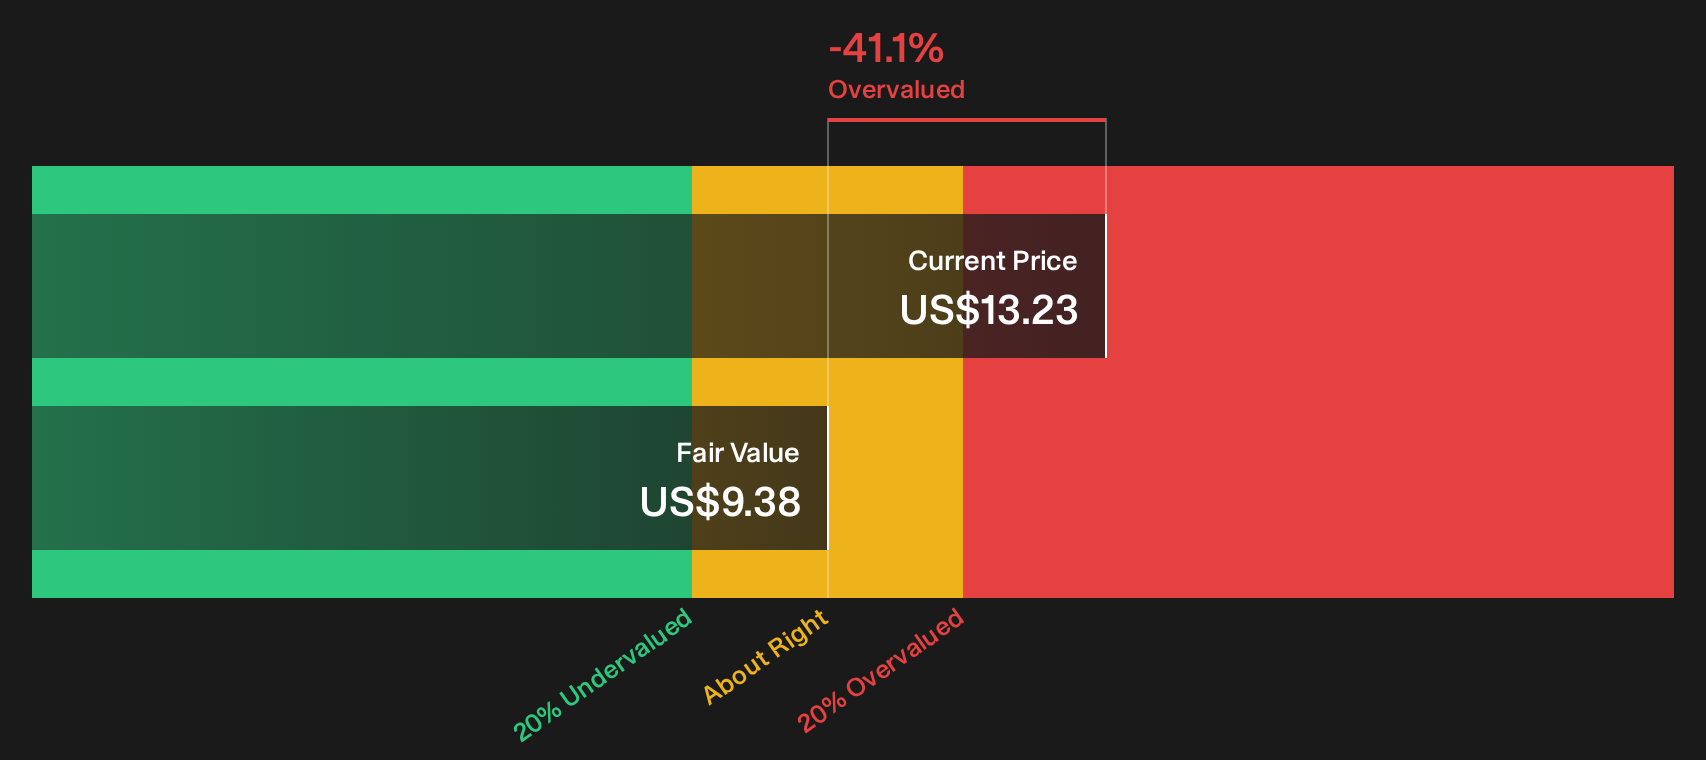
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PG&E for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on PG&E so far, and the real edge comes from seeing the same data through your own lens. Take a moment to weigh both the concerns and the upside, then ground your view in the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PG&E?
If you stop with PG&E, you risk missing out on other setups where quality, price and risk line up in far more compelling ways.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters for fundamentals many investors overlook until it is too late.
- Hunt for mispriced quality by using the 30 high quality undervalued stocks to surface companies where cash flows and balance sheets pull in the same direction.
- Explore potential income ideas through the 7 dividend fortresses, focusing on businesses that pair higher yields with an emphasis on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com