
How Investors May Respond To Flowers Foods (FLO) Falling Unit Sales
- Flowers Foods, the maker of Wonder Bread and other packaged bakery products, has seen unit sales shrink for about two years, alongside a forecast 3.3% revenue decline over the next 12 months, while earnings per share have fallen 24.3% annually over the past three years.
- The combination of rising sales and falling earnings at Flowers Foods suggests new volumes are less profitable, which points to operational pressure rather than just softer demand headlines.
- We will now look at how Flowers Foods' investment narrative holds up in light of weaker unit volumes and earnings pressure.
Scan beyond Flowers Foods and compare these pressures with hand-picked packaged food and staples companies using our 30 resilient stocks with low risk scores to see which businesses pair resilience with cleaner financial profiles.
Flowers Foods Investment Narrative Recap
To own Flowers Foods, you need to believe the portfolio shift toward Better For You bread and snacks can offset pressure in traditional loaves and weak unit trends. The recent update that unit volumes have been shrinking for about two years while revenue is forecast to dip 3.3% reinforces that execution risk. It keeps the spotlight on whether mix and pricing can keep earnings from being squeezed further.
The near term catalyst remains clear. Flowers Foods needs to stabilize core loaf bread, where softness has already weighed on comparable net sales and margins. The biggest current risk is that declining units, higher diesel and packaging costs, and a high dividend that is not well covered by earnings leave little room for error in funding this reset.
With no fresh corporate announcements tied directly to this news, the most relevant reference point is management’s prior cost removal program and balance sheet work. Roughly US$200 million of expenses have already been cut, with an additional US$20 million tailwind expected into 2027, alongside a US$400 million facility to handle the October 2026 bond maturity and a dividend reset aimed at reducing leverage.
Those earlier actions frame how Flowers Foods can respond to ongoing volume and earnings pressure. Investors will likely watch whether further restructuring of the portfolio toward Better For You bread, Simple Mills, snacking and Wonder branded cakes, as well as any incremental efficiency moves, can offset weaker fresh bread units while also supporting interest costs, debt reduction and the current dividend commitment.
Flowers Foods is modeled to reach US$5.1b in revenue and US$129.2m in earnings by 2029, with analysts assuming fairly flat annual revenue trends and an earnings increase of about US$74m from roughly US$55.2m today.
Uncover why Flowers Foods' fair value indicates a 20% potential upside to its current price that could narrow quickly.
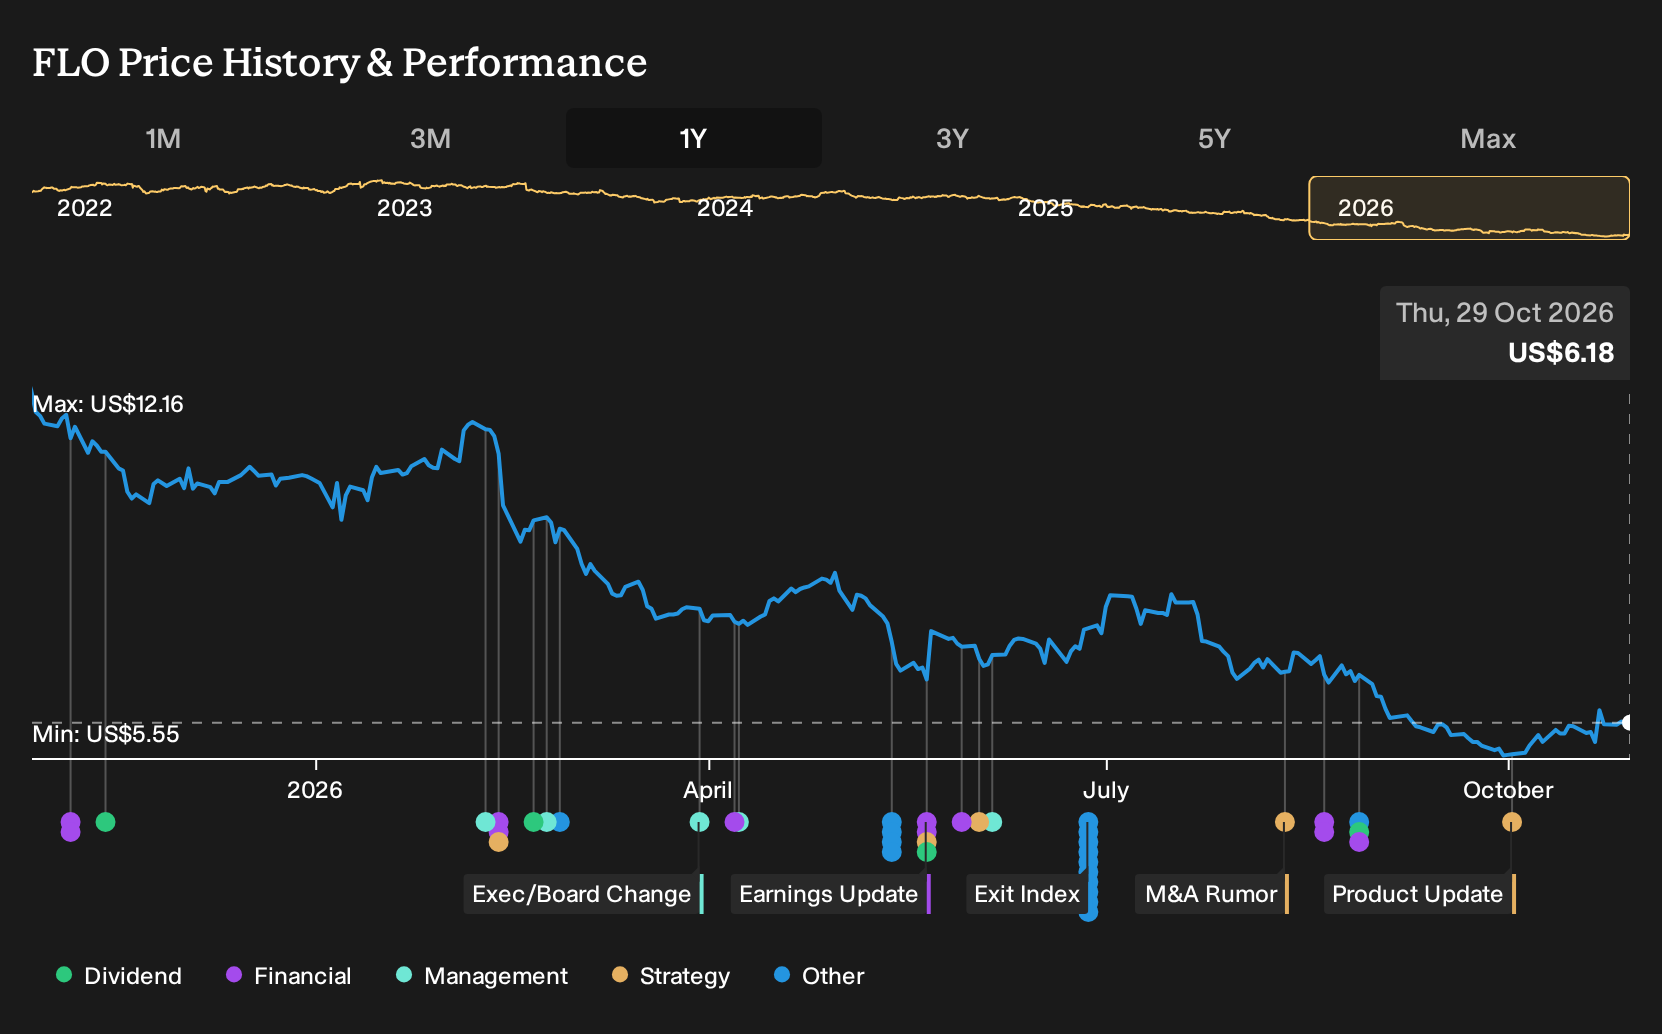
Exploring Other Perspectives
One alternate view focuses less on Better For You momentum and more on sustained volume and cost pressure at Flowers Foods. The most bearish analysts were already modeling revenue drifting to about US$5.0b and earnings of roughly US$103.8m by 2029. That is a far more cautious story, and the latest volume hit could push those opinions even further apart. Readers can compare these contrasting setups and decide which assumptions feel closer to their own expectations.
Explore 7 other Flowers Foods fair value estimates, including one that suggests as much as 19% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Flowers Foods research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Flowers Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flowers Foods' overall financial health at a glance.
Looking For More Ideas Beyond Flowers Foods?
If the mixed picture at Flowers Foods has you thinking about portfolio balance, it can help to line it up against other businesses with very different risk and income profiles. The Simply Wall St Screener lets you scan for stocks that fit your own filters so you can pressure test Flowers Foods against a wider opportunity set.
- Prefer steady operators with limited balance sheet strain and fewer red flags? Then start with a 30 resilient stocks with low risk scores that focuses on resilience over excitement.
- If value is your priority and you want companies where quality and price intersect more cleanly, sort through our 30 high quality undervalued stocks to see which stocks line up with that lens.
- For readers who care most about income, use the 7 dividend fortresses that zeroes in on higher yielding payers with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com