
Prysmian (BIT:PRY) Stock Faces Q3 Earnings Strength And Full Valuation
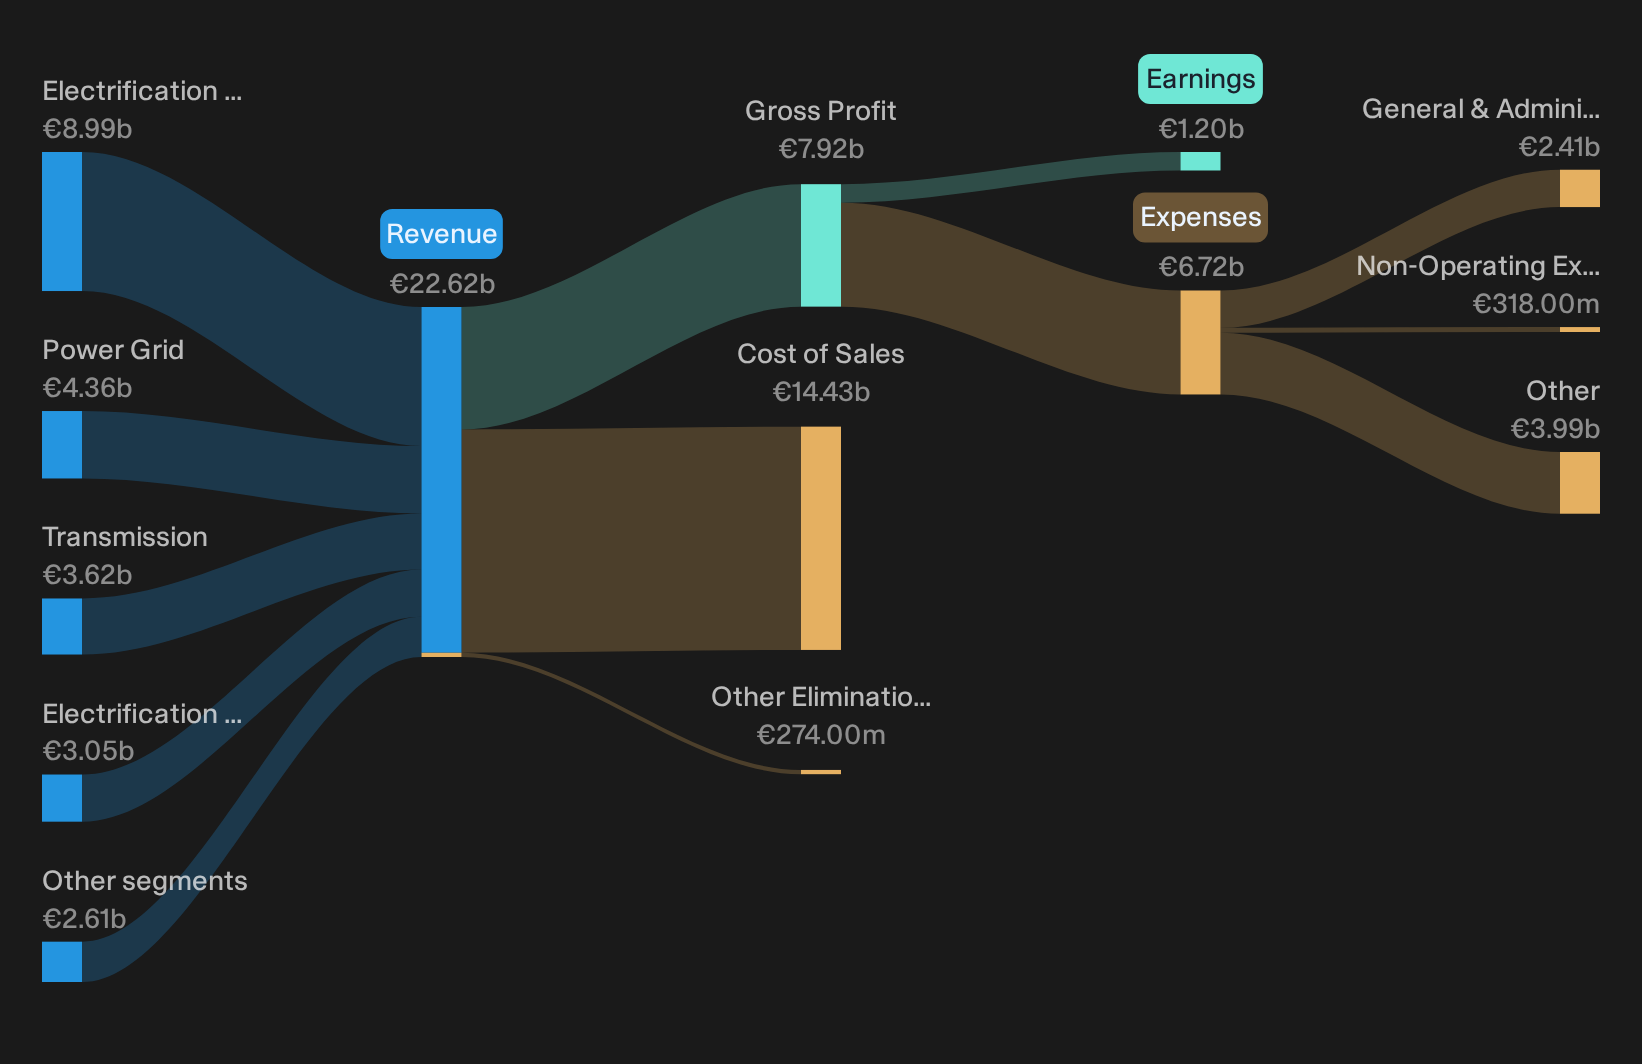
Prysmian stock closed at €110.4 after Q3 2026 earnings, leaving traders to weigh a flat near term against a much louder story in the numbers. The group posted quarterly revenue of €6,435m and basic earnings per share of €1.31, backed by an adjusted EBITDA update that management calls the best quarter yet. In the short term, the share price reaction looks muted compared with that earnings punch. Over a longer horizon, investors are wrestling with a P/E of 27x and a discounted cash flow value only slightly above the current quote, which keeps the debate firmly open.
Impressed by Prysmian's strong Q3 earnings punch but uneasy about paying 27x P/E for a stock that screens close to its DCF value? Compare that trade off with a curated 201 high quality undervalued stocks to see how other quality names line up on price versus fundamentals.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €6,435m vs. €4,942m (up 30.2%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): €433m vs. €235m (up 84.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): €1.31 vs. €0.82 (up 59.4%)
- Adjusted EBITDA (Q3 2026 vs. Q3 2025): €851m vs. approximately €651m (up approximately 30%), with an implied margin of about 17% in Q3 2026
Prysmian hit its 2028 goals two years early. Ask Charlie what put Prysmian ahead of 2028 targets.
Prysmian bull case: contracts and mix shift on trial
The upbeat story hinges on Digital Solutions and electrical infrastructure becoming heavier profit engines for Prysmian.
"Expansion of long term optical data center contracts, including more than €10b of committed optical revenues with a €5.5b Molex agreement and capacity investments of over €1b in US fiber, positions Prysmian to grow Digital Solutions revenue and lift segment EBITDA margins toward the guided 25% to 30% range."
Q3 shows that thesis starting to show in the numbers. Digital Solutions margins run above 25%, group adjusted EBITDA hits a record, and guidance for full year EBITDA and free cash flow steps higher.
Prysmian bear case: high expectations and hidden weak spots
Skeptics worry that relying on well publicised projects and deals leaves Prysmian exposed if less visible units lag.
"A large share of the positive story now rests on businesses and contracts that are heavily disclosed, such as long term optical agreements and the Atkore acquisition, while less detail is provided on other parts of the portfolio."
The latest quarter still shows moderate Power Grid progress and margin recovery tied to easing inflation rather than clear outperformance, while backlog softness in Italy hints at timing risk. With EBITDA already ahead of earlier targets and guidance lifted, any stumble in these quieter segments could matter more from here.
One Narrative disagrees with today's price. → See where this Narrative says Prysmian should trade.
Hunt For Quiet Mispricings
Prysmian just reported Q3 results while the share price reaction stayed muted. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 21% below our estimate - targets cleaner fuel vessels for freight customers and pursues record order backlogs.
- Company 2 - 40% below our estimate - turns basic web hosting clients into multi subscription users as agentic AI tools expand across its platform.
- Company 3 - 32% below our estimate - shifts packaging customers toward higher margin composite and clean energy products as automated capacity ramps up.
Three companies from the same screener. Open every one of the 201 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com