
Hilton Worldwide Holdings (HLT) Lifted Guidance And Expanded In Nordics, Is It Fully Priced?
What Hilton’s fresh earnings, guidance and product moves signal for shareholders
Hilton Worldwide Holdings (HLT) is back in focus after a trio of updates that matter for anyone tracking the stock. Fresh earnings numbers, new guidance and loyalty changes all landed together.
Recent moves in Hilton Worldwide Holdings’ share price line up with that earnings beat, higher 2026 guidance and the Scandic and Pay with Points announcements, with a 10.35% 1 month share price return and a 21.83% year to date gain contributing to a 37.45% 1 year total shareholder return.
Scan the hotel and travel peers that currently screen as 30 high quality undervalued stocks and see how Hilton Worldwide Holdings stacks up against other potential breakout candidates in the sector.
Hilton Worldwide Holdings is already up sharply on the back of fresh earnings, richer 2026 guidance and new loyalty perks. The real puzzle now is whether that surge captured most of the value or still leaves meaningful upside on the table.
Price-to-Earnings of 46.7x: Is it justified?
Hilton Worldwide Holdings trades on a P/E of 46.7x, which is a rich tag when you set it against the latest close of $356.93 and what peers are priced at.
The P/E ratio compares the share price to earnings per share and, for hotel operators, it is a quick shorthand for how much investors are willing to pay for each dollar of profit. For a franchising heavy group like Hilton Worldwide Holdings, which generates fees off managed and branded properties, that multiple captures expectations around resilience, brand strength and future earnings power.
Earnings have grown 18.7% per year over the past 5 years and the business is flagged as having high quality earnings, so the market could be assigning a premium for that track record even though the latest year saw profit expansion of only 2.1%. Forecasts point to earnings growth that is not described as significant and revenue growth that is expected to run at 20% per year, so the current valuation looks like it is pricing in solid progress rather than dramatic acceleration.
The gap is wide. Hilton Worldwide Holdings sits on a P/E of 46.7x versus a 20.2x average for the US Hospitality industry and 27.7x for its peer group, while an estimated fair P/E of 26.8x suggests a level the market could migrate toward if expectations cool off from here.
Explore the SWS fair ratio for Hilton Worldwide Holdings.
Result: Price-to-Earnings of 46.7x (OVERVALUED)
Still, the Hilton Worldwide Holdings story can shift quickly if travel demand softens or if new supply and competing brands put pressure on its fee driven model.
Find out about the key risks to this Hilton Worldwide Holdings narrative.
Another view on Hilton Worldwide Holdings’ valuation
The P/E argument presents Hilton Worldwide Holdings as expensive. The SWS DCF model extends that idea further. It values the stock at $249.12 per share, which is well below the current $356.93 price and indicates an overvalued outcome under that cash flow lens.
Both methods point in the same direction, yet each relies on different assumptions about earnings power and reinvestment. The question for you is which set of assumptions appears more realistic if industry conditions or Hilton Worldwide Holdings’ growth plans change.
Look into how the SWS DCF model arrives at its fair value.
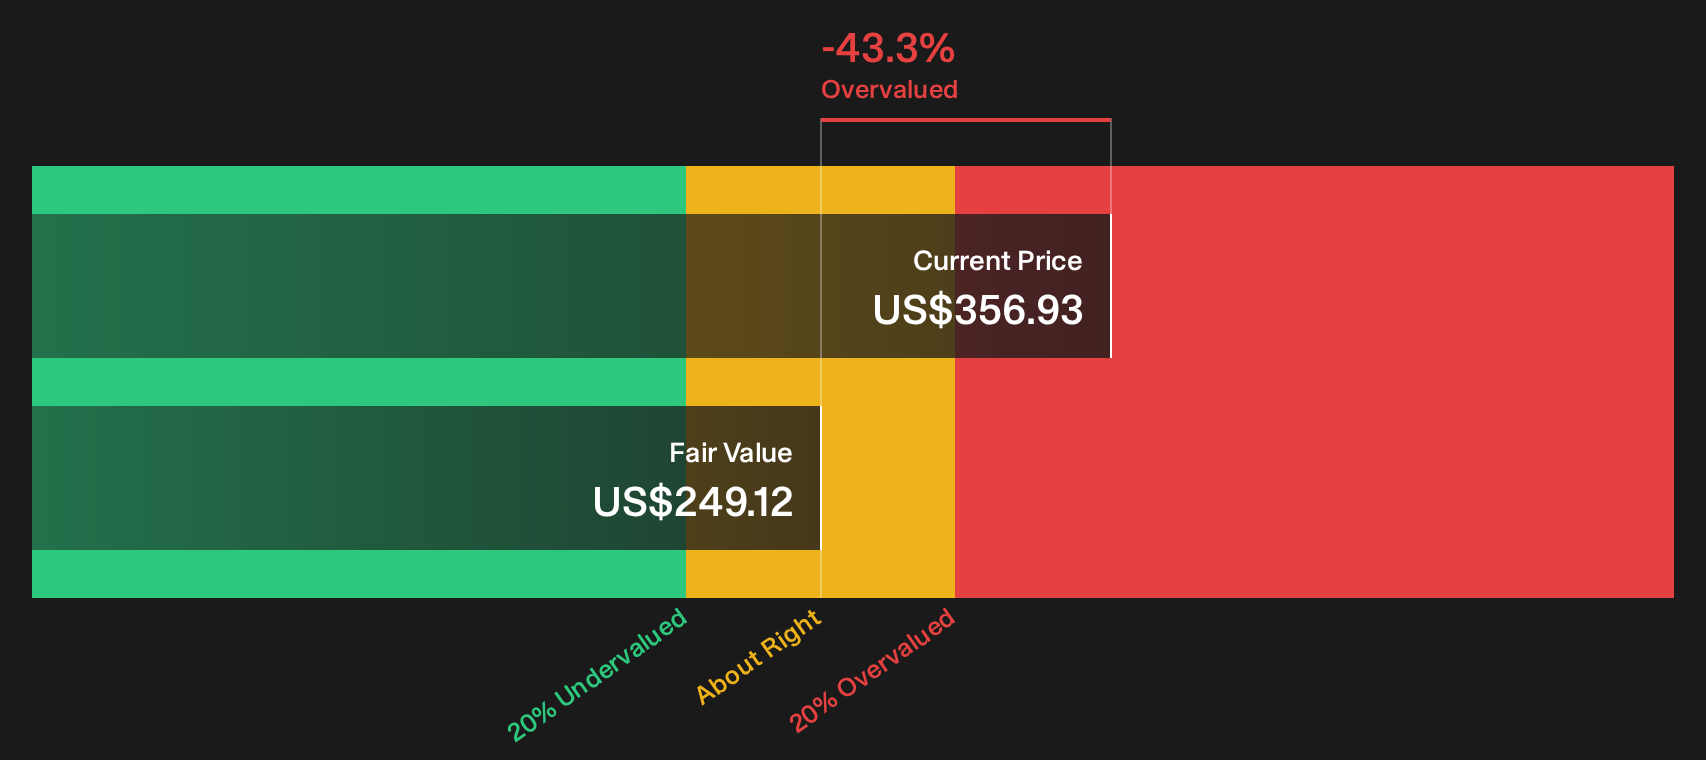
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hilton Worldwide Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hilton Worldwide Holdings so far. If you want your view to move faster than the headlines, start by weighing both the upside and the downside, and then check the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
If Hilton Worldwide Holdings now feels fully priced, do not stop your research here. Broader opportunity often sits in places the crowd has not checked yet.
- Spot potential turnaround stories early by scanning 9 elite penny stocks with strong financials that already show stronger balance sheets and cleaner financial profiles than typical micro caps.
- Target quality at a discount by reviewing the 30 high quality undervalued stocks that combine solid fundamentals with prices that do not fully reflect their financial strength.
- Anchor your portfolio with resilience by focusing on the 30 resilient stocks with low risk scores that carry lower risk scores and steadier financial characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com