
Did Earnings Beat Expectations Just Shift IMAX's (IMAX) Investment Narrative?
- IMAX is approaching its September 2026 quarter report with consensus earnings per share of $1.06, an Earnings ESP of +0.28%, and a Zacks Rank of #1, alongside commentary that recent quarters all came in above EPS expectations.
- The same coverage highlights IMAX’s focus on premium cinema demand, filmmaker partnerships, and a relatively low leverage profile as key supports for its theater network and content strategy.
- This article examines how IMAX's investment narrative is shaped by expectations for quarterly earnings and its premium cinema positioning.
Scan premium cinema opportunities that move with the same box-office momentum as IMAX by focusing on our hand-picked 18 high quality undiscovered gems universe.
IMAX Investment Narrative Recap
To own IMAX, you need to believe that premium large format keeps winning a meaningful share of theatrical spend, even as streaming, VR and gaming pull attention at home. The near term hinge is box-office throughput on its installed base and the pace of new screen deals. The upcoming earnings print matters mainly as a read on that operating momentum and on how efficiently those screens convert into cash.
The biggest short term catalyst remains a healthy slate of tentpole and local language releases that perform well on IMAX screens worldwide. The key risk is the flip side of that reliance. Any period with fewer major titles or weaker attendance can pressure box office driven revenue, EBITDA margins and free cash flow, particularly since expectations around earnings growth and profitability already look elevated.
The current focus on IMAX’s September quarter, with attention on earnings per share expectations, directly ties back to this content and attendance story. Earnings around a single period can move sentiment, although they do not change the structural drivers. For investors, the more useful signal is what management says about system installations, backlog health and demand from exhibitors for premium auditoriums.
That same update also matters for risk. Commentary around the movie slate, exposure to individual blockbusters and any signs that streaming or other at home formats are pulling viewers away from its network goes straight to the core bear case. If guidance or color on bookings implies a softer slate or slower install tempo, it could weigh on how the market views IMAX’s ability to turn its addressable 4,500 screen opportunity into steady, high margin cash flows.
IMAX Long Term Analyst Setup
IMAX's narrative projects US$520.6 million in revenue and US$104.5 million in earnings by 2029. This rests on analysts assuming 7.8% yearly revenue growth and an earnings increase of about US$63.6 million from US$40.9 million today.
Uncover how IMAX's fair value indicates a 15% potential upside to its current price. This potential could narrow quickly as sentiment shifts.
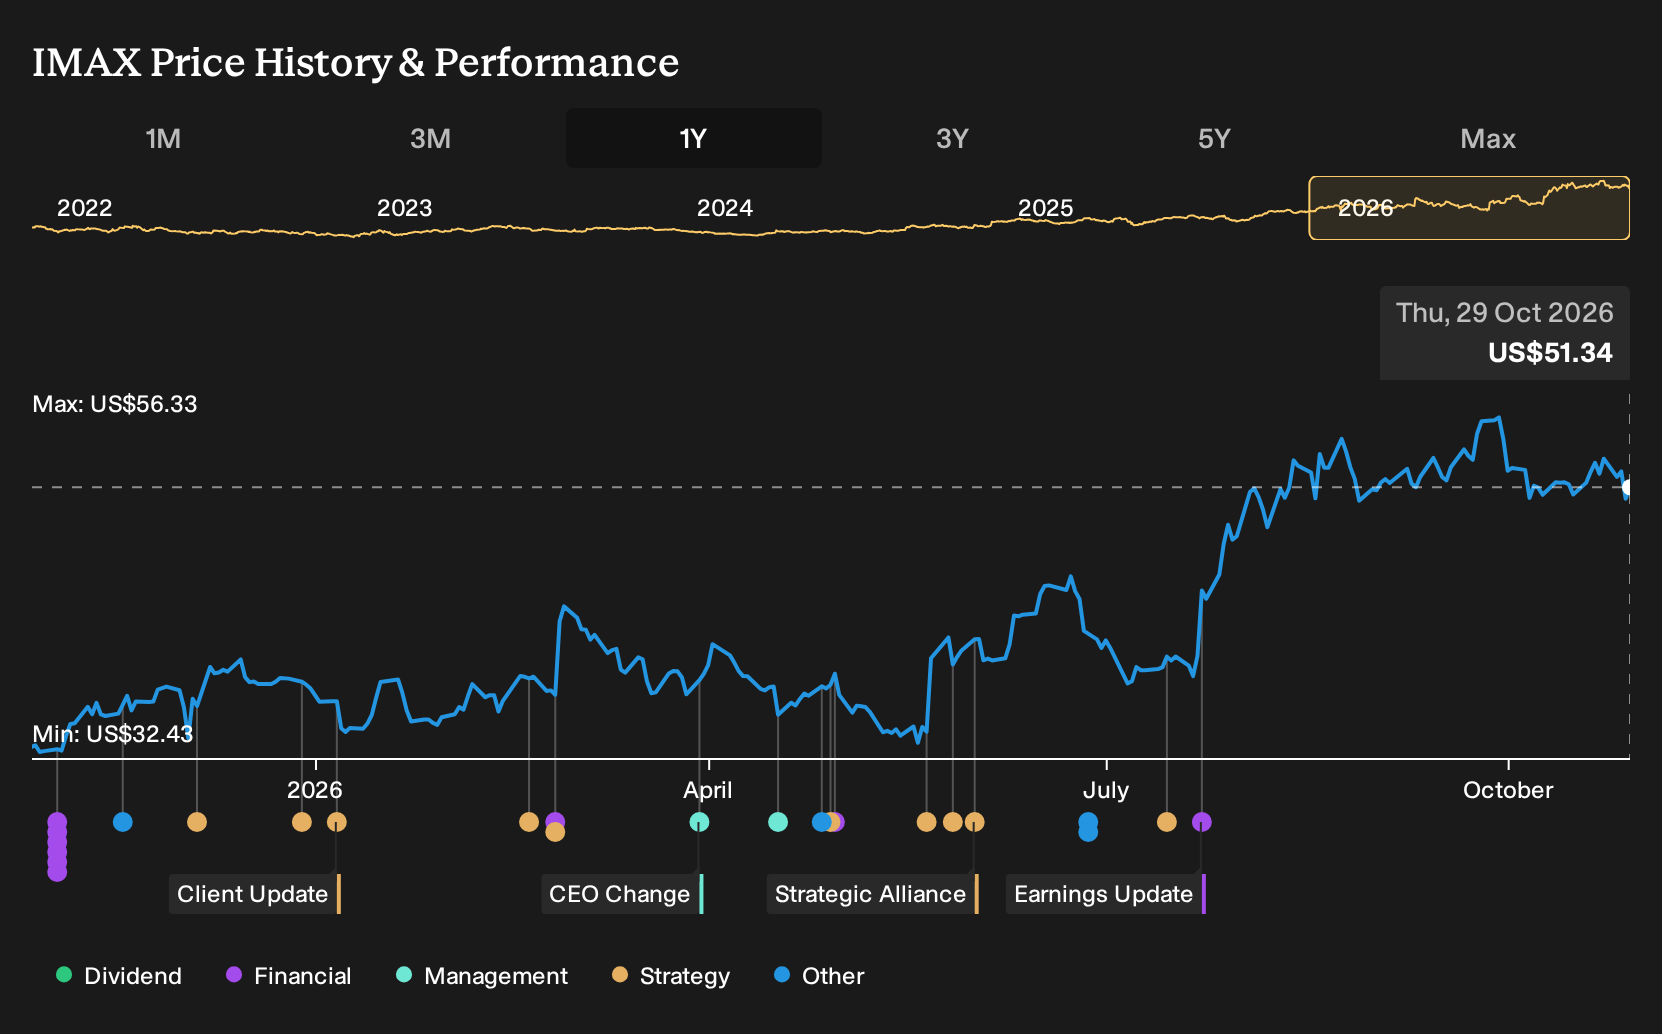
Exploring Other Perspectives
You might read the upbeat IMAX story around premium cinema, yet the lowest analysts were more focused on equipment reliability as a drag on the thesis. They were penciling in about US$514.7 million of revenue and US$105.2 million of earnings by 2029. Those forecasts came before this earnings news, so views may change as fresh information becomes available.
Explore 2 other IMAX fair value estimates, including one that suggests it could be worth just $59.17.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your IMAX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for IMAX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IMAX's overall financial health at a glance.
Looking For More Ideas Beyond IMAX?
If the IMAX story has you thinking about where premium experiences, balance sheets and income potential intersect, it can help to widen the lens and compare it with other listed businesses.
- For investors hunting for mispriced quality, check out a curated set of 30 high quality undervalued stocks that pair robust fundamentals with what may be undemanding valuations.
- If capital preservation ranks high on your list, scan a 30 resilient stocks with low risk scores that screens for resilience on both financial strength and volatility.
- Those who care about financial stability first can start with a list of solid balance sheet and fundamentals (23 results) to see companies that keep debt and core funding risk in tighter check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com