
Comfort Systems USA (FIX) Beats In Q3, Is The Pullback Opening A Valuation Gap?
Comfort Systems USA (FIX) just paired a strong third quarter earnings release with a planned CFO transition and a higher dividend, giving investors fresh information on both performance and leadership continuity.
Comfort Systems USA’s share price has pulled back sharply over the past month, with a 30 day share price return of down 20.35% and a 90 day share price return of down 23.33%, even though the year to date share price return is up 32.14%.
That disconnect sits against a backdrop of strong longer term total shareholder returns, with a 1 year total shareholder return of 37.96% and a 3 year total shareholder return above 6x. This indicates that sentiment had been very optimistic going into this recent earnings season.
The combination of a softer short term share price, a higher dividend and recent results suggests investors are recalibrating expectations rather than abandoning the Comfort Systems USA story, as markets assess what the latest earnings and leadership news might mean for future growth and risk.
Scan other construction and infrastructure contractors that are showing similar momentum in earnings and order books in our curated list of 42 power grid technology and infrastructure stocks.
Comfort Systems USA now appears to be a high quality operator facing a much more challenging question. After a sharp pullback following very strong results, is the stock still priced for perfection or starting to offer real value?
Most Popular Narrative: 36.7% Undervalued
Compared with the last close at $1,326.23, the most followed narrative pegs Comfort Systems USA’s fair value at $2,095, implying a wide valuation gap built on strong backlog and cash generation assumptions.
Strong gross margin levels in both Mechanical and Electrical, together with nearly US$1b of free cash flow in Q2 2026 and a net cash position of more than US$1.8b, give Comfort Systems USA room to keep investing roughly 5% of revenue in growth projects and acquisitions that can support future earnings and cash generation.
See why 93 investors see Comfort Systems USA as 37% undervalued.
Result: Fair Value of $2,095 (UNDERVALUED)
Still, the Comfort Systems USA narrative could be hit if data center and semiconductor build programs slow, or if sector wide P/E compression persists despite solid execution.
Find out about the key risks to this Comfort Systems USA narrative.
Another View: What Multiples Say About Comfort Systems USA
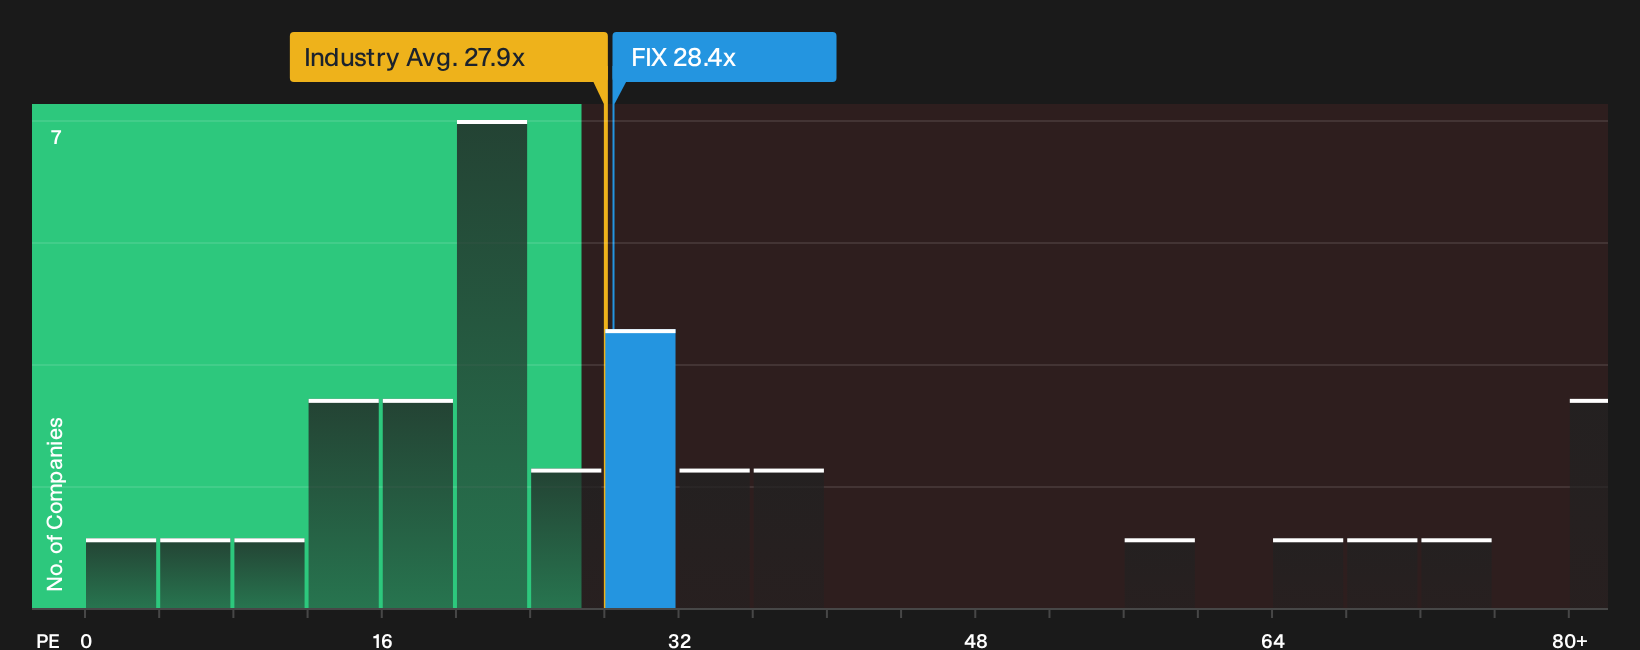
The community narrative leans on a fair value of $2,095, yet the current P/E of 28.4x already sits slightly above the US Construction industry at 27.9x and below peers at 35.5x, while the fair ratio points to 40x. Is that a margin of safety or a premium with less room for error?
To stress test that question against hard numbers, check how the valuation stacks up in our full breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Comfort Systems USA is clearly split, with investors weighing meaningful risks against appealing upside. Act promptly and review the full picture for yourself by checking the balance of 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Comfort Systems USA?
Do not stop at Comfort Systems USA. One way to sharpen your next move is to compare it with other high quality opportunities that investors are already tracking.
- Target resilient upside by scanning a 30 resilient stocks with low risk scores that can help you focus on companies where downside risk scores stay contained.
- Hunt for potential mispricing by using the 18 high quality undiscovered gems and see which businesses with strong fundamentals are not yet crowded trades.
- Strengthen your core holdings by filtering for a list of solid balance sheet and fundamentals (23 results) so you are less likely to be caught off guard by weak finances when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com